|
onlinetaxupdate team wish to express sincere thanks to all the readers, authors, subscribers for the support extended to us. Please share your feedback at
|
taxupdate.otu@gmail.com or 7738647904
|
Newsletter 131 dated 19.08.2024
|
|
|
|
|
|
|
|
|
Dear Reader,
|
Please find newsletter for your reading and reference.
|
|
Index of the Newsletter
- Recent updates
- Budget Posts
- Article
- Lawgics by Ms.Nidhi Aggarwal
- GST Notes by CMA Anil Sharma
- GST Daily by CA Pradeep Modi
- PPT/Handbook
- GST/IT/Customs in media
- Latest Update - Recap
|
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Instruction no. 01/2026-GST dated 03.08.2026 regarding Coordination with State Mining Authorities for sharing information relating to illegal mining and transportation of minerals.
|
|
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Instruction no. 06/2025-GST dated 03.10.2025 regarding Provisional sanction of refund claims on the basis of identification and evaluation of risk by the system
|
File No.: CBIC-20006/4/2025-GST
Government of India
Ministry of Finance
Department of Revenue
Central Board Indirect Taxes & Customs
GST Policy Wing
|
Instruction No. 06/2025-GST dated 03.10.2025
|
All the Principal Chief Commissioners / Chief Commissioners of Central Tax
|
Subject: Provisional sanction of refund claims on the basis of identification and evaluation of risk by the system - reg.
|
The 56th meeting of the Goods and Services Tax Council held on 3rd September 2025, recommended amendment in rule 91(2) of CGST Rules, 2017 to provide for sanction of 90% of refund claimed on provisional basis by the proper officer on the basis of identification and evaluation of risk by the system. In addition, a proviso has been inserted in rule 91(2) to provide that, on case-by-case basis, where the proper officer is of the opinion that in a particular case, provisional refund should not be granted, he can, for reasons to be recorded in writing, instead of grant of refund on provisional basis, proceed with detailed examination of the application. Further, vide notification No. 14/2025-Central Tax dated 17.09.2025, category of registered persons has been notified under section 54(6) of the CGST Act, 2017, who shall not be allowed refund on provisional basis for zero rated supplies.
|
2. In order to ensure uniformity in the implementation of the provisions of the Act across field formations and to streamline the process of GST refunds, the Board, hereby issues the following instructions with respect to processing of refund claims, filed with the proper officer, on account of zero rated supply of goods or services or both.
|
3. Manner of processing refund applications:
|
3.1 While processing refund applications, the following may be ensured:
|
a. The refund application, consequent to its filing, shall continue to be processed as per extant guidelines till the issuance of FORM GST RFD-02 or FORM GST RFD-03, as the case may be. The extant timeline prescribed for the issuance of FORM GST RFD-02 or FORM GST RFD-03, as the case may be, should be strictly adhered to.
|
b. Categorization of refund applications as “low-risk” on the basis of risk score provided by the system shall be taken into account and 90% of the refund amount claimed shall be sanctioned on provisional basis in such cases.
|
c. It may be noted that once an acknowledgment has been issued in FORM GST RFD-02, scrutiny is not required to be done for low risk refund applications for sanctioning of refund on provisional basis unless the said refund application is covered under the first proviso to rule 91(2) of the CGST Rules, 2017, whereby the officer, for reasons to be recorded in writing, may proceed with the examination of the application in accordance with the provisions of rule 92, instead of grant of refund on provisional basis.
|
d. For refund applications, which are not categorised as “low-risk” by the system, refund shall not be sanctioned on provisional basis and in such cases, the proper officer shall proceed with detailed scrutiny of refund application and further action as per the extant guidelines.
|
3.2 The statutory conditions prescribed for grant of provisional refund, including non-eligibility of the notified category of registered persons under section 54(6) vide notification No. 14/2025-Central Tax dated 17.09.2025, the requirement under rule 91(1) regarding non-prosecution, shall continue to be applicable in these cases. Further, as no adjustment or withholding of refund, as provided under sub sections (10) and (11) of section 54 of the CGST Act, can be done in respect of the provisionally sanctioned amount, therefore, in such cases, the proper officer, instead of granting refund on provisional basis, may process and sanction refund on final basis at the earliest and recover the amount from the amount so sanctioned. Also, provisional refund may not be sanctioned where, in respect of any previous refund application filed by the claimant, the issue involved is pending in an appellate forum, or where a show cause notice is issued or where an order has been passed but matter has not attained finality.
|
3.3 It is clarified that as the said amendment has been made for trade facilitation, therefore the said proviso to rule 91(2) of the CGST Rules, 2017 may be used sparingly and on case-to-case basis, so that the provisional refund is not denied merely on the basis of presumptive reason(s), initiation of routine proceedings such as scrutiny etc.
|
3.4 It also needs to be noted that if, on detailed examination, it appears to the proper officer that the refund amount sanctioned provisionally is more than the refund amount finally found admissible, in such case, the proper officer shall issue a show cause notice to the applicant, in FORM GST RFD-08, under section 54 of the CGST Act, read with section 73 or 74 or 74A of the CGST Act, as is presently being done.
|
4. As the amendment in rule 91(2) of CGST Rules, 2017 has been notified vide notification No. 13/2025 Central Tax dated 17.09.2025 to come into effect from 01.10.2025, therefore the provisions related to risk based sanction of provisional refund shall be applicable for all refund applications filed on or after 01.10.2025.
|
5. It is worthwhile to note that the GST Council, in its 56th meeting, has also recommended amending Section 54(6) of the CGST Act, 2017, to provide for sanction of 90% of the refund amount claimed on provisional basis, in case of refund claims filed on account of inverted duty structure (IDS), similar to the provisions in place for zero-rated supplies. However, the said amendment to the Act will be incorporated through the forthcoming Finance Act and States will also be required to pass the corresponding amendments in their respective legislations, which will take time.
|
5.1 Therefore, as an interim measure of trade facilitation, it has been decided by the Central Government that till this amendment in the Act is effected, in case of refund applications filed on account of IDS, on or after 01.10.2025, 90% of the refund amount so claimed may be sanctioned on provisional basis in similar manner as is being sanctioned provisionally for refund claims filed on account of zero-rated supplies.
|
5.2 The manner for processing such refund applications shall be the same as specified in para 3.1 to para 3.4 above. Further, the statutory conditions prescribed for grant of provisional refund in case of zero rated supplies shall equally apply in these cases.
|
5.3 It is further stated that the functionality for issuance of provisional refund in such cases has been made available by GSTN, on lines similar to the provisional refund processing for refund applications filed on account of zero rated supply of goods or services or both.
|
6. The implementation of this instruction may be supervised by the jurisdictional Principal Commissioner/ Commissioner and a report in this regard may be sent to the jurisdictional Principal Chief Commissioner/ Chief Commissioner. Principal Chief Commissioner/ Chief Commissioner should ensure that the trade facilitation measures decided upon by the Government are implemented in letter and spirit and there is proper monitoring regarding the same.
|
7. Difficulty, if any, in implementation of this instruction may please be brought to the notice of the Board.
|
(Gaurav Singh)
Commissioner (GST)
|
Copy to: Additional Secretary, GST Council Secretariat with a request to circulate to State GST formations, which may, if deemed appropriate, issue similar instructions within their jurisdictions to ensure uniformity and effective implementation.
|
|
|
|
|
|
Office of the Commissioner of Commercial Taxes, Nandanam, Chennai issued Circular No. 07/2026-TNGST dated 25.06.2026 regarding GST- Return Scrutiny under Section 61 of the TNGST Act, 2017 and adjudication proceedings - Prior approval for suo moto scrutiny notices and ex parte orders.
|
Detailed guidelines were issued to the Proper officers for adjudication in the Assessment Circles, in the Circular cited, to make adjudication process more transparent, reduce the litigations and realize revenue.
|
In this direction, system generated scrutiny notices based on risk parameters have been made available to the Proper Officers to ensure uniformity and monitoring of the return scrutiny process. Instructions have also been issued to all Proper Officers to process the system-generated scrutiny notices by following the provisions of the GST Acts and Rules and training has been imparted for adherence to quality standards in the adjudication process.
|
The scrutiny notices generated by the IT wing of the department and made available are detailed below:
|
|
|
|
|
|
OFFICE OF THE COMMISSIONER OF STATE TAXMAHARASHTRA STATE, MUMBAI issued NOTIFICATION NO: - SGST/e-way bill/02/2025-26 dated 20.02.2026 Waiving off requirement of e-way bill for motor vehicles for road testing where goods are transported for reasons other than by way of supply under sub-rule (5) of rule 138A of MGST Rules, 2017.
|
M/s. Tata Motors Limited, having principal place of business at TATA MOTORS LIMITED, Nigadi Bhosari Road, Pimpri Chinchwad, Pune, Maharashtra, 411 018. (GSTIN: 27AALCT0864B1ZE) (hereinafter called as ‘taxpayer’), have made a representation vide their letter GST/MH/056 dated 13th November 2025. for waiving off requirement of e-way bill for motor vehicles for road testing where goods are transported for reasons other than by way of supply under sub-rule (5) of rule 138A of MGST Rules, 2017(hereinafter referred as MGST Rules, 2017).
|
Whereas I, Asheesh Sharma, Commissioner of State Tax. Maharashtra State, am of the opinion that the difficulties being faced by the ‘taxpayer’ are genuine and require due consideration. Now, therefore I, Asheesh Sharma, Commissioner of State Tax, Maharashtra State, in exercise of the powers conferred upon me under sub-rule (5) of rule 138A of the MGST Rules, 2017, am pleased to issue this notification for grant of permission to M/s. Tata Motors Limited. having principal place of business at TATA MOTORS LIMITED, Nigadi Bhosari Road, Pimpri Chinchwad, Pune, Maharashtra, 411 018 (GSTIN: 27AALCT0864B1ZE) to waive the requirement of e-way bill for motor vehicles to perform various road tests across India, subject to the following procedure and conditions as mentioned below.
|
(i) The ‘ taxpayer ’ shall execute a bond sufficient to cover the value of the motor vehicle being cleared for the purpose of road testing in a calendar month, with the Jurisdictional State Tax Officer, PIMPRI_702, Division - PUNE_SOUTH_EAST, Zone - PUNE_SOUTH_WEST, PUNE undertaking to follow all the conditions mentioned hereunder;
|
(ii) Motor vehicles shall be removed by the ‘taxpayer’ for the purpose of road test under a delivery challan, duly signed by the authorized signatory of the “taxpayer”;
|
(iii) The exemption to carry delivery challan instead of e-way bill is limited only to transportation of motor vehicles for reasons other than by way of supply and limited to road test of such motor vehicles;
|
(iv) The delivery challan shall be induplicate, pre-authenticated and having running serial number for every calendar year and printed format and shall contain the following information.
|
(a) The name and address of the “taxpayer”, it’s ‘GSTIN’
|
(b) Name of the jurisdictional officer, Division and Zone with whom the taxpayer is registered for the purpose of GST and notification number under which permission under sub-rule (5) of rule 138(A) of MGST Rules, 2017 for such removal has been given;
|
(c) The description, vehicle serial number/ engine number/ chassis number, as the case may be, to identify the vehicle which has been cleared for the purpose carrying out road test along with the value of such motor vehicle;
|
(d) The date of dispatch of such motor vehicle for road test and probable time line for return of the motor vehicles to its place of clearance;
|
(v) The Motor vehicle/ transport equipment will also carry trade plate as prescribed under Central Motor Vehicles Rules, 1989 or under any other law in force for the purpose of undertaking testing of such motor vehicle as the case may be;
|
(vi) The ‘taxpayer’ shall maintain proper records to correlate the dispatch and return of the motor vehicles sent for road testing. If at any point of time the value of the motor vehicles cleared for road test exceeds the amount for which the bond has been executed, the ‘taxpayer’ shall execute a separate bond of differential value with the concerned, before removal of the motor vehicle for testing purpose;
|
(vii) The taxpayer’ shall submit to the Jurisdictional State Tax Officer, PIMPRI_702, Division - PUNE_SOUTH_EAST, Zone - PUNE_SOUTH_ WEST, PUNE a monthly account containing the details of all motor vehicles sent and received back after road testing;
|
(viii) The ‘taxpayer’ shall furnish any additional relevant information pertaining to the instant subject matter which may be required by the Jurisdictional State Tax Officer, PIMPRI_702, Division-PUNE_SOUTH_EAST, Zone - PUNE_SOUTH_WEST, PUNE.
|
2. The ‘ taxpayer ’ shall be fully responsible and accountable for the taxable goods so removed without generation of e-way bill under sub-rule (5) of rule 138(A) of MGST Rules, 2017 as permitted under this notification.
|
3. If the above said conditions are not adhered to or are violated, the impugned permission shall be revoked/withdrawn without any prior intimation.
|
4. This notification is valid for financial year 2025-26, i.e. up to 31st March 2026
|
|
|
|
|
|
|
|
Odisha GST Department issued Office Memorandum no. 2579 dated 31.01.2026 regarding Guidelines relating to recovery of tax due from works contract through WAMIS module.
|
|
|
|
|
|
|
|
The Office of the Commissioner of the Commercial Taxes Telangana State -Hyderabad issued Standard Operation Procedure (SOP) In pursuance to the proceedings of the Hon’ble High Court of Telangana in WP No.20731 & 24077 of 2025 dt. 08.09.2025.
|
GOVERNEMNT OF TELANGANA
COMMERCIAL TAXES DEPARTMENT
|
OFFICE OF THE
COMMISSIONER OF COMMERCIAL TAXES
TELANGANA STATE, HYDERABAD.
|
CCT’s Ref.No.LIV(2)/33/2025, dated 14.10.2025
|
The attention of the Additional Commissioner (ST) (CCW, EIU & Statistics) is invited to the SoP (Standard Operating Procedure) framed to rectify the anomalies created by multiplication of Show Cause Notices and orders as per the directions of the Hon’ble High Court of Telangana and she is requested to take steps to place the approved SoP (Standard Operating Procedure), which is enclosed here with, in the Public Domain i.e., on the C.T. Department Website immediately by scrolling the SoP as New in red font, as the next date of hearing in W.P. No. 20731 and 24077 of 2025 is on 15-10-2025 and the SoP (Standard Operating Procedure) is to be placed in the Public Domain i.e., on the C.T. Department Website by that time.
|
Sd/- M. Raghunandan Rao, I.A.S.
Commissioner of Commercial Taxes
|
To
The Additional Commissioner (ST) (CCW, EIU & Statistics),
O/o Commissioner of Commercial Taxes,
Telangana, Hyderabad.
|
GOVERNMENT OF TELANGANA
COMMERCIAL TAXES DEPARTMENT
|
Office of the
Commissioner of Commercial Taxes
Telangana State :: Hyderabad
|
CCT’s Ref.No.LIV(2)/33/2025, Dt:14-10-2025
|
Sub: Prevention and rectification of multiplicity of Orders for the same cause of action/issue, period and taxable event under the TGST Act, 2017 – Standard Operating Procedure (SOP) – Issued – Regarding
|
In pursuance to the proceedings of the Hon’ble High Court of Telangana in WP No.20731 & 24077 of 2025 dt. 08.09.2025, the following Standard Operating Procedure is issued.
|
It has been noticed in certain instances that multiple adjudication orders are issued for the same cause of action/issue, period and taxable event under the TGST Act, 2017. The attention of the concerned is drawn to the provisions of Section 161 of the TGST Act, 2017, which is extracted hereunder for ready reference:
|
Section 161. Rectification of errors apparent on the face of record.-
|
“Without prejudice to the provisions of section 160, and notwithstanding anything contained in any other provisions of this Act, any authority, who has passed or issued any decision or order or notice or certificate or any other document, may rectify any error which is apparent on the face of record in such decision or order or notice or certificate or any other document, either on its own motion or where such error is brought to its notice by any officer appointed under this Act or an officer appointed under the Central Goods and Services Tax Act or by the affected person within a period of three months from the date of issue of such decision or order or notice or certificate or any other document, as the case may be
Provided that no such rectification shall be done after a period of six months from the date of issue of such decision or order or notice or certificate or any other document.
|
Provided further that the said period of six months shall not apply in such cases where the rectification is purely in the nature of correction of a clerical or arithmetical error, arising from any accidental slip or omission:
|
Provided also that where such rectification adversely affects any person, the principles of natural justice shall be followed by the authority carrying out such rectification.”
|
On plain reading of Sec 161 of TGST Act, rectification can be done under the following circumstances.
|
The authority, who has passed or issued any decision or order or notice or certificate or any other document, may rectify any error which is apparent on the face of the record in such decision or order or notice or any certificate or any other document, either on its own motion or where such error is brought to its notice by any officer appointed under this Act or an officer appointed under the Central Goods and Service Tax Act or by the affected person within a period of three (3) months from the date of issue of such decision or order or notice or certificate or any other document as the case may be.
|
The 1st Proviso to Section 161 states that rectification, if any, shall be done within a period of six (6) months from the date of issue of decision or order or notice or certificate or any other document.
|
The 2nd Proviso to Section 161 states that the said period of six (6) months shall not apply to the cases where the rectification is purely in the nature of correction of a clerical or arithmetical error, arising from any accidental slip or omission.
|
The multiplicity of the issuance of the notices and orders for the same cause of action/issue, period and taxable event will certainly fall under the errors committed by the officers which are purely due to accidental slip or omission as specified under 2nd proviso to Section 161 of the TGST Act.
|
Therefore, the anomalies of multiplicity of notices and orders for the same cause of action/issue, period and taxable event can be rectified under 2nd Proviso of section 161 TGST Act, 2017.
|
Standard Operating Procedure (SOP):
|
1) The officers concerned can carry out rectification of any kind including rectifying the multiple orders for the same cause of action/issue, period and taxable event as prescribed U/Sec.161 of the TGST Act, 2017 within six (6) months from the date of issue of decision or order or notice or certificate or any other document.
|
2) The officers concerned can rectify the multiple orders for the same cause of action/issue, period and taxable event, by also adhering to 2nd proviso of Section 161 of the TGST Act, 2017.
|
3) The officers concerned have to delete the tax portion in the second or subsequent order for the repeated issues and retain the component which is not covered in the earlier proceedings and arrive at a single comprehensive net tax liability under SGST, CGST & IGST separately.
|
4) The officers concerned shall also take note of the fact that in the event of the second or subsequent order containing more tax liability and gets rectified by deletion of tax pertaining to repeated issues, the same shall be brought to the notice of the revisional authority for initiation of proceedings U/Sec.108 of the TGST Act, 2017, since the first order is prejudicial to the interest of revenue.
|
5) The officers concerned shall also take note of the fact that in the event of the second or subsequent order containing more tax liability and gets rectified by deletion of tax pertaining to repeated issue, the same shall be brought to the notice of the undersigned for initiation of proceedings U/Sec.107(2) of the TGST Act, 2017, since the first order is prejudicial to the interest of revenue.
|
6) The officer concerned need not exercise powers U/Sec.161 as stated supra, if the second and subsequent orders are distinct in nature, which are unconnected with the first order.
|
7) The officer concerned may also intimate the taxpayers with regard to the multiplicity of notices/orders for the same cause of action/issue, period and taxable event in order to rectify the same U/Sec.161 of the TGST Act, 2017 in addition to the information already placed in the public domain.
|
Sd/- M. Raghunandan Rao, I.A.S.
Commissioner of Commercial Taxes
|
|
|
|
|
|
|
|
OFFICE OF THE DEPUTY COMMISSIONER, DIVISION II, C.G.S.T COMMISSIONERATE, INDORE, CGO COMPLEX, SECOND FLOOR, INDORE- 452001, wrote to All taxpayers inviting them to attend Interaction/Awareness program with Hon'ble Minister of State (Finance), Govt. of India on next-Gen GST reforms.
|
As it is known to us that Government of India has unveiled next-Gen GST reforms (GST 2.0) with the am to rationalize GST rates effective from 22.09.2025. Shri Pankaj Chaudhary, Hon'ble Minister of State (Finance), Govt. of India is pleased to hold an Interaction/Awareness program with all the stakeholders viz. Industrialist, Traders and Businessman etc.
|
2. In this regard, you are cordially invited to the attend the interactive program with Hon'ble Minister on next-Gen GST reforms. Your gracious presence is highly solicited.
|
3. Schedule and Venue of the program is given below:
|
(Deputy Commissioner)
CGST & Central Excise,
Division-II, Indore
|
|
|
|
|
|
GSTN Advisory no. 672 dated 19.09.2026
|
This is an advance information to the all users – Taxpayers and Tax Officers, of GST System who use Digital Certificate Signature on the GST Portal.
|
A new version of emSigner (v3.3) is being made available for download for the purpose of providing compatibility with tokens (USB dongles) that are issued on or after 21-September-2026.
|
A. Users with valid certificates: There is no change for the users having existing valid digital certificates and their existing token (USB Dongle) are working, as of 21-Sep-2026. If your existing DSC works normally, you may continue using your current emSigner version.
|
If you encounter signing failures or if your certificate does not appear for selection despite correctly installed token drivers, upgrade to the emSigner version 3.3 by following steps given under point-B below. The emSigner version 3.3 is backward compatible to support the existing tokens (USB dongles).
|
B. Users with newly issued tokens: The users who have been issued a new token (USB Dongle) on or after 21-Sep-2026, either due to issuance of new certificate and dongle, or renewal of certificate in a new dongle, shall have to upgrade to version 3.3 of emSigner by following below steps:
|
Step-1. Please ensure that your system – desktop / laptop / AIO which on which the DSC is used for the GST System, meets the following minimum system requirements:
|
1.1 Operating system and hardware
|
Step-2.Download & install the version 3.3 of emSigner from the GST Portal by navigating to https://www.gst.gov.in/help/docsigner - the older versions of emSigner will not work for such new DSC dongles issued from 21 September 2026 onwards.
|
C. Validity and future renewal: Under CCA’s advisory, DSCs downloaded onto FIPS 140-2 dongles on or before 21 September 2026 can continue to be used until the DSC expires. That date does not automatically invalidate existing DSCs. Subsequent renewal or fresh issuance generally requires a FIPS 140-3 dongle, subject to CCA’s specified exceptions. The CCA migration advisory may be referred for more details on this aspect by navigating to https://cca.gov.in/sites/files/pdf/news/Advisory_on_Migration_from_FIPS_140- 2_to_FIPS_140-3.pdf
|
Please create a ticket on the GST Helpdesk if you need any assistance while upgrading to the emSigner version 3.3 and our teams shall get in touch for resolution.
|
|
|
|
|
|
The GST Council meeting, originally scheduled for September 12, has been postponed to October 7 due to the BRICS summit being hosted by India in New Delhi.
|
India is hosting the annual BRICS summit in New Delhi on September 12 and 13, which is expected to deliberate on a number of pressing global challenges, including the economic consequences of the West Asia crisis.
|
BRICS, originally comprising Brazil, Russia, India, China, and South Africa, expanded in 2024 to include Egypt, Ethiopia, Iran, and the United Arab Emirates, with Indonesia joining in 2025.
|
Sources said to news agency PTI that, in view of the BRICS summit, the 57th GST Council meeting has been rescheduled for October 7. The meeting will be preceded by an officers' meeting on October 5 and 6.
|
The council, chaired by Finance Minister Nirmala Sitharaman and comprising state finance ministers, would be meeting after a gap of over a year. The 56th GST Council meeting had taken place on September 3-4, 2025, during which the Centre and states decided on a major restructuring of Goods and Services Tax (GST) rates and slabs.
|
Effective September 22, 2025, GST became a two-tier structure of 5 and 18 per cent, and a highest 40 per cent rate only for ultra luxury and sin goods, replacing the four slabs of 5, 12, 18 and 28 per cent which was in place since July 1, 2017.
|
At its 57th meeting on October 7, 2026, the GST Council is likely to discuss simplification in GST registration of businesses that pass on tax credit of over Rs 2.5 lakh a month.
|
Also, automation and other changes in GST registration cancellation is also expected to be taken up by the council.
|
Currently, there is no uniformity in the procedure followed by the central GST formation and various state formations in granting GST registration to large businesses who pass on credit over Rs 2.5 lakh/month and this creates uncertainty in the minds of taxpayers.
|
The GST Council in its September 2025 meeting had already approved a simplified GST registration scheme for small and low-risk biz and the same was rolled out from November 1.
|
Small and low-risk businesses applicants whom the GST system identifies based on data analysis, or those applicants who self-assess that their output tax liability does not exceed Rs 2.5 lakh per month (inclusive of CGST, SGST/UTGST and IGST) can opt for the scheme.
|
About 1.68 crore businesses are currently registered under GST.
|
|
|
|
|
|
CBIC issued Notification No. 75 /2026-Customs (N.T.) dated 15.09.2026 regarding Fixation of Tariff Value of Edible Oils, Brass Scrap, Areca Nut, Gold and Silver
|
|
|
|
|
|
|
|
CBIC issued Notification No. 74 /2026-Customs (N.T.) dated 01.09.2026 regarding Appointment of Common Adjudicating Authority in the case of M/s. Akwel Automative Pune India Pvt. Ltd. (IEC: 3105015850) – Consolidated Adjudication of Multiple Show Cause Notices arising from SVB Investigation Report No. 198/AC/SVB/SKB/2022-23 dated 20.12.2022
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Trade Notice 28/2026-27 dated 16.09.2026 regarding Revision in Timeline for Issuance of PSIC and One-time Relaxation for Issuance of Backlog PSICs
|
Kind attention is invited to earlier Trade Notice No. 22/2026-27 dated 25.08.2026 regarding enhancements in the Pre-Shipment Inspection Agency (PSIA)/Pre Shipment Inspection Certificate (PSIC) process.
|
2. In order to facilitate smooth implementation of the revised PSIA/PSIC module, the following relaxations are hereby made to the provisions contained in the aforesaid Trade Notice:
|
i. One-time transitional arrangement for issuance of PSICs
|
A one-time relaxation of seven days from the date of issuance of this trade notice is hereby provided to the recognized PSIAs for clearing the backlog PSICs pertaining to inspections conducted prior to 25.08.2026, where such certificates could not be issued due to system restrictions introduced pursuant to the aforesaid Trade Notice.
|
ii. Revision in timeline for issuance of PSIC
|
Para 2(ii) of Trade Notice No. 22/2026-27 dated 25.08.2026 shall stand substituted with the following:
|
"The PSIC shall be generated and issued within 2 days from the date of inspection. The system shall permit generation and issuance of the PSIC only within the prescribed timeline. The PSIC uploading shall be done from the same geographical location/country where inspection is carried out."
|
3. All other provisions of Trade Notice No. 22/2026-27 dated 25.08.2026 shall remain unchanged.
|
This issues with the approval of the DG, DGFT.
|
|
|
|
|
|
|
|
The Directorate of Revenue Intelligence (DRI) seized more than 362 metric tonnes of Pakistan-origin dry dates under 'Operation Deep Manifest' during an enforcement drive targeting illicit trade conduits.
|
Acting on specific actionable intelligence, operational teams intercepted 13 cargo containers carrying the consignments at CFS Ahmad in Nashik , which a Mumbai-based commercial entity imported.
|
According to the Ministry of Finance, the shipments arrived via Jebel Ali in the United Arab Emirates, accompanied by import clearance paperwork that falsely declared the UAE as the sovereign country of origin.
|
Official findings revealed that the commercial consignment moved through a deliberate routing network designed to mask its true origin. The cargo started its maritime transit from Karachi Port in Pakistan, reaching Jebel Ali Port in the UAE abroad an initial vessel.
|
"Preliminary investigation revealed a carefully orchestrated transshipment arrangement designed to conceal the Pakistan-origin of the goods," the Ministry stated.
|
The operational breakdown showed that the illicit cargo underwent minimal physical handling in the Gulf transit hub to obscure the paper trail.
|
"The dry dates were initially shipped from Karachi Port, Pakistan, to Jebel Ali Port, UAE, in one set of containers aboard one vessel," the official statement noted.
|
Handlers in the transit zone then re-routed the shipment onto another carrier line, it state.
|
"At Jebel Ali, the goods were merely transshipped and transferred to another set of containers and loaded onto a different vessel for onward shipment to India through entities operated by Pakistani nationals," the Ministry confirmed.
|
Border and port enforcement tightened following regulatory revisions enacted by the Directorate General of Foreign Trade (DGFT) in mid-2025.
|
The Ministry mentioned that following the Pahalgam terror attack, the Government of India, in the interest of national security, imposed a complete prohibition on the direct or indirect import or transit of all goods originating in or exported from Pakistan, with effect from 02.05.2025, vide DGFT notification no. 06/2025-26 dated 02.05.2025.
|
To counter non-compliant import tactics across container terminals, central enforcement authorities launched structured surveillance protocols targeting third-party trade jurisdications.
|
"In response, DRI, under 'Operation Deep Menifest", has been consistently identifying, intercepting and seizing Pakistan-origin goods attempted to be imported into India through third-country routing," the Ministry said.
|
Customs and intelligence officials continue to track intermediate entities connected to commercial paper falsification, fraudulent routing manifests, and proxy transshipment nodes.
|
"The seizure underscores (DRI's sustained resolve to identify, disrupt and dismantle sophisticated networks seeking to circumvent trader prohibitions through misdeclaration , transshipment and manipulation of documentation, thereby safeguard national security and straightening supply chain integrity," the Ministry added.
|
|
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Notification No. 36/2026-27 dated 15.09.2026 regarding De minimis exemption from Registration-cum-Membership Certificate (RCMC) requirements for low-value exports
|
|
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Public Notice 30/2026-27 dated 14.09.2026 regarding Extension of timeline for surrender of unutilised TRQ quantity allocated for import of 10 Lakh MT of Raw Sugar
|
|
|
|
|
|
Central Board of Direct Taxes (CBDT) issued notification no. 120/2026 dated 17.09.2026 to hereby make following rules further to amend the Income tax Rules, 2026 , namely -
|
These rules may be called the Income-tax (Fourth Amendment) Rules, 2026
|
|
|
|
|
|
|
|
Directorate of Income Tax (Systems) of Central Board of Direct Taxes (CBDT) issued notification no. 3/2026 dated 15.09.2026 to prescribe Procedure for registration of reporting person/entity and submission of Form No. 98 as per rule 160 of the Income tax Rules, 2026.
|
Rule 160 of the Income-tax Rules, 2026 (hereinafter, "the Rules") specifies that every person referred to in clauses (a) and (b) of sub-rule (2), who has received any declaration in Form No. 97 in relation to a transaction specified in column 2 of Table in rule 159, shall furnish a statement in Form No. 98.
|
2. As per rule 160, the statement in Form No. 98 shall be furnished through online transmission of electronic data to a server designated for this purpose. As per sub-rule 3 of rule 160, the statement in Form No. 98 shall:
|
(a) where the declarations are received by the 30th September, be furnished by the 31st
October of that year; and
|
(b) where the declarations are received by the 31st March, be furnished by the 30th April
of the financial year immediately following the financial year in which the form is
received.
|
3. In exercise of the powers under rule 332 of the Income-tax Rules, 2026, the Director General of lncome-tax (Systems) hereby lays down the following procedure:.
|
(a) Registration and Generation of Income Tax Department Reporting Entity Identification Number (ITDREIN): The reporting person/entity is required to get registered with the Income Tax Department by logging in to the e-filing website (https://eportal.incometax.gov.in) with the log-in ID used for the purpose of filing the Income Tax Return of the reporting person/entity. The reporting person/entity needs to click on "Reporting Portal" link under "Pending Actions" tab at e-filing portal to access "Reporting Portal" for first time registration. The reporting person/entity will mandatorily be required to enter the details of form type, category and address of reporting person/entity along with the details of the principal officer.
|
On successful submission, the ITDREIN is generated and the principal officer will receive a confirmation e-mail on his/her registered e-mail address and SMS at his/her registered mobile number. There will be no option to deactivate ITDREIN, once it is generated.
|
The reporting person/entity already registered for compliance of erstwhile Form No: 61 are not required to register for Form No. 98 and the existing ITDREIN as well as the respective principal officers shall continue to remain valid. For the purpose of verification of Form No. 98, the principal officer will act as "Designated Director".
|
(b) Submission of Form No. 98: As per rule 160, a statement in Form No. 98 is required to be furnished by the reporting person/entity. The prescribed Schema, Report Generation and Validation Utility for Form No. 98 and Generic Submission Utility can be downloaded from the Reporting Portal under "Resources" tab. The prepared Statement to be filed is required to be digitally signed by and uploaded at the Reporting Portal or through Generic Submission Utility through the login credentials (PAN and password) of the principal officer.
|
(c) Submission of correction statement: In case the reporting person/entity comes to know or discovers any inaccuracy in the information provided in the statement or the defects have been communicated to the reporting person/entity through Data Quality Report (DQR) after submission of Statement, it is required to remove the defects by submitting a correction statement. The number of "Reports Requiring Correction (RRC)" will be visible against the original statement on Reporting Portal. The user can download the DQR file from the DQR column under "Statements" Tab of Reporting Portal, which can then be opened on the Report Generation Utility to find and fix the errors. The reporting person/entity needs to rectify all the defects till the number of "Reports Requiring Correction (RRC)" becomes zero within the specified period.
|
(d) Deletion of Submitted Reports in a statement: In case the reporting person/entity wishes to delete the inadvertently filed reports within a statement, it can choose the statement type as "Deletion Statement" and file all such reports within a single statement to be deleted with exact previously filed values against each field. The manner of filing Deletion Statement shall be similar to submission of correction statement.
|
(e) Security, archival and retrieval policies: The reporting person/entity is required to document and implement appropriate information security policies and procedures with clearly defined roles and responsibilities to ensure security of submitted information and related information/documents. The reporting person/entity is also required to document and implement appropriate archival and retrieval policies and procedures with clearly defined roles and responsibilities to ensure that submitted information and related information/documents are available promptly to the competent authorities.
|
This notification shall come into force with effect from /5~f September 2026. The Reporting for F.Y. 2025-26 and earlier years (including correction/ deletion) will continue as per the provisions of the Income-tax Act, 1961 and the Income-tax Rules, 1962, through Form No. 61 as per Notification No. 2 of 2018 dated 05.04.2018.
|
|
|
|
|
|
CBDT has issued Notification No. 114/2026 dated 14.08.2026, notifying the rules and prescribed forms under the Foreign Assets of Small Taxpayers Disclosure Scheme, 2026.
|
|
|
|
|
|
Press release no. 2300883 dated 18.08.2026
|
Top Tax Officials Deliberate on Key Issues Concerning the Income Tax Department at Conclave
|
The two-day conclave of Principal Chief Commissioners of Income Tax and Principal Directors General of Income Tax, organized by the Income Tax Department, concluded today, August 18, in Jaipur. The conclave was chaired by Shri Ravi Agrawal, Chairman, Central Board of Direct Taxes (CBDT).
|
The event was attended by Members of the CBDT—Shri Pankaj Kumar Mishra, Shri Sanjay Bahadur, Shri Prasenjit Singh, Ms. G. Aparna Rao, Ms. Pallavi Agrawal and Shri Sunil Kumar Singh—along with Principal Chief Commissioners, Principal Directors General, Commissioners of Income Tax (Administration) and other senior officers from across the country.
|
The conclave witnessed extensive deliberations on key issues concerning the Income Tax Department, including e-HRMS, service matters, litigation, reservation policy, taxpayer services, future projects, the Systems Directorate, capacity building, infrastructure, expenditure budget, TDS administration and inter-agency coordination. Senior officers also shared their views and suggestions on the challenges and future priorities of the Department. A documentary produced by the Media Cell of the CBDT was also screened during the programme.
|
Shri Ravi Agrawal, Chairman, CBDT, held open and interactive discussions with senior officers on the future direction and functioning of the Department and emphasized the need for an actionable roadmap based on the suggestions received. Detailed discussions were also held on infrastructure requirements and essential facilities for Income Tax offices across the country.
|
The programme was organized under the guidance of Shri Ravi Agrawal, Chairman, CBDT, and under the leadership of Shri Sumeet Kumar, Principal Chief Commissioner of Income Tax, Rajasthan. Shri Anil Kumar Bhardwaj, Commissioner of Income Tax (Administration & TPS), Jaipur; Shri Gautam Singh Chaudhary, Additional Commissioner of Income Tax (Administration); Shri Surendra Yadav, Deputy Commissioner of Income Tax (Headquarters); and other officers and staff made significant contributions towards the successful conduct of the conclave.
|
At the conclusion of the programme, Ms. G. Aparna Rao, Member (TPS&R), CBDT, delivered the valedictory address. Shri Anil Kumar Bhardwaj, Commissioner of Income Tax (Administration & TPS), Jaipur, thereafter extended a vote of thanks to the Chairman, CBDT, Members of the Board, senior officers and all officers and staff associated with the successful organization of the conclave.
|
The conclave concluded on a positive and forward-looking note, with a shared commitment to translating the deliberations and suggestions into concrete action towards strengthening the Department and enhancing taxpayer services.
|
|
|
|
|
|
|
|
The Parliament received the assent of the President on the 16th August, 2024 and the Finance Bill is now 'The Finance (No. 2) Act, hereby published for general information.
|
|
|
|
|
|
|
|
Yes, the Honorable High Court of Madras in the case of Monika Alloys India Private Limited vs State Tax Officer (W.P. No.16563, 18170 & 18171 of 2024) set aside the impugned order and remanded back the matter for reconsideration. The Honorable Court noted that the petitioner was served a show cause notice dated 19.09.2023, alleging wrongful availment of Input Tax Credit. The petitioner replied to this notice on 10.10.2023 by uploading it on the portal along with an attachment explaining that the transitional VAT credit was claimed by filing Form TRAN-1. However, the impugned order recorded that the petitioner did not file any objections to the DRC-01 notice or provide any documentary evidence, which contradicted the documents on record. Therefore, the Honorable Court set aside the impugned order and remanded the matter for reconsideration. The respondent was directed to provide a reasonable opportunity to the petitioner, including a personal hearing, and issue and fresh order within three months from the date of receipt of a copy of this order.
|
Important to mention here that the Trans credit is neither the input tax as per Section 2(62) of the CGST Act, 2017 nor the output tax as per Section 2(82) of the CGST Act, 2017. Therefore, the transition credit claimed and utilized, even if found to be ineligible cannot be demanded under section 73 or 74 of the CGST Act as there is no jurisdiction with the proper officer under these provisions of the law. There transaction credit once claimed cannot be distributed in the law.
|
|
|
|
|
|
Author: Adv Minakshi Jain
|
Index:
- Amendments to the Central Goods and Services Tax Act, 2017 (CGST Act):
- Amendments to the Integrated Goods and Services Tax Act, 2017 (IGST Act):
- Amendments to the Union Territory Goods and Services Tax Act, 2017 (UTGST Act):
- Amendments to the Goods and Services Tax (Compensation to States) Act, 2017:
Amendments to the Central Goods and Services Tax Act, 2017 (CGST Act):
- Section 9 Amendment: Sub-section (1) of Section 9 is amended to include the words "and un-denatured extra neutral alcohol or rectified spirit used for manufacture of alcoholic liquor, for human consumption "after" alcoholic liquor for human consumption."
- Section 10 Amendment: Sub-section (5) of Section 10 is amended to add the reference to "section 74A" after "section 73 or section 74."
- Insertion of Section 11A :A new Section 11A is inserted, allowing the Government, upon being satisfied that a prevalent practice regarding the levy or non-levy of central tax on any supply of goods or services was or is in place, to issue a notification directing that the central tax payable on such supplies, or the excess central tax collected, shall not be required to be paid.
- Section 13 Amendment: Sub-section (3) of Section 13 is amended:
- Clause (b) is modified to clarify that the supplier needs to issue the invoice only in cases where it is required.
- A new clause (c) is inserted, providing that the date of issue of the invoice by the recipient shall be considered where the recipient is required to issue the invoice.
- The first proviso is amended to include a reference to the newly inserted clause(c).
- Section 16 Amendment:
- A new sub-section (5) is inserted, allowing registered persons to take input tax credit (ITC) for invoices or debit notes pertaining to Financial Years 2017-18 to 2020-21in any return filed by November 30, 2021.
- A new sub-section (6) is inserted, specifying that if a registration is cancelled and later revoked, the person shall be entitled to ITC for relevant invoices or debit notes in a return filed within specific timelines after the revocation order.
- Section 17 Amendment: Sub-section (5), clause (i) is amended to restrict the applicability of Section 74 for the period up to the Financial Year 2023-24, excluding references to Sections 129 and 130.
- Section 21: Amendment to include reference to the newly introduced Section 74A, in addition to Sections 73 and 74.
- Section 30: Introduces a new proviso in subsection (2) which states that revocation of cancellation of registration shall be subject to conditions and restrictions as may be prescribed.
- Section 31:
- Amendment to sub section (3)(f) to mandate that the period within which the tax must be paid shall be prescribed.
- Insertion of an explanation under clause (g) to clarify that a "supplier who is not registered" includes those registered solely for tax deduction under Section 51.
- Section 35: Amendment to include reference to Section 74A along with Sections 73 and 74 in sub section (6).
- Section 39: Substitution of subsection (3) to require registered persons who deduct tax at source under Section 51 to file monthly returns in a prescribed form and manner, regardless of whether any deductions have been made during that month.
- Section 49: Amendment to include reference to Section 74A in subsection (8)(c).
- Section 50: Amendment to include reference to Section 74A in the proviso of subsection (1).
- Section 51: Amendment to include reference to Section 74A in subsection (7).
- Section 54: Removal of the second proviso in subsection (3).
- Insertion of a new subsection (15) disallowing refunds of unutilized input tax credit or integrated tax paid on zero-rated supplies of goods if those goods are subject to export duty.
- Section 61: Amendment to include reference to Section 74A in subsection (3).
- Section 62: Amendment to include reference to Section 74A in subsection (1).
- Section 63: Amendment to include reference to Section 74A.
- Section 64: Amendment to include reference to Section 74A in subsection (2).
- Section 65: Amendment to include reference to Section 74A in subsection (7).
- Section 66: Amendment to include reference to Section 74A in subsection (6).
- Section 70: Insertion of a new subsection (1A) mandating that all persons summoned must attend as directed and truthfully provide statements or documents during examination.
- Section 73: Amendment to marginal heading to specify that the determination of tax applies to periods up to FY 2023-24.
- Insertion of a new subsection (12) to confirm that the provisions of this section apply only to tax determination up to FY 2023-24.
- Section 74: Amendment to marginal heading to specify that the determination of tax applies to periods up to FY 2023-24.
- Insertion of a new subsection (12) to confirm that the provisions of this section apply only to tax determination up to FY 2023-24.
- Omission of Explanation 2.
- Insertion of Section 74A: Introduces provisions for tax determination, refunds, and penalties for the period starting from FY 2024-25 onwards.
- Specifies the process and timelines for issuing notices, determining tax, and the applicable penalties.
- Provides different penalty structures depending on whether the non-payment or short payment of tax was due to fraud or other reasons.
- Clarifies the process for concluding proceedings and defines the term "suppression" in the context of this section.
- Section 75: Sub-section (1): The applicability of Section 75(1) is extended to include references to sub-sections (2) and (7) of Section 74A.
- Insertion of Sub-section (2A): A new provision is added where, if an Appellate Authority, Appellate Tribunal, or court finds that the penalty under Section 74A(5)(ii) is not sustainable due to the absence of fraud, willful misstatement, or suppression of facts, the person shall be liable to pay a penalty under Section 74A(5)(i).
- Sub-section (10): Substituted to clarify that adjudication proceedings shall be deemed concluded if the order is not issued within the prescribed time limits in Section 73(10), Section 74(10), or Section 74A(7).
- Sub-sections (11), (12), and (13): Expanded to include references to Section 74A in addition to Sections 73 and 74.
- Section 104: The Explanation in sub-section (1) is amended to include references to sub- sections (2) and (7) of Section 74A.
- Section 107:
- Sub-section (6)(b): The term "twenty-five" is replaced with "twenty."
- Sub-section (11): References to Section 74A are added in the second proviso.
- Section 109:
- Sub-section (1): Expanded to allow the Principal Bench to conduct examinations or adjudicate cases referred to in Section 171(2), if notified.
- Sub-section (5): Added provisos that specify certain cases to be adjudicated only by the Principal Bench.
- Sub-section (6): Amended to make the President’s powers subject to the provisions of sub-section (5).
- Section 112:
- Sub-sections (1) and (3): Amendments effective from August 1, 2024, allowing the filing of appeals or applications withinthe prescribed period or withinthree months after the date notified by the Government, whichever is later.
- Sub-section (6): Added provisions allowing applications to be filed within three months after the expiry of the period specified in sub-section (3).
- Sub-section (8)(b): The terms "twenty percent" and "fifty crore rupees" are replaced with "ten per cent" and "twenty crore rupees," respectively.
- Section 122: Sub-section (1B): The term "Any electronic commerce operator who" is substituted with "Any electronic commerce operator, who is liable to collect tax at source under section 52."
- Section 127: The section is amended to include references to Section 74A in addition to Sections 73 and 74.
- Insertion of Section 128A: A new section providing for the waiver of interest and penalty under specific conditions where a person pays the full amount of tax for periods from July 1, 2017, to March 31, 2020, as specified in Section 128A(1). Conditions for the conclusion of proceedings, as well as exceptions, are also detailed.
- Section 140: Sub-section (7): Amended retrospectively from July 1, 2017, to include invoices received prior to, on, or after the appointed day.
- Section 171: Sub-section (2): Adds a proviso allowing the Government to specify a date from which the Authority shall not accept requests for examination regarding the reduction of tax rates or input tax credits. The section also clarifies the definition of "Authority" to include the "Appellate Tribunal."
- Schedule III: New paragraphs are added, specifically addressing the treatment of co- insurance premiums and reinsurance commissions in GST, clarifying the responsibilities of the lead insurer and reinsurer regarding tax payments.
- Section 150: Provides that no refund will be made for taxes paid or input tax credits reversed under circumstances where such payments or reversals would not have been required if Section 118 had been in force at all relevant times.
Amendments to the Integrated Goods and Services Tax Act, 2017 (IGST Act):
- Section 5(1): A new clause is hereby inserted, bringing within the ambit of goods subject to integrated tax, "un-denatured extra neutral alcohol or rectified spirit used for the manufacture of alcoholic liquor for human consumption.
- New Section 6A: A mechanism is introduced whereby the Government may, upon being satisfied that a general practice of non-levy or short-levy of integrated tax was prevalent, exempt the payment of integrated tax (or excess tax) on certain supplies.
- Section 16(4): This section is clarified to ensure that claims for refunds of integrated tax paid on zero-rated supplies are to be governed in accordance with the provisions of the Central Goods and Services Tax Act, 2017.
- Section 16(5): It is stipulated that no refund of unutilized input tax credit shall be permitted on zero-rated supplies of goods if such goods are subject to export duty.
- Section 20 (Proviso): A proviso is added to cap the maximum amount payable for each appeal to the Appellate Authority or Tribunal at ₹40 crore.
Amendments to the Union Territory Goods and Services Tax Act, 2017 (UTGST Act):
- Section 7(1): A clause similar to that inserted in the IGST Act, includes "un-denatured extra neutral alcohol or rectified spirit used for the manufacture of alcoholic liquor for human consumption" under the goods subject to Union Territory tax.
- New Section 8A: A provision analogous to Section 6A of the IGST Act is introduced, allowing the Government to waive the Union Territory tax (or excess tax) if it is satisfied that a general practice of non-levy or short levy of tax was prevalent.
Amendments to the Goods and Services Tax (Compensation to States) Act, 2017:
- New Section 8A: This new section authorizes the Government to waive the cess (or excess cess) payable on certain supplies, provided it is satisfied that a general practice of non-levy or short levy of cess was prevalent.
|
|
|
|
|
4. Lawgics by Ms.Nidhi Aggarwal
|
Ms. Nidhi Aggarwal is delighted to present judgment with a great vision to spread complex GST law in a simple manner amongst the taxpayers, tax professionals, students and knowledge seeker.
|
|
Recently added notes are listed below:
|
|
|
|
|
|
Synopsis: The Delhi High Court dismissed the writ petition involving fraudulent ITC claims, directing the petitioner to pursue appellate remedy u/s 107 of the CGST Act.
|
Caste name: Banson Enterprises & Anr. vs Assistant Commissioner CGST & Ors.
|
Citation: W.P. (C) 6503/2025 dated 15.05.2025
|
Authority: Delhi High Court
|
The petition challenges the Order-in-Original dated 02.02.2025 based on a Show Cause Notice (SCN) dated 03.08.2024 A search was conducted, and statements were recorded including that of one Director admitting to the issuance of fake invoices during the Central Excise period. It was alleged that the Petitioner issued goods-less invoices to enable fraudulent Input Tax Credit (ITC) claims amounting to Rs. 1.85 crore.
|
Contentions of the Petitioner:
|
SCN was issued by unauthorized officer, thus, violates Rule 142(1)(a) of CGST Rules. No pre-consultation as required under Rule 142(1A) of CGST Rules was issued. Consolidated SCN for multiple financial years was issued and challenge to such consolidated action is pending in a separate matter (Quest Infotech case).
|
Contentions of the Department:
The impugned order is appealable, hence writ is not maintainable. The Petitioner’s Director admitted to allegations. Natural justice was followed as the Petitioner received the SCN, filed a reply, and availed of personal hearing. Reliance must be made on SC judgments and Allahabad HC rulings emphasizing alternate remedy u/s 107 CGST Act.
|
Findings and Decision of the Court:
The Court refused to interfere under writ jurisdiction, citing:
|
- No breach of fundamental rights or principles of natural justice.
- Availability of a statutory remedy (appeal) under Section 107 CGST Act.
The Court noted that the Allegations involve serious misuse of ITC, requiring fact-based adjudication, not suited for writ jurisdiction. Thus, the Petitioner was granted liberty to file appeal, and if filed with pre deposit, the appeal shall not be dismissed on limitation.
|
|
|
|
|
|
|
|
Synopsis: GST RC cancellation is not justified as petitioner was not given fair opportunity to respond.
|
Case Name: M/s. Genius Orthos Industries VS Union of India & Ors.
|
Citation: WRIT TAX No. 542 of 2023 dated 24.04.2025
|
Authority: Allahabad High Court
|
The petitioner was engaged in the business of surgical goods and its GST registration was cancelled on 19.12.2022 after a physical verification of its premises allegedly found no inputs, finished goods, or workers. A show cause notice was issued prior to cancellation, but the petitioner claimed they were not informed of the specific material findings leading to the cancellation. The appeal against the cancellation was also dismissed.
|
Contentions of the Petitioner:
|
The principles of natural justice were violated, as no proper notice of the specific material against them was given. Cancellation was based on vague grounds, and the watchman at the premises had confirmed that business activities were conducted, albeit irregularly. Rule 25 of the CGST Rules and Form GST REG 30 was not referenced in actual SCN.
|
Contentions of the Department:
|
The petitioner had due knowledge of the discrepancies found during physical verification and failed to provide a satisfactory explanation. Claimed that the cancellation order was justified due to absence of business activity at the registered premises.
|
Findings and Decision of the Court:
|
The High Court found that the cancellation was done without due process, especially considering that:
|
- The material used for cancellation was never properly shared with the petitioner.
- The statement of the watchman indicating occasional business activity was ignored.
- The physical verification report (GST REG-30) was not referenced in the show cause notice.
Thus, impugned cancellation and appellate orders were quashed and the matter was remanded to the proper authority for fresh adjudication within three months, ensuring that a reasoned and speaking order is passed after an Opportunity of hearing is granted. The petitioner may submit relevant evidence.
|
|
|
|
|
|
|
|
Synopsis: Rejection of appeal on ground that appeal was not filed electronically under Rule 108 of CGST Rules, 2017 is invalid in case of non availability of order–in–original on GST portal and Appeal being filed manually.
|
Case Name: M/s Appolo Sesame Industries & Anr. VS Assistant Commissioner of CGST, Division X, Nadiad & Ors
|
Citation: R/Special Civil Application No. 571 of 2025 dated 24.04.2025
|
Authority: Gujarat High Court
|
The petitioners challenged the rejection of their appeal against an Order-in-Original dated 30.10.2023. They had filed the appeal manually in Form GST APL-01, as the order was not available on the GST portal, making electronic filing impossible. Despite this, the Appellate Authority rejected the appeal on 27.09.2024, stating it was not filed electronically, as required under Rule 108(1) of the CGST Rules, 2017.
|
Contentions of the Petitioner:
|
The order-in-original was not available on the portal, so manual filing was the only viable option. A pre-deposit of 10% of the disputed dues was paid. The Appellate Authority ignored the proviso to Rule 108(1), which allows manual filing if the order is unavailable electronically. The Appellate Authority failed to issue the mandatory provisional acknowledgment, despite receiving the appeal.
|
Contentions of the Department:
|
The appeal was filed offline without fulfilling electronic filing requirements. The Appellate Authority argued that procedural rules were not followed, hence the rejection was valid.
|
Findings and Decision of the Court:
|
The High Court found that the Appellate Authority failed to apply its mind to the facts. It held that the rejection of the appeal violated Rule 108(1) of the CGST Rules, as manual filing is permitted when the order is not available on the portal. The impugned rejection order was set aside and the matter was remanded to the Appellate Authority to hear and decide the appeal on merits.
|
|
|
|
|
|
5. GST Notes by CMA Anil Sharma
|
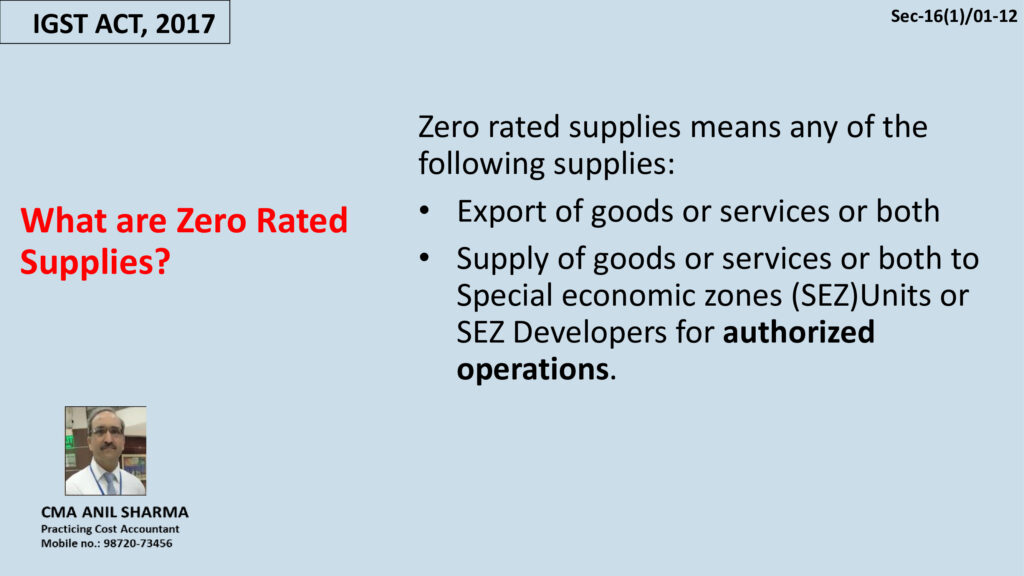
1) Chapter-7 of IGST Act containing 12 slides is added in the Notes section'. It covers POS for inter state transactions including export.
|
Authored by CMA Anil Sharma Sir, with a vision to simply the complex GST Law for taxpayer, professional, taxmen etc.
|
|
|
|
|
|
|
|
|
6. GST Daily by CA Pradeep Modi
CA Pradeep Modi is presenting judgment analysis under title 'GST Daily - Stay yourself updated'
|
|
|
|
|
|
|
Recap of Latest updates posted on 27.08.2026
|
CBIC issued Notification No. 30/2026-Customs dated 21.08.2026 regarding Seeks to exempt 10 lakh MT of raw sugar falling under tariff heading 1701 from the whole of the customs duty leviable thereon under …
|
GSTN is taking downtime to enhance its services on the GST Portal on 26.08.2026 from 12:00 AM onwards until 6:30 am of 26.08.2026.
|
The Hon’ble Supreme Court in M/s G.R. Infra Projects Limited set aside the Show Cause Notice dated June 13, 2025 issued under Section 74 of the CGST Act read with the MPGST Act for the FY 2018-19, and held that a bland and mechanical recital of the words ‘fraud or concealment of facts’,
|
Indian Railway Finance Corporation Ltd received a show cause notice from the GST Authority demanding ₹549.32 crore. The notice, issued under Section 73 of the Central Goods and Services Tax Act, 2017, cites excess input tax credit claims for FY23.
|
The Anti-Corruption Bureau (ACB) on Monday arrested a state tax officer and a senior assistant in Nirmal district for demanding and accepting a bribe of ₹50,000 in connection with a GST audit.
|
CBIC issued Notification No. 71/2026-Customs (N.T.) dated 25.08.2026 regarding Fixation of Tariff Value of Edible Oils, Brass Scrap, Areca Nut, Gold and Silver
|
CBIC issued Notification no. 21/2026-Customs (ADD) dated 21.08.2026 that Seeks to continue applicability of anti-dumping duty on imports of Natural Mica based Pearl Industrial Pigments ..
|
CBDT issued notification no. 115/2026 dated 21.08.2026 to hereby approves deduction under section 45(3)(a)(i) of the Income tax Act, 2025 to the International Institute of Bio Technology and Toxicology , Tamil Nadu for Scientific Research
|
I request the views of tax professionals and TDS experts on the following issue under the Income-tax Act, 2025, regarding reporting in Form 140.
|
|
|
|
|
|
|
|
THE HON'BLE ALLAHABAD HIGH COURT IN THE CASE OF Vibhuti Tyres V/s State of U.P., decided on 7-5-2025
|
✔️ Is it justified that GST order with higher demand than show-cause notice?
|
👉 The Hon'ble High Court Judgement:-
|
✔️ Where in show-cause notice amount representing tax, interest and penalty was indicated as Rs. 8,81,080, but in order, much higher demand was raised at Rs. 32,97,336, same was in violation of section 75(7); matter was to be remanded back.
|
Section 75 of Central Goods and Services Tax Act, 2017
|
|
|
|
|
|
|
|
THE HON'BLE JHARKHAND HIGH COURT IN THE CASE OF Sadanand Prasad Barnwal V/s State of Jharkhand, decided on 8-5-2025
|
✔️ Is it valid if SCN and order under section 73 for lack of digital signature of issuing authority?
|
👉 The Hon'ble High Court Judgement:-
|
✔️ Where both summary of SCN in Form GST DRC-01 and order under section 73 did not bear digital signature of concerned authority, both SCN and order were to be quashed.
|
Section 161, read with section 73 of Central Goods and Services Tax Act, 2017
|
|
|
|
|
|
|
|
THE HON'BLE CALCUTTA HIGH COURT IN THE CASE OF Edelweiss Rural & corporate Services Ltd. V/s Deputy Commissioner of Revenue, decided on 5-5-2025
|
✔️ What would be Refund if business stood closed and registration was cancelled?
|
👉 The Hon'ble High Court Judgement:-
|
✔️ Where Refund sanction order had itself observed that assessees business was closed down, its registration was cancelled and it had no tax dues refund claim was already allowed, direction to credit refund amount to credit ledger instead of bank account of assessee was self-contradictory since there was no business for assessee to take benefit of refund credited to assessees credit ledger.
|
Section 54 of Central Goods and Services Tax Act, 2017
|
|
|
|
|
|
|
|
THE HON'BLE JHARKHAND HIGH COURT IN THE CASE OF Sri Ram Stone Works V/s State of Jharkhand, decided on 9-5-2025
|
✔️ Can GST Notice would be issued under Section 61 of CGST Act merely on the basis of difference between sale price and market price?
|
👉 TheHon'ble High Court Judgement:- ✔️ Clear objective of section 61 is to enable an Assessing Officer to point out discrepancies and errors which are occurring in return filed by a registered person with that of related particulars; notice under section 61 cannot be issued comparing particulars at which assessee has sold its goods with that of prevalent market price.
|
|
|
|
|
|
7. PPT/Handbook on GST
|
|
|
|
8. GST/Income Tax in Media
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Hope the above updates is of use to you. Please share your input and feedback at taxupdate.otu@gmail.com
|
|
|
|
|
|
|
|
 
|
Visit our website
|
OTU provides you
|
- Articles on various topics
|
|
- Media - GST, Income Tax & Press R.
|
|
|
|
|
