|
onlinetaxupdate team wish to express sincere thanks to all the readers, authors, subscribers for the support extended to us. Please share your feedback at
|
taxupdate.otu@gmail.com or 7738647904
|
Newsletter 139 dated 14.10.2024
|
|
|
|
|
|
|
|
|
Dear Reader,
|
Please find newsletter for your reading and reference.
|
|
Index of the Newsletter
- Recent updates
- Portal updates
- Article
- Lawgics by Ms.Nidhi Aggarwal
- GST Notes by CMA Anil Sharma
- GST Daily by CA Pradeep Modi
- PPT/Handbook
- GST/IT/Customs in media
|
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Notification no. 02/2026 – Central Tax dated 07.05.2026.
|
GOVERNMENT OF INDIA
MINISTRY OF FINANCE
DEPARTMENT OF REVENUE
|
Notification No. 02/2026 – Central Tax dated 07.05.2026
|
S.O. 2286(E).— In exercise of the powers conferred by sub-section (1A) of section 101A of the Central Goods and Services Tax Act, 2017 (12 of 2017) (hereinafter referred to as the said Act), the Central Government, on the recommendations of the Council, hereby empowers the Principal Bench of the Appellate Tribunal, New Delhi constituted under sub-section (3) of section 109 of the said Act, to hear appeals made under section 101B of the said Act.
|
This notification shall be deemed to have come into force on the 1st day of April, 2026.
|
BALASUBRAMANIAN KRISHNAMURTHY,
Joint Secretary
|
|
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Notification no. 01/2026 – Central Tax dated 21.04.2026 that Seeks to extends the due date for furnishing the return in FORM GSTR-3B for the month of March, 2026 till the twenty-first day of April, 2026.
|
GOVERNMENT OF INDIA
MINISTRY OF FINANCE
DEPARTMENT OF REVENUE
CENTRAL BOARD OF INDIRECT TAXES AND CUSTOMS
Notification No. 01 /2026 Central Tax dated 21.04.2026
|
G.S.R (E)… ( In exercise of the powers conferred by sub section (6) of section 39 of the Central Goods and Services Tax Act, 2017 (12 of 2017), the Commissioner, on the recommendations of the GST Council, hereby extends the due date for furnishing the return in FORM GSTR 3B for the month of March, 2026 till the twenty first day of April, 2026, for the registered persons who are required to furnish return under sub section (1) of section 39 read with clause (i) of sub rule (1) of rule 61 of the Central Goods and Services Tax Rules, 2017.
|
2. This notification shall come into effect from 20th day of April, 2026.
|
(Kangale Shrunkhala Motiram)
Director
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Notification no. 01/2026-Central Tax (Rate) dated 30.04.2026 that Seeks to amend Notification No 9/2025 - Central tax (Rate) to align them with changes made vide Finance Act, 2026
|
|
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Notification no. 18/2025-Central Tax (Rate) dated 31.12.2025 Seeking to amend Notification 09/2025- Central Tax (Rate), to prescribe GST rates on tobacco products.
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Circular no. 256/02/2026-GST dated 25.07.2026 to provide Clarification regarding filing of appeal by department before the Goods and Services Appellate Tribunal (GSTAT) against order of appellate authority (where Orders-in-Original have been passed by a Common Adjudicating Authority in DGGI cases)
|
Government of India
Ministry of Finance
Department of Revenue
Central Board of Indirect Taxes and Customs
GST Policy Wing
F. No. CBIC-20010/12/2026-GST
|
Circular No. 256/02/2026-GST dated 25.07.2026
|
The Principal Chief Commissioners/ Chief Commissioners (All)
|
The Principal Directors General/ Directors General (All)
|
Subject: Clarification regarding filing of appeal by department before the Goods and Services Appellate Tribunal against order of appellate authority (where Orders-in-Original have been passed by a Common Adjudicating Authority in DGGI cases) – reg.
|
Kind attention is drawn to notification No. 02/2022-Central Tax dated 11th March, 2022 wherein para 3A and Table V were inserted in notification No. 02/2017-Central Tax dated 19th June, 2017 (and further amended by notification No. 27/2024- Central Tax, dated 25th November, 2024), to empower Additional/ Joint Commissioners of Central Tax of specified Central Tax Commissionerates (hereinafter referred to as “Common Adjudicating Authority” or “CAA”), with all India Jurisdiction for the purpose of adjudication of the show cause notices issued by the officers of the Directorate General of Goods and Services Tax Intelligence (herein after referred as “DGGI”).
|
2. Attention is further drawn to circular No. 169/01/2022-GST dated 12th March 2022 and circular No. 239/33/2024-GST dated 4th December 2024 wherein guidelines were issued with respect to assignment of show cause notices for adjudication and passing of order by a CAA, in respect of cases investigated by the officers of the DGGI.
|
3. Further, vide circular No. 250/07/2025-GST dated 24th June 2025, guidelines were issues with respect to reviewing and revisional authority and appeal by department before the appellate authority against orders passed by a CAA.
|
4. References have been received from field formations seeking clarification regarding filing of appeal by the department before the Goods and Services Tax Appellate Tribunal (hereinafter referred to as ‘GSTAT’), against an order of appellate authority (where Order-in-Original has been passed by a Common Adjudicating Authority in respect of DGGI cases). Clarifications are being sought as to:
|
(a) who will be the reviewing authority in respect of such orders of appellate authority in CAA cases?;
|
(b) which jurisdictional authority will be required to file an appeal before the GSTAT in such CAA cases?; and
|
(c) whether appeal before the GSTAT, in such CAA cases, is required to be filed before the bench of GSTAT having territorial jurisdiction over the location of the taxable person/ noticee or is to be filed before the bench of GSTAT having jurisdiction over Commissionerate of the CAA.
|
5. The GSTAT has been constituted under section 109 of the CGST Act, 2017. The territorial jurisdiction of the benches of the GSTAT has been notified through, the notification S.O. 3048(E) [F. NO. A-50050/150/2008-CESTAT-DOR dated the 31st July, 2024 (as amended from time to time), issued by the Central Government under the said section on the recommendations of the GST Council. Appeals to the GSTAT are governed by the provisions of section 112 of the CGST Act, 2017.
|
6. The matter has been examined in consultation with the Union Ministry of Law and Justice. In order to ensure uniformity in the procedure of filing of departmental appeals before the GSTAT in such cases (where Orders-in-Original have been passed by a CAA in DGGI cases), the Central Board of Indirect Taxes and Customs, hereby issues the following clarifications in respect of procedure to be followed for the purposes of review of orders passed by the appellate authority in such CAA cases and for filing of appeal by department against such order of appellate authorities:
|
(a). Communication of order by the appellate authority: The appellate authority, upon passing of an order-in-appeal, under section 107 of the CGST Act, in respect of an appeal arising from an order-in-original passed by the Common Adjudicating Authority, shall upload the order-in-appeal on the common portal, and shall also send a copy of the said order to the Pr. Commissioner/ Commissioner of CGST Commissionerate having jurisdiction over Common Adjudication Authority, through email, along with a with a physical copy.
|
(b). The Pr. Commissioner/ Commissioner of CGST Commissionerate having jurisdiction over the Common Adjudication Authority, shall examine the said order-in-appeal passed by the appellate authority in such cases, after seeking comments and inputs from DGGI (if required) at the earliest, and he shall, forward such comments to the jurisdictional CGST Pr. Commissioner/ Commissioners of all the taxable persons/ noticees involved in the said order-in-original, with his recommendations.
|
(c). Reviewing authority: The jurisdictional CGST Pr. Commissioner/ Commissioner of a particular taxable person/ noticee shall be the reviewing authority under sub-section (3) of section 112 of CGST Act, 2017 in respect of the order passed by the appellate authority in such CAA cases, in respect of the said taxable person/ notice under his jurisdiction. The said reviewing authority (including the Pr. Commissioner/ Commissioner having jurisdiction over the Common Adjudication Authority) shall, examine the matter regarding the legality and propriety of the order of appellate authority in such CAA cases after taking into consideration, inter alia, the comments and recommendations referred to in para (b) above in accordance with provisions of sub-section (3) of section 112 of CGST Act, 2017. Where the reviewing authority is of the opinion that an appeal is required to be filed by the department against order of the appellate authority in such CAA cases, he may for the purpose of satisfying himself as to the legality or propriety of the said order and for determination of such points arising out of the said order, as may be specified him, may, by order, appoint and direct any officer subordinate to him for filing and pursuing the appeal by the department before the GSTAT.
|
(d). Separate appeals have to be filed in respect of each of the taxable person/ noticee, against the order of appellate authority in such CAA cases, by the jurisdictional CGST Commissionerate of the taxable person/ noticee, before the concerned Bench of the GSTAT having territorial jurisdiction over such taxable person/ noticee.
|
(e). After such application to the GSTAT has been made, the jurisdictional CGST Pr. Commissioner/ Commissioner shall also intimate the Pr. Commissioner/ Commissioner of CGST Commissionerate having jurisdiction over the Common Adjudication Authority, along with a copy of the appeal filed in this respect. Where the reviewing authority is of the opinion that no appeal by the department is required to be filed against the order of the appellate authority in CAA cases, he shall intimate the same to Pr. Commissioner/ Commissioner of CGST Commissionerate having jurisdiction over the Common Adjudication Authority.
|
7. Difficulty, if any, in implementation of the above instructions may please be brought to the notice of the Board.
|
(Gaurav Singh)
Commissioner (GST)
|
|
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Circular no. 255/01/2026-GST dated 25.06.2026 to provide Clarification regarding jurisdiction in cases involving migration/ transfer of taxable persons from one jurisdiction to another jurisdiction.
|
|
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Circular no. 254/11/2025-GST dated 27.10.2025 regarding Assigning proper officer under section 74A, section 75(2) and section 122 of the Central Goods and Services Tax Act, 2017
|
|
|
|
|
|
CBIC issued Notification No. 75 /2026-Customs (N.T.) dated 15.09.2026 regarding Fixation of Tariff Value of Edible Oils, Brass Scrap, Areca Nut, Gold and Silver
|
|
|
|
|
|
Central Board of Indirect Taxes & Customs issued CAVR Review Order No. 2/2025-Customs dated 26.11.2025 for extension of validity of CAVR Order No. 02/2023-Customs under the Custom (Assistance in Value Declaration of Identified imported Goods) Rules. 2023 in respect of Stainless Steel of J3 grade classified under HS Codes 72191200. 72191300. 72191400, 72192390. 72193290. 72193390. 72193490. 72193590. 72199012. 72199013. 72199090. 72202029. 72202090, 72209022,72209029 & 72209090
|
ln exercise of the powers conferred by clause (iv) of the second proviso to sub-section (1) ol section 14 of the Customs Act, 1962 (52 of 1 962), read with sub rule (2) of rule 10 and rule 5 of the Customs (Assistance in Value Declaration of Identified Imported Goods) Rules,2023, the Central Board of Indirect Taxes & Customs hereby extends the validity of CAVR Order No. 02/2023-Customs dated 15th November, 2023, issued in respect of Stainless Steel of J3 grade falling under HS Codes 72191200, 72191300, 72191400, 72192390, 72193290, 72193390, 72193490, 72193590, 72199012, 72199013, 72199090, 72202029, 72202090,72209022,72209029 & 72209090, for a period of one year with effect from 29th November, 2025. This order shall remain in force till 28th November, 2026
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Trade Notice 28/2026-27 dated 16.09.2026 regarding Revision in Timeline for Issuance of PSIC and One-time Relaxation for Issuance of Backlog PSICs
|
Kind attention is invited to earlier Trade Notice No. 22/2026-27 dated 25.08.2026 regarding enhancements in the Pre-Shipment Inspection Agency (PSIA)/Pre Shipment Inspection Certificate (PSIC) process.
|
2. In order to facilitate smooth implementation of the revised PSIA/PSIC module, the following relaxations are hereby made to the provisions contained in the aforesaid Trade Notice:
|
i. One-time transitional arrangement for issuance of PSICs
|
A one-time relaxation of seven days from the date of issuance of this trade notice is hereby provided to the recognized PSIAs for clearing the backlog PSICs pertaining to inspections conducted prior to 25.08.2026, where such certificates could not be issued due to system restrictions introduced pursuant to the aforesaid Trade Notice.
|
ii. Revision in timeline for issuance of PSIC
|
Para 2(ii) of Trade Notice No. 22/2026-27 dated 25.08.2026 shall stand substituted with the following:
|
"The PSIC shall be generated and issued within 2 days from the date of inspection. The system shall permit generation and issuance of the PSIC only within the prescribed timeline. The PSIC uploading shall be done from the same geographical location/country where inspection is carried out."
|
3. All other provisions of Trade Notice No. 22/2026-27 dated 25.08.2026 shall remain unchanged.
|
This issues with the approval of the DG, DGFT.
|
|
|
|
|
|
|
|
The Directorate of Revenue Intelligence (DRI) seized more than 362 metric tonnes of Pakistan-origin dry dates under 'Operation Deep Manifest' during an enforcement drive targeting illicit trade conduits.
|
Acting on specific actionable intelligence, operational teams intercepted 13 cargo containers carrying the consignments at CFS Ahmad in Nashik , which a Mumbai-based commercial entity imported.
|
According to the Ministry of Finance, the shipments arrived via Jebel Ali in the United Arab Emirates, accompanied by import clearance paperwork that falsely declared the UAE as the sovereign country of origin.
|
Official findings revealed that the commercial consignment moved through a deliberate routing network designed to mask its true origin. The cargo started its maritime transit from Karachi Port in Pakistan, reaching Jebel Ali Port in the UAE abroad an initial vessel.
|
"Preliminary investigation revealed a carefully orchestrated transshipment arrangement designed to conceal the Pakistan-origin of the goods," the Ministry stated.
|
The operational breakdown showed that the illicit cargo underwent minimal physical handling in the Gulf transit hub to obscure the paper trail.
|
"The dry dates were initially shipped from Karachi Port, Pakistan, to Jebel Ali Port, UAE, in one set of containers aboard one vessel," the official statement noted.
|
Handlers in the transit zone then re-routed the shipment onto another carrier line, it state.
|
"At Jebel Ali, the goods were merely transshipped and transferred to another set of containers and loaded onto a different vessel for onward shipment to India through entities operated by Pakistani nationals," the Ministry confirmed.
|
Border and port enforcement tightened following regulatory revisions enacted by the Directorate General of Foreign Trade (DGFT) in mid-2025.
|
The Ministry mentioned that following the Pahalgam terror attack, the Government of India, in the interest of national security, imposed a complete prohibition on the direct or indirect import or transit of all goods originating in or exported from Pakistan, with effect from 02.05.2025, vide DGFT notification no. 06/2025-26 dated 02.05.2025.
|
To counter non-compliant import tactics across container terminals, central enforcement authorities launched structured surveillance protocols targeting third-party trade jurisdications.
|
"In response, DRI, under 'Operation Deep Menifest", has been consistently identifying, intercepting and seizing Pakistan-origin goods attempted to be imported into India through third-country routing," the Ministry said.
|
Customs and intelligence officials continue to track intermediate entities connected to commercial paper falsification, fraudulent routing manifests, and proxy transshipment nodes.
|
"The seizure underscores (DRI's sustained resolve to identify, disrupt and dismantle sophisticated networks seeking to circumvent trader prohibitions through misdeclaration , transshipment and manipulation of documentation, thereby safeguard national security and straightening supply chain integrity," the Ministry added.
|
|
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Notification No. 36/2026-27 dated 15.09.2026 regarding De minimis exemption from Registration-cum-Membership Certificate (RCMC) requirements for low-value exports
|
|
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Public Notice 30/2026-27 dated 14.09.2026 regarding Extension of timeline for surrender of unutilised TRQ quantity allocated for import of 10 Lakh MT of Raw Sugar
|
|
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Trade Notice 27/2026-27 dated 14.09.2026 Inviting comments/suggestions on Amendment in Para 2.93 of the Handbook of Procedures, 2023 – Rules of Origin (Non-Preferential).
|
|
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Trade Notice 26/2026-27 dated 07.09.2026 regarding Comments/views on proposed suspension of 544 Standard Input Output Norms (SIONs) remaining unutilized during the last three financial years
|
|
|
|
|
|
Central Board of Direct Taxes issued Guidelines dated 13.06.2025 vide F. No. 225/37/2025/ITA-II, regarding compulsory selection of returns for Complete Scrutiny during the Financial Year 2025-26 - procedure for compulsory selection in such cases.
|
2. The parameters for compulsory selection of returns for Complete Scrutiny during Financial Year 2025-26 and procedure for compulsory selection in such cases are prescribed as under:
|
3. Clarification: It is clarified that where return has been furnished in response to notice u/s 142(1) of the Act and such notice u/s 142(1) of the Act was issued due to the information contained in NMS Cycle/AIS/Statement of Financial Transactions (SFT)/ CPC-TDS information / information received from Directorate of I&CI, such return will not be taken up for compulsory scrutiny. Selection of such cases for scrutiny will be done through the CASS cycle.
|
4. Issuance of notice u/s 143(2) in certain cases:
|
4.1 Jurisdictional Assessing Officers (JAOs) shall upload the underlying documents for access by NaFAC in the following cases which are to be completed by NaFAC on or before 31.03.2026 and Notice u/s 143(2)/142(1) of the Act calling for information shall be served on the assess through NaFAC in these caes:
|
(a) Cases (other than search & seizures/survey) in which notices u/s 148 of the Act have been issued where return is either furnished or not furnished in response to notice u/s 148 of the Act.
|
(b) Cases in which notices u/s 142(1) of the Act calling for return, have been issued & no returns have been furnished.
|
4.2 Cases, where notices u/s 148 of the Act have been issued pursuant to search & seizure/survey actions conducted on or after the 01.04.2021 but before 01.09.2024, if lying outside Central Charges,
|
(i) where return is furnished, the Jurisdictional Assessing Officer (JAO) concerned shall serve the Notice u/s 143(2) of the Act and Pr.CIT/Pr.DIT/CIT/DIT concerned shall ensure that such cases transfer these cases to central charges u/s 127 of the Act.
|
(ii) where return is not furnished, these cases shall be transferred to central charges for further necessary action.
|
4.3 During the course of Search & Seizure action, information relating to some other persons, who may have one-off/very few or limited financial transaction(s) with the main assessee group covered in the search u/s 132/ 132A of the Act, may be found. Such persons are not integrally connected with the core business of the main assessee searched and do not belong to the same business group. Often such persons are also not residing in the same city as that of the main assesssee. In such cases, the relevant information is generally passed on to the jurisdictional AO for assessing them u/s 148 (for searches conducted/requisition made after 01.04.2021) of the Income-tax Act, 1961. It is clarified that such non-search cases selected u/s 148 of the Act are not required to be transferred to the Central Charges unless covered by the Board's guidelines under F.No. 299/107/2013-IT (Inv.III)/1568 dated 25.04.2014.
|
5. For Assessing Officers in International Taxation and Central Circle charges:
|
5.1 The cases shall be selected for compulsory scrutiny by the International Taxation and Central Circle charges following the above prescribed parameter at Para 2 with prior administrative approval of Pr.CIT/Pr.DIT/CIT/DIT concerned and these selected cases for compulsory scrutiny shall continue to be handled by International Taxation and Central Circle charges respectively, as earlier.
|
5.2 It is further clarified that communication to NaFAC for access and/or further action after selection for Compulsory Scrutiny will not apply to the International taxation and Central charges.
|
6. Time limit: As per the proviso to section 143(2) of the Act, the time limit for service of notice u/s 143(2) of the Act for the ITRs filed in the Financial Year (FY) 2024-25 which are selected for Compulsory Scrutiny is 30.06.2025.
|
7. These instructions may be brought to the notice of all concerned for necessary compliance.
|
|
|
|
|
|
Press release no. 2300883 dated 18.08.2026
|
Top Tax Officials Deliberate on Key Issues Concerning the Income Tax Department at Conclave
|
The two-day conclave of Principal Chief Commissioners of Income Tax and Principal Directors General of Income Tax, organized by the Income Tax Department, concluded today, August 18, in Jaipur. The conclave was chaired by Shri Ravi Agrawal, Chairman, Central Board of Direct Taxes (CBDT).
|
The event was attended by Members of the CBDT—Shri Pankaj Kumar Mishra, Shri Sanjay Bahadur, Shri Prasenjit Singh, Ms. G. Aparna Rao, Ms. Pallavi Agrawal and Shri Sunil Kumar Singh—along with Principal Chief Commissioners, Principal Directors General, Commissioners of Income Tax (Administration) and other senior officers from across the country.
|
The conclave witnessed extensive deliberations on key issues concerning the Income Tax Department, including e-HRMS, service matters, litigation, reservation policy, taxpayer services, future projects, the Systems Directorate, capacity building, infrastructure, expenditure budget, TDS administration and inter-agency coordination. Senior officers also shared their views and suggestions on the challenges and future priorities of the Department. A documentary produced by the Media Cell of the CBDT was also screened during the programme.
|
Shri Ravi Agrawal, Chairman, CBDT, held open and interactive discussions with senior officers on the future direction and functioning of the Department and emphasized the need for an actionable roadmap based on the suggestions received. Detailed discussions were also held on infrastructure requirements and essential facilities for Income Tax offices across the country.
|
The programme was organized under the guidance of Shri Ravi Agrawal, Chairman, CBDT, and under the leadership of Shri Sumeet Kumar, Principal Chief Commissioner of Income Tax, Rajasthan. Shri Anil Kumar Bhardwaj, Commissioner of Income Tax (Administration & TPS), Jaipur; Shri Gautam Singh Chaudhary, Additional Commissioner of Income Tax (Administration); Shri Surendra Yadav, Deputy Commissioner of Income Tax (Headquarters); and other officers and staff made significant contributions towards the successful conduct of the conclave.
|
At the conclusion of the programme, Ms. G. Aparna Rao, Member (TPS&R), CBDT, delivered the valedictory address. Shri Anil Kumar Bhardwaj, Commissioner of Income Tax (Administration & TPS), Jaipur, thereafter extended a vote of thanks to the Chairman, CBDT, Members of the Board, senior officers and all officers and staff associated with the successful organization of the conclave.
|
The conclave concluded on a positive and forward-looking note, with a shared commitment to translating the deliberations and suggestions into concrete action towards strengthening the Department and enhancing taxpayer services.
|
|
|
|
|
|
|
|
GSTN Advisory no. 672 dated 19.09.2026
|
This is an advance information to the all users – Taxpayers and Tax Officers, of GST System who use Digital Certificate Signature on the GST Portal.
|
A new version of emSigner (v3.3) is being made available for download for the purpose of providing compatibility with tokens (USB dongles) that are issued on or after 21-September-2026.
|
A. Users with valid certificates: There is no change for the users having existing valid digital certificates and their existing token (USB Dongle) are working, as of 21-Sep-2026. If your existing DSC works normally, you may continue using your current emSigner version.
|
If you encounter signing failures or if your certificate does not appear for selection despite correctly installed token drivers, upgrade to the emSigner version 3.3 by following steps given under point-B below. The emSigner version 3.3 is backward compatible to support the existing tokens (USB dongles).
|
B. Users with newly issued tokens: The users who have been issued a new token (USB Dongle) on or after 21-Sep-2026, either due to issuance of new certificate and dongle, or renewal of certificate in a new dongle, shall have to upgrade to version 3.3 of emSigner by following below steps:
|
Step-1. Please ensure that your system – desktop / laptop / AIO which on which the DSC is used for the GST System, meets the following minimum system requirements:
|
1.1 Operating system and hardware
|
Step-2.Download & install the version 3.3 of emSigner from the GST Portal by navigating to https://www.gst.gov.in/help/docsigner - the older versions of emSigner will not work for such new DSC dongles issued from 21 September 2026 onwards.
|
C. Validity and future renewal: Under CCA’s advisory, DSCs downloaded onto FIPS 140-2 dongles on or before 21 September 2026 can continue to be used until the DSC expires. That date does not automatically invalidate existing DSCs. Subsequent renewal or fresh issuance generally requires a FIPS 140-3 dongle, subject to CCA’s specified exceptions. The CCA migration advisory may be referred for more details on this aspect by navigating to https://cca.gov.in/sites/files/pdf/news/Advisory_on_Migration_from_FIPS_140- 2_to_FIPS_140-3.pdf
|
Please create a ticket on the GST Helpdesk if you need any assistance while upgrading to the emSigner version 3.3 and our teams shall get in touch for resolution.
|
|
|
|
|
|
|
|
GSTN is taking downtime to enhance its services on the GST Portal on 18.09.2026 from 12:00 AM onwards until 2:00 am of 18.09.2026.
|
|
We shall be enhancing services on the GST portal on : 18th Sept’26 12:00 AM onwards. GST Portal services will not be available until 18th Sept’26 02:00 AM. The inconvenience caused is regretted.
|
|
|
|
|
|
|
|
|
CBDT has issued Notification No. 114/2026 dated 14.08.2026, notifying the rules and prescribed forms under the Foreign Assets of Small Taxpayers Disclosure Scheme, 2026.
|
|
|
|
|
|
|
|
The Income Tax e-Filing Portal has enabled a dedicated grievance facility for taxpayers to report complaints relating to corruption, misbehaviour, harassment and sexual harassment.
|
Under the grievance mechanism, complainants can select the relevant category and provide details including the name and designation of the officer concerned, along with a description of the grievance. The portal specifically provides categories for “Corruption” and “Mis-behaviour/harassment/sexual harassment.”
|
The facility is expected to strengthen transparency, accountability and taxpayer grievance redressal by providing an online mechanism for reporting serious complaints relating to official conduct.
|
|
|
|
|
|
|
|
Common offline utility for Form 3CA-3CD and 3CB-3CD
Form 3CA-3CD: Audit report under section 44AB of the Income -tax Act, 1961, in a case where the accounts of the business or profession of a person have been audited under any other law and Statement of Particulars required to be furnished under Section 44AB of the Income-tax Act, 1961
|
Form 3CB-3CD: Audit report under section 44AB of the Income -tax Act 1961, in the case of a person referred to in clause (b) of sub - rule (1) of rule 6G and Statement of Particulars required to be furnished under Section 44AB of the Income-tax Act, 1961
|
Edge browser installation is required before installing the utility.
|
|

|
Date of first release of Form Utility 10-Sep-2021
|
Date of Latest release of Form Utility 02-Apr-2026
|
|
|
|
Date of first release of Form Schema 26-Oct-2021
|
Date of latest release of Form Schema 01-Apr-2026
|
|

|
Form 10B (A.Y. 2023-24 Onwards)
Audit Report under clause (b) of the tenth proviso to section 10(23C) and section 12A(1)(b)(ii) of Income tax act,1961, in the case of a fund or trust or institution or any university or other educational institution or any hospital or other medical institution.
|
|
|
|
Date of first release of Form Utility 24-Aug-2023
|
Date of Latest release of Form Utility 01-Apr-2026
|
|
|
|
Date of first release of Form Schema 08-Sep-2023
|
Date of latest release of Form Schema 01-Apr-2026
|
|
|
|
Form 10B (Upto A.Y. 2022-23)
Audit report under section 12A(b) of the Income-tax Act, 1961, in the case of charitable or religious trusts or institutions
|
|
|
|
(Version PR3.1) (1.19 MB)
|
Date of first release of Form Utility 06-Sep-2022
|
Date of Latest release of Form Utility 04-Oct-2022
|
|
|
|
Date of first release of Form Schema 19-Aug-2022
|
Form 10BB (A.Y. 2023-24 Onwards)
Audit report under clause (b) of the tenth proviso to clause (23C) of section 10 and sub-clause (ii) of clause (b) of sub-section (1) of section 12A of the Income-tax Act, 1961, in the case of a fund or trust or institution or any university or other educational institution or any hospital or other medical institution which is required to be furnished under clause (b) of the tenth proviso to clause (23C) of section 10 or a trust or institution which is required to be furnished under sub-clause (ii) of clause (b) of section 12A
|
|
|
|
Date of first release of Form Utility 11-Oct-2023
|
Date of Latest release of Form Utility 01-Apr-2026
|
|
|
|
Date of first release of Form Schema 21-Sep-2023
|
Date of latest release of Form Schema 01-Apr-2026
|
|
|
|
Form 10BB (Upto A.Y. 2022-23)
Audit report under section 10(23C) of the Income-tax Act, 1961, in the case of any fund or trust or institution or any university or other educational institution or any hospital or other medical institution referred to in sub-clause (iv) or sub-clause (v) or sub-clause (vi) or sub-clause (via) of section 10(23C)
|
|
|
|
Date of first release of Form Utility 02-Sep-2022
|
|
|
|
Date of first release of Form Schema 17-Aug-2022
|
Form 15CA
Information to be furnished for payments to a non-resident not being a company, or to a foreign company.
|
|
|
|
|
|
|
|
Date of first release of Form Schema 02-Oct-2021
|
Form 15CB
Certificate of an accountant.
|
|
|
|
|
|
|
|
Date of first release of Form Schema 02-Oct-2021
|
Form 29B
Report under section 115JB of the Income-tax Act, 1961 for computing the book profits of the company.
|
|
|
|
Date of first release of Form Schema 09-Aug-2022
|
Date of latest release of Form Schema 01-Apr-2026
|
|
|
|
Form 29C
Report under section 115JC of the Income-tax Act, 1961 for computing Adjusted Total Income and Alternate Minimum Tax of the person other than a company.
|
|
|
|
Date of first release of Form Schema 09-Aug-2022
|
Date of latest release of Form Schema 01-Apr-2026
|
|
|
|
Form 3CEB
Report from an accountant to be furnished under section 92E relating to international transaction(s) and specified domestic transaction(s).
|
|
|
|
Date of first release of Form Utility 04-Oct-2022
|
Date of Latest release of Form Utility 01-Apr-2026
|
|
|
|
Date of first release of Form Schema 02-Sep-2022
|
Date of latest release of Form Schema 23-Dec-2025
|
|
|
|
Source: Income tax portal
|
|
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued following Notifications on 08.10.2024 viz.
|
- Amendment in GST rate on goods
- Notification no. 05/2024-Central Tax (Rate) dated 08.10.2024
- Notification no. 05/2024-Union Territory Tax (Rate) dated 08.10.2024
- Notification no. 05/2024-Integrated Tax (Rate) dated 08.10.2024
- Amendment in RCM on goods
- Notification no. 06/2024-Central Tax (Rate) dated 08.10.2024
- Notification no. 06/2024-Union Territory Tax (Rate) dated 08.10.2024
- Notification no. 06/2024-Integrated Tax (Rate) dated 08.10.2024
- Amendment in GST rate on services
- Notification no. 07/2024-Central Tax (Rate) dated 08.10.2024
- Notification no. 07/2024-Union Territory Tax (Rate) dated 08.10.2024
- Notification no. 07/2024-Integrated Tax (Rate) dated 08.10.2024
- Amendment in GST exemption on services
- Notification no. 08/2024-Central Tax (Rate) dated 08.10.2024
- Notification no. 08/2024-Union Territory Tax (Rate) dated 08.10.2024
- Notification no. 08/2024-Integrated Tax (Rate) dated 08.10.2024
- Amendment in RCM on services
- Notification no. 09/2024-Central Tax (Rate) dated 08.10.2024
- Notification no. 09/2024-Union Territory Tax (Rate) dated 08.10.2024
- Notification no. 09/2024-Integrated Tax (Rate) dated 08.10.2024
1. Amendment in GST rate on goods
|
Notification no. 05/2024 dated 08.10.24 issued to make further amendment in GST rate on goods notification no. 01/2017 dated 28.06.2017
|
Changes in 5% GST rate bracket
|
following entry no. inserted after item number 232
|
- "(233) Trastuzumab Deruxtecan
- (234) Osimertinib
- (235) Durvalumab"
Changes in 12% GST rate bracket
|
New serial no. 32C inserted "Extruded or expanded products, savoury or salted (other than un-fried or un-cooked snack pellets, by whatever name called, manufactured through process of extrusion)" falling under HSN 1095 90 30.
|
Changes in 18% GST rate bracket
|
column (3) of serial no. 16 is substituted as "un-fried or un-cooked snack pallets, by whatever name called, manufactured through process of extrusion, extruded or expanded products, savoury or salted".
|
serial no. 435A entry is substituted.
|
HSN 9401 , Seats (other than those of heading 9402), whether or not convertible into beds and parts thereof other than seats of a kind used in aircraft or seats of a kind used for motor vehicles".
|
Changes in 28% GST rate bracket
|
New entry 210A inserted "Seats of a kind used for motor vehicles"
|
This notification shall come into force with effect from the 10th day of October, 2024.
|
In line with the above stated amendment in CGST, an amendment in UTGST and IGST is made vide Notification no. 05/2024-Union Territory Tax (Rate) & Notification no. 05/2024-Integrated Tax (Rate) both dated 08.10.2024.
|
2. Amendment in RCM on goods
|
RCM on goods Notification no. 4/2017-Central Tax (Rate) dated 28.06.2017 is amended vide Notification no. 06/2024-Central Tax (Rate) dated 08.10.2024.
|
Entry no 8 is inserted whereby the supply of metal scrap is added under RCM. The registered recipient of metal scrap falling under HSCN 72, 73, 74, 75, 76, 77, 78, 79, 80 or 81 shall pay tax under RCM when the supply is received from an unregistered person.
|
This notification shall come into force with effect from the 10th day of October, 2024.
|
In line with the above stated amendment in CGST, an amendment in UTGST and IGST is made vide Notification no. 06/2024-Union Territory Tax (Rate) & Notification no. 06/2024-Integrated Tax (Rate) both dated 08.10.2024.
|
3. Amendment in GST rate on services
|
Notification no. 07/2024 dated 08.10.24 makes further amendment in the GST Rate on services notification no. 11/2017-Central Tax (Rate) dated 28.06.2017.
|
In the said notification, new item entry (ivb) is inserted whereby the GST rate on 'transportation of passengers, with or without accompanied baggage, by air, in a helicopter on seat share basis' is specified as 5% (CGST 2.5% + SGST 2.5%) provided that credit of input tax charged on goods used in supplying the service has not been taken.
|
Further, in serial no. (vii), after the brackets and figures (iva), the brackets and figures "(ivb)," shall be inserted.
|
This notification shall come into force with effect from the 10th day of October, 2024.
|
In line with the above stated amendment in CGST, an amendment in UTGST and IGST is made vide Notification no. 07/2024-Union Territory Tax (Rate) & Notification no. 07/2024-Integrated Tax (Rate) both dated 08.10.2024.
|
2. Amendment in GST exemption on services
|
Notification no. 08/2024 CTR dated 08.10.2024 issued to make further amendment in the service rate exemption notification no. 12/2017-CTR dated 28.06.2017.
|
New entry 25A is being inserted
|
Supply of services by way of providing metering equipment on rent, testing for meters/transformers/capacitors etc., releasing electricity connection, shifting of meters/service lines, issuing duplicate bills etc., which are incidental or ancillary to the supply of transmission and distribution of electricity provided by electricity transmission and distribution utilities to their consumers.
|
New entry 44A is being inserted
|
Research and development services against consideration received in the form of grants supplied by –
(a) a Government Entity; or
(b) a research association, university, college or other institution, notified under clauses
(ii) or (iii) of sub-section (1) of section 35 of the Income Tax Act, 1961.
|
falling under Heading 9981 ,
|
Provided that the research association, university, college or other institution, notified under clauses (ii) or (iii) of subsection (1) of section 35 of the Income Tax Act, 1961 is so notified at the time of supply of the research and development service."
|
New entry 66A is being inserted
|
Services of affiliation provided by a Central or State Educational Board or Council or any other similar body, by whatever name called, to a school established, owned or controlled by the Central Government, State Government, Union Territory, local authority, Governmental authority or Government entity.
|
falling under Heading 9992
|
Serial no. 69 shall be substituted
|
Any services provided by –
|
(a) the National Skill Development Corporation set up by the Government of India;
|
(b) he National Council for Vocational Education and Training;
|
(c) an Awarding Body recognized by the National Council for Vocational Education and Training;
|
(d) an Assessment Agency recognized by the National Council for Vocational Education and Training;
|
(e) a Training Body accredited with an Awarding Body that is recognized by the National Council for Vocational Education and Training,
|
(i) the National Skill Development Programme or any other scheme implemented by the National Skill Development Corporation; or
|
(ii) a vocational skill development course under the National Skill Certification and Monetary Reward Scheme; or
|
(iii) any National Skill Qualification Framework aligned qualification or skill in respect of which the National Council for Vocational Education and Training has approved a qualification package.
|
falling under Heading 9983 or Heading 9991 or Heading 9992.
|
Following term in Serial number 71 shall be substituted
|
against serial number 71, in column (3), for the words “National Council for Vocational Training”, the words “National Council for Vocational Education and Training” shall be substituted.
|
in paragraph 2 of the said notification,
|
(a) in sub-item (i), for the words “National Council for Vocational Training”, the words “National Council for Vocational Education and Training” shall be substituted.
|
(b) in sub-item (ii), for the words “National Council for Vocational Training”, the words “National Council for Vocational Education and Training” shall be substituted.
|
This notification shall come into force with effect from the 10th day of October, 2024.
|
In line with the above stated amendment in CGST, an amendment in UTGST and IGST is made vide Notification no. 08/2024-Union Territory Tax (Rate) & Notification no. 08/2024-Integrated Tax (Rate) both dated 08.10.2024.
|
4. Amendment in RCM on services
|
Notification no. 09/2024-Central Tax (Rate) dated 08.10.2024 issued to make further amendment in RCM notification no. 13/2017-Central Tax (Rate) dated 28.06.2017.
|
New entry no. 5AB is inserted whereby on the "Service by way of renting of any property other than residential dwelling." the recipient being registered person shall pay GST under RCM where the service is supplied by an unregistered person.
|
This notification shall come into force with effect from the 10th day of October, 2024.
|
In line with the above stated amendment in CGST, an amendment in UTGST and IGST is made vide Notification no. 09/2024-Union Territory Tax (Rate) & Notification no. 09/2024-Integrated Tax (Rate) both dated 08.10.2024.
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued following notifications -
|
- Notification no. 21/2024-Central Tax dated 08.10.2024 to give effect to Section 128A as 01.11.2024
- Notification no. 22/2024-Central Tax dated 08.10.2024 to provide special procedure for rectification of order u/s 73 , 74 or 107 or 108.
- Notification no. 23/2024-Central Tax dated 08.10.2024 waiver of late fees to person liable to deduct TDS u/s 51 for the month of June 2021 onwards
|
|
|
|
|
No, the Honorable Karnataka High Court in the case of M/s. Bangalore Golf Club v. Commercial Tax Officer set aside the order as no opportunity of hearing was granted to the Petitioner before passing an adverse order. The Honorable Court held that it is mandatory to grant the opportunity of hearing as required under section 75(4) of the CGST Act when an adverse order is being contemplated against the Petitioner.
|
The Honorable Karnataka High Court made clear that setting aside the impugned order is not to be taken as recording a finding as regards the contention of the petitioner regarding passing a common order for two different financial years.
|
This is expressly given in the statute that the opportunity of being heard must be presented where it is specifically asked by the taxpayer or where an adverse order is contemplated against the taxpayer. The petitioner must have disputed the service of notice and must have allowed the Revenue to discharge their burden to prove regarding service of notice. Approaching a writ court under Article 226 or Article 32 of the Constitution of India must be a strategic and well-thought decision. If the Honorable Court remands back the case for the second round of adjudication and the notice is not vacated, then it turns out to be a fruitless exercise unable to fetch the desired relief.
|
It is not always that suffering an ex-parte order will be disastrous. Most of the times, ex parte orders without a reply by taxpayers, are not sustainable on facts and law. Moreover, every mistake of the Revenue cannot become ground to vacate notice and achieve the desired outcome.
|
|
|
|
|
|
No, the Honorable Madras High Court in the case of Veeran Mehhta v. Deputy Commercial Tax Officer and Deputy State Tax Officer directed the disposal of the Order dated January 22, 2024, which was based on a mismatch of tax liability discharged in form GSTR-3B and belatedly filed Form GSTR-1. The Honorable Court held that no recovery or coercive measures could be initiated until the Petitioner’s rectification petition was resolved. The Honorable Madras High Court noted that the Petitioner placed on record the Form GSTR-3B for January in the assessment period 2018-2019. The Form GSTR-1, purportedly for July in the assessment period 2019-2020 was also on record. The outward taxable value pertaining to IGST in the two documents was tallied. The Petitioner also placed on record the tax liability comparison report from the GST portal. This document also indicated an excess in liability when the Form GSTR-3B and Form GSTR-1 were compared. Such excess was Rs. 4,17,577/-. In these circumstances, a prima facie case was made out for consideration of the rectification petition.
|
The Honorable Court held that the writ petition is disposed of and the Respondent is restrained from initiating recovery or coercive measures until the rectification petition was disposed of and lastly, directed the Respondent to consider and dispose of the rectification application within three months from the date of the order.
|
Section 161 has a very limited scope and it allows for the rectification of any error or mistake that is apparent from the record. It is important to note that ‘apparent on the face of record’ is not one that involves (i) a conclusion that cannot be reached without taking new facts on record during rectification proceedings or (ii) requiring application of mind to existing facts or interpretation already adopted in reaching the conclusion already reached. In the Author’s considered opinion, this is not a fit case to apply for rectification.
|
The only remedy is to prefer an appeal before the first appellate authority against the impugned order. If an appeal is not filed within the statutory time limit (3+1 months), then this remedy is lost forever and recovery action will be just and proper. Alternatively, cause-of-action (GSTR-1 vs GSTR-3B) could have been disputed, where notice ought to have been issued as per Section 75(12) in form DRC-01B and not under Section 73. Where a specific section is given under the statute to address the issue of mismatch of data reported in GSTR-1 and GSTR-3B, resorting to Section 73 is a gross misapplication of the law
|
|
|
|
|
|
No, the Honorable Patna High Court in the case of M/s Raj Kishore Sah v. Union of India , dismissed the writ petition challenging the cancellation of GST registration, where the Petitioner had not availed remedy of the Amnesty Scheme provided by the Government vide Notification No. 03/2023-Central Tax dated March 31, 2023 and filed the appeal after the time limit prescribed under section 107 of the Bihar Goods and Services Tax Act. The Honorable Patna High Court observed that the Petitioner was not a registered dealer and there was no monitoring of activities by the department in the intervening period. Further, there was no way to ascertain whether any transactions were carried out during the period when the Petitioner’s registration was canceled. The Honorable Court held that an appeal must be filed within three months of the order and delay is condoned if the appeal is delayed within one month of the expiry of the limitation. Therefore, the appeal ought to have been filed on or before January 11, 2023 or before February 10, 2023 with a delay condonation application. The Petitioner had filed a delayed appeal and had not availed remedy of the Amnesty Scheme offered by the government through the Notification. Hence, the court dismissed the petition and declined to exercise its discretion in favor of the Petitioner stating the law favors the diligent and not the indolent.
|
If the appeal is filed after the statutory period permitted in Section 107(4) (3+1 months), no authority can condone the delay, not even if the reasons are ample and deserve to be entertained. The appeal must be dismissed for being fatally belated because the Legislature has imposed certain limitations in the law.
|
Limitation is when a right continues but is no longer enforceable after the lapse of a certain time. If the appeal is not filed within the time limit given, then the statutory remedy is lost forever.
|
|
|
|
|
|
4. Lawgics by Ms.Nidhi Aggarwal
|
Ms. Nidhi Aggarwal is delighted to present judgment with a great vision to spread complex GST law in a simple manner amongst the taxpayers, tax professionals, students and knowledge seeker.
|
|
Recently added notes are listed below:
|
|
|
|
|
|
Synopsis: The Delhi High Court dismissed the writ petition involving fraudulent ITC claims, directing the petitioner to pursue appellate remedy u/s 107 of the CGST Act.
|
Caste name: Banson Enterprises & Anr. vs Assistant Commissioner CGST & Ors.
|
Citation: W.P. (C) 6503/2025 dated 15.05.2025
|
Authority: Delhi High Court
|
The petition challenges the Order-in-Original dated 02.02.2025 based on a Show Cause Notice (SCN) dated 03.08.2024 A search was conducted, and statements were recorded including that of one Director admitting to the issuance of fake invoices during the Central Excise period. It was alleged that the Petitioner issued goods-less invoices to enable fraudulent Input Tax Credit (ITC) claims amounting to Rs. 1.85 crore.
|
Contentions of the Petitioner:
|
SCN was issued by unauthorized officer, thus, violates Rule 142(1)(a) of CGST Rules. No pre-consultation as required under Rule 142(1A) of CGST Rules was issued. Consolidated SCN for multiple financial years was issued and challenge to such consolidated action is pending in a separate matter (Quest Infotech case).
|
Contentions of the Department:
The impugned order is appealable, hence writ is not maintainable. The Petitioner’s Director admitted to allegations. Natural justice was followed as the Petitioner received the SCN, filed a reply, and availed of personal hearing. Reliance must be made on SC judgments and Allahabad HC rulings emphasizing alternate remedy u/s 107 CGST Act.
|
Findings and Decision of the Court:
The Court refused to interfere under writ jurisdiction, citing:
|
- No breach of fundamental rights or principles of natural justice.
- Availability of a statutory remedy (appeal) under Section 107 CGST Act.
The Court noted that the Allegations involve serious misuse of ITC, requiring fact-based adjudication, not suited for writ jurisdiction. Thus, the Petitioner was granted liberty to file appeal, and if filed with pre deposit, the appeal shall not be dismissed on limitation.
|
|
|
|
|
|
5. GST Notes by CMA Anil Sharma
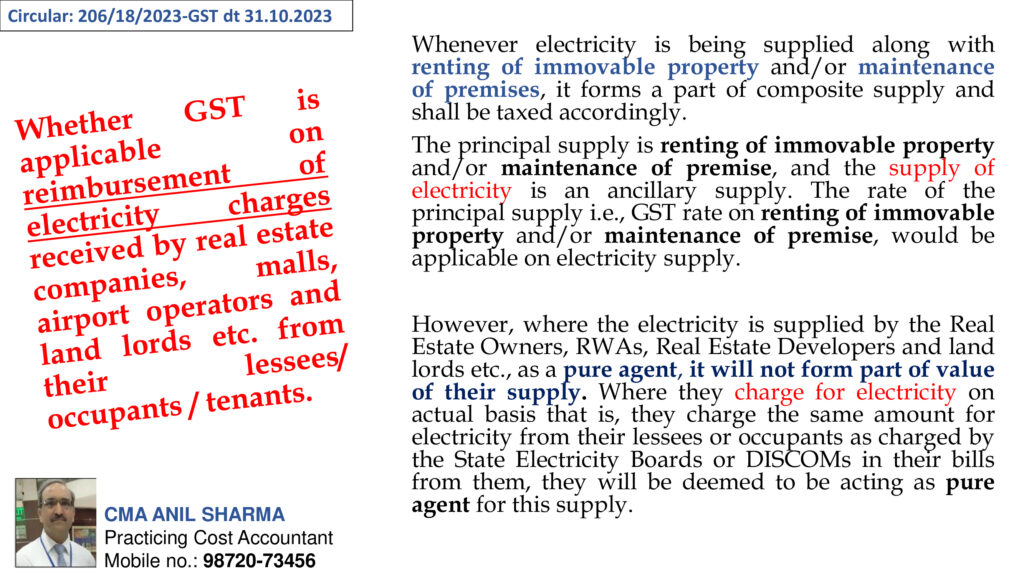
1) New slides on GST Circulars is added in the Notes section titled as "Capsules".
|
- Total 25 slides in capsule-01 is added
|
|
|
|
|
|
|
|
6. GST Daily by CA Pradeep Modi
CA Pradeep Modi is presenting judgment analysis under title 'GST Daily - Stay yourself updated'
|
|
|
|
|
|
|
Recap of Latest updates posted on 27.08.2026
|
CBIC issued Notification No. 30/2026-Customs dated 21.08.2026 regarding Seeks to exempt 10 lakh MT of raw sugar falling under tariff heading 1701 from the whole of the customs duty leviable thereon under …
|
GSTN is taking downtime to enhance its services on the GST Portal on 26.08.2026 from 12:00 AM onwards until 6:30 am of 26.08.2026.
|
The Hon’ble Supreme Court in M/s G.R. Infra Projects Limited set aside the Show Cause Notice dated June 13, 2025 issued under Section 74 of the CGST Act read with the MPGST Act for the FY 2018-19, and held that a bland and mechanical recital of the words ‘fraud or concealment of facts’,
|
Indian Railway Finance Corporation Ltd received a show cause notice from the GST Authority demanding ₹549.32 crore. The notice, issued under Section 73 of the Central Goods and Services Tax Act, 2017, cites excess input tax credit claims for FY23.
|
The Anti-Corruption Bureau (ACB) on Monday arrested a state tax officer and a senior assistant in Nirmal district for demanding and accepting a bribe of ₹50,000 in connection with a GST audit.
|
CBIC issued Notification No. 71/2026-Customs (N.T.) dated 25.08.2026 regarding Fixation of Tariff Value of Edible Oils, Brass Scrap, Areca Nut, Gold and Silver
|
CBIC issued Notification no. 21/2026-Customs (ADD) dated 21.08.2026 that Seeks to continue applicability of anti-dumping duty on imports of Natural Mica based Pearl Industrial Pigments ..
|
CBDT issued notification no. 115/2026 dated 21.08.2026 to hereby approves deduction under section 45(3)(a)(i) of the Income tax Act, 2025 to the International Institute of Bio Technology and Toxicology , Tamil Nadu for Scientific Research
|
I request the views of tax professionals and TDS experts on the following issue under the Income-tax Act, 2025, regarding reporting in Form 140.
|
|
|
|
|
|
7. PPT/Handbook on GST
|
|
|
|
8. GST/Income Tax in Media
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Hope the above updates is of use to you. Please share your input and feedback at taxupdate.otu@gmail.com
|
|
|
|
|
|
|
|
 
|
Visit our website
|
OTU provides you
|
- Articles on various topics
|
|
- Media - GST, Income Tax & Press R.
|
|
|
|
|
