|
|

|
|
|
|
|
|
This website contains information about recent changes mainly in GST laws. It also contains Articles on various topic in GST. Please visit the website and read more.
|
|
|
|
Dear Reader,
|
Please find newsletter for your reading and reference.
|
|
Newsletter no. 94 dated 22.07.2023
|
|
|
Index of the Newsletter
- Recent updates
- GST in media
- Income Tax in media
- Articles
- Lawgics by Ms.Nidhi Aggarwal
- GST notes by CMA Anil Sharma
|
|
|
|
|
|
|
Clarification to deal with difference in Input Tax Credit (ITC) availed in FORM GSTR-3B as compared to that detailed in FORM GSTR-2A for the period 01.04.2019 to 31.12.2021.
|
Circular No. 193/05/2023-GST
|
File No. CBIC-20001/5/2023-GST
|
Central Board of Indirect Taxes and Customs
|
The Principal Chief Commissioners/Chief Commissioners/Principal Commissioners/ Commissioners of Central Tax (All)
|
The Principal Directors General/ Directors General (All)
|
Subject: Clarification to deal with difference in Input Tax Credit (ITC) availed in FORM GSTR-3B as compared to that detailed in FORM GSTR-2A for the period 01.04.2019 to 31.12.2021.
|
Attention is invited to Circular No. 183/15/2022-GST dated 27th December, 2022, vide which clarification was issued for dealing with the difference in Input Tax Credit (ITC) availed in FORM GSTR-3B as compared to that detailed in FORM GSTR-2A for FY 2017-18 and 2018-19, subject to certain terms and conditions.
|
2. Even though the availability of ITC was subjected to restrictions and conditions specified in Section 16 of Central Goods and Services Tax Act, 2017 (hereinafter referred to as “CGST Act”) from 1st July, 2017 itself, restrictions regarding availment of ITC by the registered persons up to certain specified limit beyond the ITC available as per FORM GSTR-2A were provided under rule 36(4) of Central Goods and Services Tax Rules, 2017 (hereinafter referred to as “CGST Rules”) only with effect from 9th October 2019. W.e.f. 09.10.2019, the said rule allowed availment of Input tax credit by a registered person in respect of invoices or debit notes, the details of which have not been furnished by the suppliers under sub-section (1) of section 37, in FORM GSTR-1 or using the invoice furnishing facility (IFF), to the extent not exceeding 20 per cent. of the eligible credit available in respect of invoices or debit notes the details of which have been furnished by the suppliers under sub-section (1) of section 37 of CGST Act in FORM GSTR-1 or using the IFF. The said limit was brought down to 10% w.e.f. 01.01.2020 and further reduced to 5% w.e.f. 01.01.2021. The said rule was intended to allow availment of due credit in cases where the suppliers may have delayed in furnishing the details of outward supplies. Further, w.e.f. 01.01.2022, consequent to insertion of clause (aa) to sub-section (2) of section 16 of the CGST Act, ITC can be availed only up to the extent communicated in FORM GSTR-2B.
|
3.1 As discussed above, rule 36(4) of CGST Rules allowed additional credit to the tune of 20%, 10% and 5%, as the case may be, during the period from 09.10.2019 to 31.12.2019, 01.01.2020 to 31.12.2020 and 01.01.2021 to 31.12.2021 respectively, subject to certain terms and conditions, in respect of invoices/supplies that were not reported by the concerned suppliers in their FORM GSTR-1 or IFF, leading to discrepancies between the amount of ITC availed by the registered persons in their returns in FORM GSTR-3B and the amount as available in their FORM GSTR-2A. It may, however, be noted that such availment of input tax credit was subject to the provisions of clause (c) of sub-section (2) of section 16 of the CGST Act which provides that ITC cannot be availed unless tax on the said supply has been paid by the supplier. In this context, it is mentioned that rule 36(4) of CGST Rules was a facilitative measure and availment of ITC in accordance with rule 36(4) was subject to fulfilment of conditions of section 16 of CGST Act including those of clause (c) of sub-section (2) thereof regarding payment of tax by the supplier on the said supply.
|
3.2 Though the matter of dealing with difference in Input Tax Credit (ITC) availed in FORM GSTR-3B as compared to that detailed in FORM GSTR-2A has been clarified for FY 2017-18 and 2018-19 vide Circular No. 183/15/2022-GST dated 27th December, 2022, various representations have been received seeking clarification regarding the manner of dealing with such discrepancies between the amount of ITC availed by the registered persons in their FORM GSTR-3B and the amount as available in their FORM GSTR-2A during the period from 01.04.2019 to 31.12.2021.
|
4. In order to ensure uniformity in the implementation of the provisions of the law across the field formations, the Board, in exercise of its powers conferred under section 168(1) of the CGST Act, hereby clarifies as follows:
|
(i) Since rule 36(4) came into effect from 09.10.2019 only, the guidelines provided by Circular No. 183/15/2022-GST dated 27th December, 2022 shall be applicable, in toto, for the period from 01.04.2019 to 08.10.2019.
|
(ii) respect of period from 09.10.2019 to 31.12.2019, rule 36(4) of CGST Rules permitted availment of Input tax credit by a registered person in respect of invoices or debit notes, the details of which have not been furnished by the suppliers under sub-section (1) of section 37, in FORM GSTR-1 or using IFF to the extent not exceeding 20 per cent. of the eligible credit available in respect of invoices or debit notes, the details of which have been furnished by the suppliers under sub-section (1) of section 37 in FORM GSTR-1 or using IFF. Accordingly, the guidelines provided by Circular No. 183/15/2022-GST dated 27th December, 2022 shall be applicable for verification of the condition of clause (c) of sub-section (2) of Section 16 of CGST Act for the said period, subject to the condition that availment of Input tax credit by the registered person in respect of invoices or debit notes, the details of which have not been furnished by the suppliers under sub-section (1) of section 37, in FORM GSTR-1 or using IFF shall not exceed 20 per cent. of the eligible credit available in respect of invoices or debit notes the details of which have been furnished by the suppliers under sub-section (1) of section 37 in FORM GSTR-1 or using IFF. This is clarified through an illustration below:
|
Consider a case where the total amount of ITC available as per FORM GSTR-2A of the registered person was Rs. 3,00,000, whereas, the amount of ITC availed in FORM GSTR-3B by the said registered person during the corresponding tax period was Rs. 5,00,000. However, as per rule 36(4) of CGST Rules as applicable during the said period, the said registered person was not allowed to avail ITC in excess of an amount of Rs 3,00,000*1.2 = Rs.3,60,000.
|
In the above case, the ITC of Rs 1,40,000 which has been availed in excess of Rs. 3,60,000 shall not be admissible as per rule 36(4) of CGST Rules as applicable during the said period even if the requisite certificate as prescribed in Circular No. 183/15/2022-GST dated 27.12.2022 is submitted by the registered person. Therefore, ITC availed in FORM GSTR-3Bin excess of that available in FORM GSTR-2A up to an amount of Rs 60,000 only (i.e. 3,60,000-3,00,000) can be allowed subject to production of the requisite certificates as per Circular No. 183/15/2022-GST dated 27.12.2022.
|
(iii) Similarly, for the period from 01.01.2020 to 31.12.2020, when rule 36(4) of CGST Rules allowed additional credit to the tune of 10% in excess of the that reported by the suppliers in their FORM GSTR-1 or IFF, the guidelines provided by Circular No. 183/15/2022-GST dated 27th December, 2022 shall be applicable, for verification of the condition of clause (c) of sub-section (2) of Section 16 of CGST Act for the said period, subject to the condition that availment of Input tax credit by the registered person in respect of invoices or debit notes, the details of which have not been furnished by the suppliers under sub-section (1) of section 37, in FORM GSTR-1 or using the IFF shall not exceed 10 per cent. of the eligible credit available in respect of invoices or debit notes the details of which have been furnished by the suppliers under sub-section (1) of section 37 in FORM GSTR-1 or using the IFF.
|
(iv) Further, for the period from 01.01.2021 to 31.12.2021, when rule 36(4) of CGST Rules allowed additional credit to the tune of 5% in excess of that reported by the suppliers in their FORM GSTR-1 or IFF, the guidelines provided by Circular No. 183/15/2022-GST dated 27th December, 2022 shall be applicable, for verification of the condition of clause (c) of sub-section (2) of Section 16 of CGST Act for the said period, subject to the condition that availment of Input tax credit by the registered person in respect of invoices or debit notes, the details of which have not been furnished by the suppliers under sub-section (1) of section 37, in FORM GSTR-1 or using the IFF shall not exceed 5 per cent. of the eligible credit available in respect of invoices or debit notes the details of which have been furnished by the suppliers under sub-section (1) of section 37 in FORM GSTR-1 or using the IFF.
|
5. It is further clarified that consequent to insertion of clause (aa) to sub-section (2) of section 16 of the CGST Act and amendment of rule 36(4) of CGST Rules w.e.f. 01.01.2022, no ITC shall be allowed for the period 01.01.2022 onwards in respect of a supply unless the same is reported by his suppliers in their FORM GSTR-1 or using IFF and is communicated to the said registered person in FORM GSTR-2B.
|
6. Further, it may be noted that proviso to rule 36(4) of CGST Rules was inserted vide Notification No. 30/2020-CT dated 03.04.2020 to provide that the condition of rule 36(4) shall be applicable cumulatively for the period February to August, 2020 and ITC shall be adjusted on cumulative basis for the said months in the return for the tax period of September 2020. Similarly, second proviso to rule 36(4) of CGST Rules was substituted vide Notification No. 27/2021-CT dated 01.06.2021 to provide that the condition of rule 36(4) shall be applicable cumulatively for the period April to June, 2021 and ITC shall be adjusted on cumulative basis for the said months in the return for the tax period of June 2021. The same may be taken into consideration while determining the amount of ITC eligibility for the said tax periods.
|
7. It may also be noted that these guidelines are clarificatory in nature and may be applied as per the actual facts and circumstances of each case and shall not be used in the interpretation of the provisions of law.
|
8. These instructions will apply only to the ongoing proceedings in scrutiny/ audit/ investigation, etc. for the period 01.04.2019 to 31.12.2021 and not to the completed proceedings. However, these instructions will apply in those cases during the period 01.04.2019 to 31.12.2021 where any adjudication or appeal proceedings are still pending.
|
9. Difficulty, if any, in the implementation of the above instructions may please be brought to the notice of the Board. Hindi version would follow.
|
Principal Commissioner (GST)
|
|
|
|
|
|
|
|
|
|
Clarification on charging of interest under section 50(3) of the CGST Act, 2017, in cases of wrong availment of IGST credit and reversal thereof.
|
Circular No. 192/04/2023-GST
|
File No. CBIC-20001/5/2023-GST
|
Central Board of Indirect Taxes & Customs
|
The Principal Chief Commissioners/ Chief Commissioners/ Principal Commissioners/ Commissioners of Central Tax (All)
|
The Principal Directors General/ Directors General (All)
|
Subject: Clarification on charging of interest under section 50(3) of the CGST Act, 2017, in cases of wrong availment of IGST credit and reversal thereof.
|
References have been received from trade requesting for clarification regarding charging of interest under sub-section (3) of section 50 of the Central Goods and Services Tax Act, 2017 (hereinafter referred to as the “CGST Act”) in the cases where IGST credit has been wrongly availed by a registered person. Clarification is being sought as to whether such wrongly availed IGST credit would be considered to have been utilized for the purpose of charging of interest under sub-section (3) of section 50 of CGST Act, read with rule 88B of Central Goods and Services Tax Rules, 2017 (hereinafter referred to as the “CGST Rules”), in cases where though the available balance of IGST credit in the electronic credit ledger of the said registered person falls below the amount of such wrongly availed IGST credit, the total balance of input tax credit in the electronic credit ledger of the registered person under the heads of IGST, CGST and SGST taken together remains more than such wrongly availed IGST credit, at all times, till the time of reversal of the said wrongly availed IGST credit.
|
2. Issue has been examined and to ensure uniformity in the implementation of the provisions of law across the field formations, the Board, in exercise of its powers conferred by section 168 (1) of the CGST Act, hereby clarifies the issues as under:
|
3. It is requested that suitable trade notices may be issued to publicize the contents of this Circular.
|
4. Difficulty, if any, in implementation of this Circular may please be brought to the notice of the Board. Hindi version would follow.
|
Principal Commissioner (GST)
|
|
|
|
|
|
|
|
|
|
CBIC has issued Circular no. 192 to 199 today 17.07.2023 giving effect to 50th GST Council meeting held on 11.07.2023.
|
Table showing the circular no. and changes in brief.
|
|
|
|
|
|
|
|
2. GST in Media - Council meeting
|
|
|
|
|
The GST Council’s recent decision to impose 28 per cent tax on the full face value of bets placed in horse racing is a “great disappointment” for the horse racing industry, according to the Turf Authorities of India (TAI).
|
At its 50th meeting held on July 11, the GST Council imposed a 28 per cent tax on the turnover of online gaming companies, horse racing and casinos.
|
Commenting on the same, TAI said the GST Council has failed to appreciate the special features of horse racing, distinguishing it from other gaming platforms. TAI said horse racing is a sport recognised internationally and even in India for over 200 years. “It is supervised, organised and regulated by us,” it added.
|
|
|
|
|
|
|
|
|
|
The North Eastern states are success stories of GST collection and devolution, Union Finance Minister Nirmala Sitharaman said in Guwahati on 21 July.
|
According to the 2023 RBI report on state finances, the eight NE states have registered a compounded annual GST hike of 27.5 per cent, the finance minister said.
|
Her comments came at the Investiture Ceremony for conferring the Presidential Award for ‘Specially Distinguished Record of Service’ to officers and staff of the Central Board of Indirect Taxes and Customs (CBIC).
|
|
|
|
|
|
|
|
|
|
The Gujarat State Tax Bar Association has written request letter to Smt. Nirmala Sitharaman, Hon. Union Minister of Finance & Chairman of GST Council.
|
The extract of the letter -
|
We would like to bring to your notice that, on 18th and 19th July, 2023 there was heavy rain in certain parts of Gujarat like coastal districts of Saurashtra, Gir, etc., under another onslaught of rain fury with a large part of Sutrapada and Dhoraji towns getting submerge in waist high water. Due to heavy rain all normal life is disturbed and people are forced to stay in house, as there is a risk of life.
|
As you are aware that, due date for GSTR-3B for the month of June is 20th July, 2023, we request your honor to kindly extend this due date due to natural calamity faced by people of Gujarat.
|
We request you to kindly accelerate this issue and request for early notification of extension to avoid late fees and consequential issues.
|
Torrential raise caused severe water logging across the state and country as well, normal life of people is disrupted there is serious problem of electricity, internet connectivity, and commune of staff for the tax payers. Heavy rainfall is also forecasted in Gujarat as well as other parts of the country flood like situation as heavy shower is also forecasted by Indian metrological department. In this situation and circumstances your honour is humbly requested and prayed - kindly extend the due date for GSTR-3B for the moth of Jun 2023, For further period of fifteen days i.e. 05th August 2023.
|
We are hopeful that government will understand the concern explain by us and well come out with positive action of extension on urgent basis.
|
Pritesh Gandhi / Prashant Shah
|
|
|
|
|
|
|
|
|
|
Delhi Police has arrested a 42-year-old man who along with his accomplices cheated a Ludhiana-based jeweller of 10kg gold plates valued at approximately Rs 6 crore by impersonating the Inspectors of central GST officers, an official said on Tuesday.
|
The accused, identified as Sushil Kumar alias Toppi, a resident of Ludhiana, used to go to the GST office in a routine manner and had gained some knowledge of the working of GST officers. DCP (outer) Harendra K Singh said an FIR was registered on the complaint of Ravinder Kumar, in which he stated that he purchases gold from Delhi in routine for making gold jewellery and sells it in the local market.
|
“On July 10, he sent his driver Balraj and worker Rajan Bawa to take the delivery of gold from Delhi with GST bills. Around 9 pm they took the delivery of gold and left for Ludhiana (Punjab) in an Ertiga car. Around 9:30 pm when they reached near Haryana Maitri Bhawan, Near West Enclave, one white i20 car overtook them and two unknown persons came out of that i20 Hyundai car and introduced themselves as Inspector from the Central GST department,” the DCP said.
|
|
|
|
|
|
|
|
|
|
The Group of Ministers (GoM) of the Goods and Services Tax Council that was tasked with rate rationalisation is likely to be reconstituted soon, with Karnataka Revenue Minister Krishna Byre Gowda set to become a member.
|
The position of convenor has been lying vacant since change of government in Karnataka. Former Karnataka chief minister Basavaraj Bommai was earlier the convenor of the seven-member committee. A decision on the convenor will be taken after the GoM is reconstituted.
|
However, a major overhaul of the GST rate structure is unlikely ahead of the general elections in 2024. “The GoM is being reconstituted. It is only after that that the process of rate rationalisation will be reviewed,” said a senior official.
|
|
|
|
|
|
|
|
3. Direct Tax Collections for F.Y. 2023-24 up to 09.07.2023
|
The provisional figures of Direct Tax collections up to 09th July, 2023 continue to register steady growth. Direct Tax collections up to 09th July, 2023 show that gross collections are at Rs. 5.17 lakh crore which is 14.65% higher than the gross collections for the corresponding period of last year. Direct Tax collection, net of refunds, stands at Rs. 4.75 lakh crore which is 15.87% higher than the net collections for the corresponding period of last year. This collection is 26.05% of the total Budget Estimates of Direct Taxes for F.Y. 2023-24.
|
|
Refunds amounting to Rs.42,000 crore have been issued during 1st April, 2023 to 09th July 2023, which are 2.55% higher than refunds issued during the same period in the preceding year.
|
|
|
|
4 Article
|
|
|
|
|
50th GST Council meeting was held on 13.07.2023.
|
CA Vaishali Kharde has presented the recommendations of the GST Council meeting in PPT form.
|
|
Author: CA Vaishali Kharde
|
|
|
|
|
|
|
|
5 Lawgics by Ms.Nidhi Aggarwal
|
|
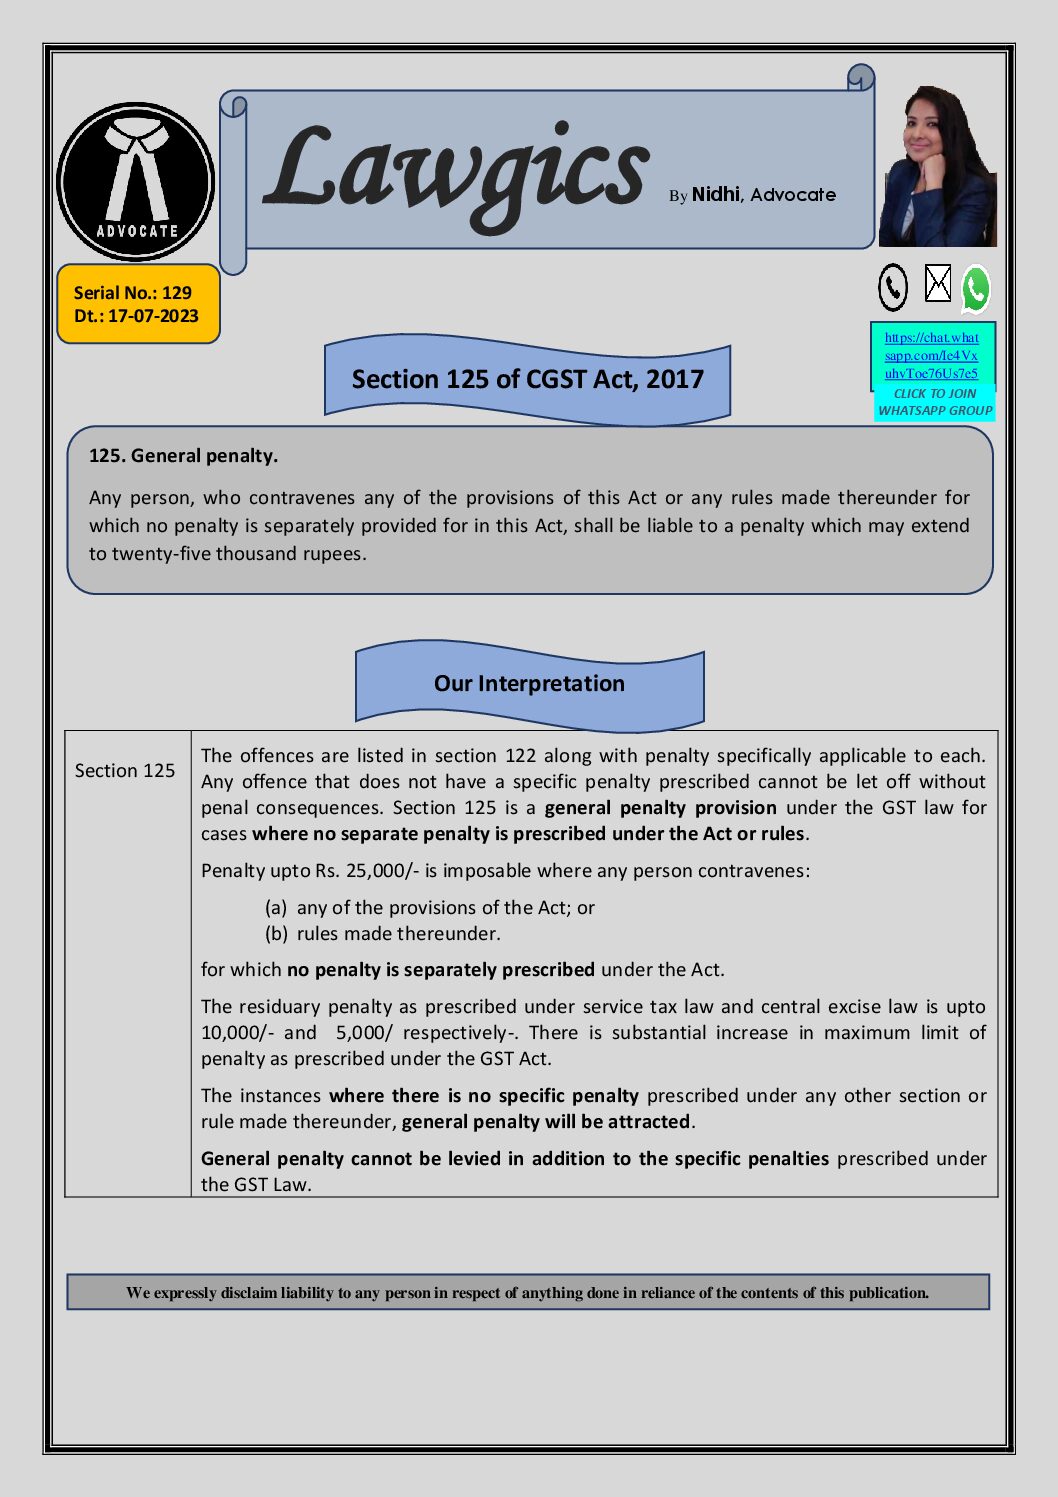
Ms. Nidhi Aggarwal is delighted to present GST Notes/Law in a simplified manner under the title “ Lawgics ”. The note is prepared in a series of PDFs encompassing GST Law and the interpretations thereof in simple manner. The author with a great vision to spread complex GST law in a simple manner amongst the taxpayers, tax professionals, students and knowledge seeker is presenting the Lawgics in piecemeal at regular interval.
|
|
|
|
|
|
|
6. GST Notes by CMA Anil Sharma
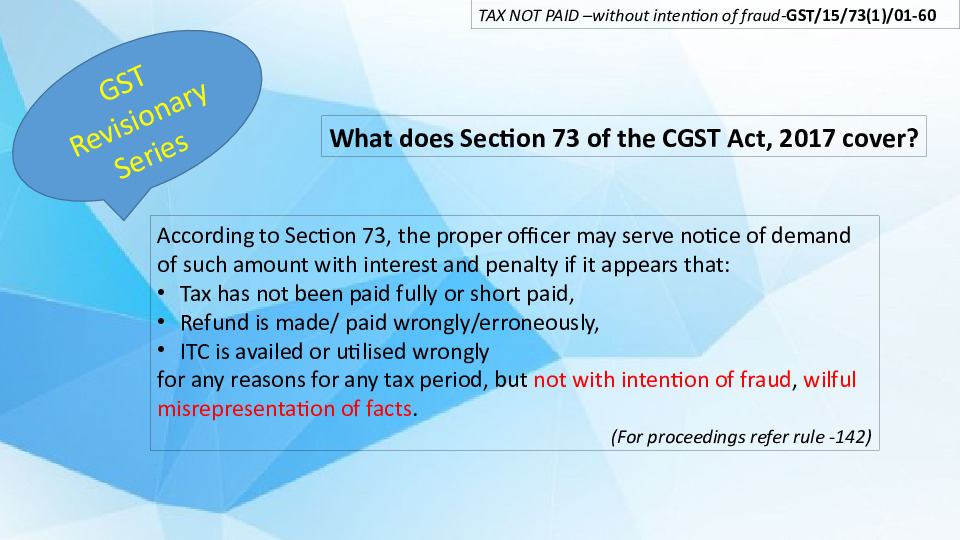
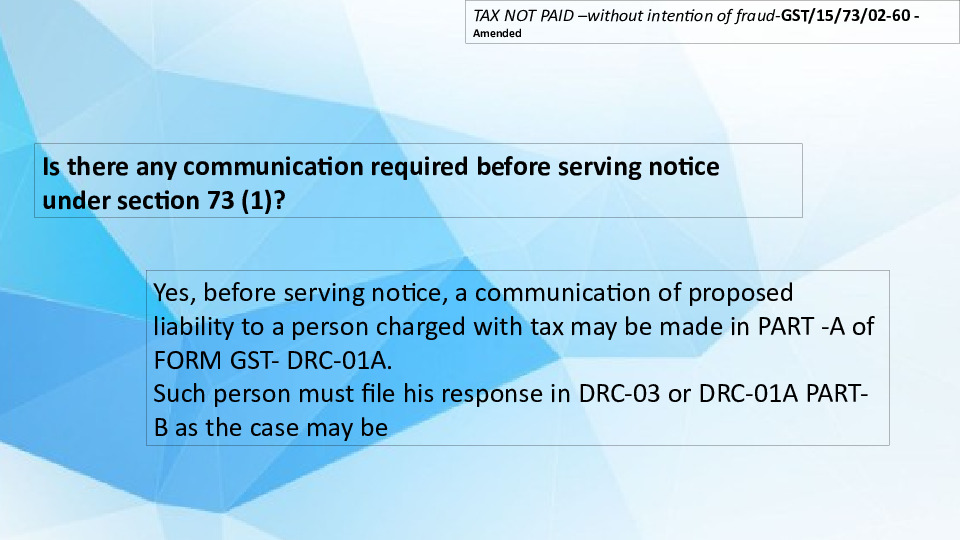
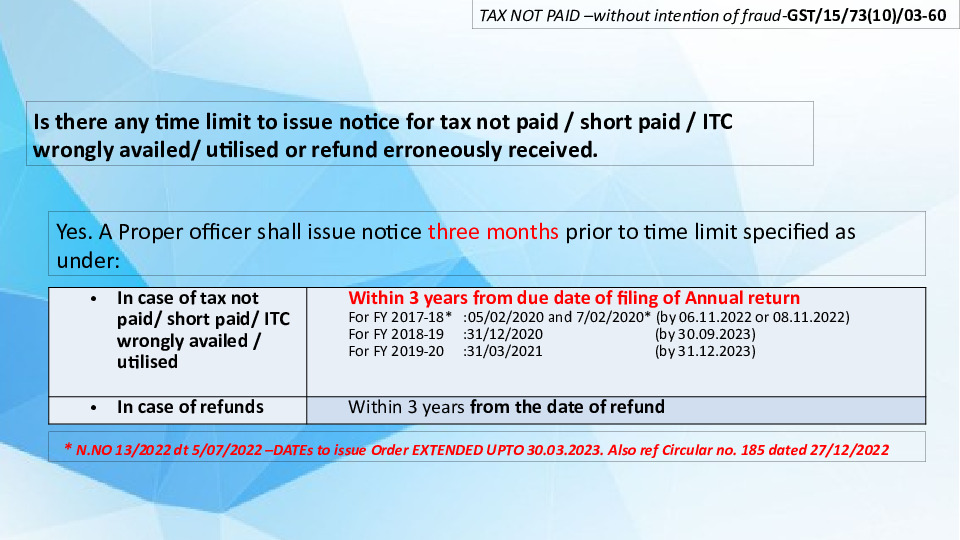
1) Shri CMA Anil Sharma, Shri CMA Gurdev Singh Saini and Smt. CMA Bhawna Sharma posted Chapter-15 containing CGST Act in simple language in PPT format. This is to make dealers, professionals, academicians, students etc. understand the basics of GST laws. Each Chapter in CGST Act, 2017 is explained in the form of Slides as given below for easy understanding of the Act:
|
Chapter-15 slides given below:-
|
|
|
|
|
|
|
|
|
|
|
You wish to publish your Article?
|
If you wish to share your article with maximum readers then please send the article at taxupdate.otu@gmail.com. We shall publish it with all due credit to you.
|
|
|
|
|
|
|
Hope the above updates is of use to you. Please share your input and feedback at taxupdate.otu@gmail.com
|
|
|
|
|
|
 
|
Visit our website
|
OTU provides you
|
- Articles on various topics
|
|
- Media - GST, Income Tax & Press R.
|
|
- Notes / Newsletter at 149/ p.a.
|
|
|
|
|