|
onlinetaxupdate team wish to express sincere thanks to all the readers, authors, subscribers for the support extended to us. Please share your feedback at
|
taxupdate.otu@gmail.com or 7738647904
|
Newsletter 142 dated 07.11.2024
|
|
|
|
|
|
|
|
|
Dear Reader,
|
Please find newsletter for your reading and reference.
|
|
Index of the Newsletter
- Recent updates
- Portal updates
- Article
- Lawgics by Ms.Nidhi Aggarwal
- GST Notes by CMA Anil Sharma
- GST Daily by CA Pradeep Modi
- PPT/Handbook
- GST/IT/Customs in media
|
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Circular no. 41/2026-Customs dated 03.09.2026 regarding National Assessment Centre (NAC) Portal for Trade and department for effective dissemination of information
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Instruction no. 17/2026-Customs dated 21.09.2026 giving Clarification in respect of difficulties being faced by field formations in adjudication of cases where Show Cause Notices have been issued under Section 28AAA of the Customs Act, 1962 in light of TRU instruction vide D.O. letter dated 01.06.2012 at para II.2
|
|
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Instruction no. 16/2026-Customs dated 18.09.2026 regarding Authorised Officers under Section 25 read with Section 47 (5) of Food Safety Standards (FSS) Act, 2006 and Regulation 13 (1) of FSS (Import) Regulation, 2017 .
|
|
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Instruction no. 15/2026-Customs dated 09.09.2026 regarding Registration of Importers under Centralized EPR Portal for Plastic Packaging as per Plastic Waste Management Rules, 2016 (as amended) and verification of registration
|
|
|
|
|
|
CBIC issued Notification No. 75 /2026-Customs (N.T.) dated 15.09.2026 regarding Fixation of Tariff Value of Edible Oils, Brass Scrap, Areca Nut, Gold and Silver
|
|
|
|
|
|
|
|
CBIC issued Notification No. 74 /2026-Customs (N.T.) dated 01.09.2026 regarding Appointment of Common Adjudicating Authority in the case of M/s. Akwel Automative Pune India Pvt. Ltd. (IEC: 3105015850) – Consolidated Adjudication of Multiple Show Cause Notices arising from SVB Investigation Report No. 198/AC/SVB/SKB/2022-23 dated 20.12.2022
|
|
|
|
|
|
|
|
CBIC issued Notification No. 73 /2026-Customs (N.T.) dated 01.09.2026 regarding The Sea Cargo Manifest and Transshipment Regulations (SCMTR), 2018
|
|
|
|
|
|
|
|
CBIC issued Notification No. 72 /2026-Customs (N.T.) dated 31.08.2026 regarding Fixation of Tariff Value of Edible Oils, Brass Scrap, Areca Nut, Gold and Silver
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Trade Notice 28/2026-27 dated 16.09.2026 regarding Revision in Timeline for Issuance of PSIC and One-time Relaxation for Issuance of Backlog PSICs
|
Kind attention is invited to earlier Trade Notice No. 22/2026-27 dated 25.08.2026 regarding enhancements in the Pre-Shipment Inspection Agency (PSIA)/Pre Shipment Inspection Certificate (PSIC) process.
|
2. In order to facilitate smooth implementation of the revised PSIA/PSIC module, the following relaxations are hereby made to the provisions contained in the aforesaid Trade Notice:
|
i. One-time transitional arrangement for issuance of PSICs
|
A one-time relaxation of seven days from the date of issuance of this trade notice is hereby provided to the recognized PSIAs for clearing the backlog PSICs pertaining to inspections conducted prior to 25.08.2026, where such certificates could not be issued due to system restrictions introduced pursuant to the aforesaid Trade Notice.
|
ii. Revision in timeline for issuance of PSIC
|
Para 2(ii) of Trade Notice No. 22/2026-27 dated 25.08.2026 shall stand substituted with the following:
|
"The PSIC shall be generated and issued within 2 days from the date of inspection. The system shall permit generation and issuance of the PSIC only within the prescribed timeline. The PSIC uploading shall be done from the same geographical location/country where inspection is carried out."
|
3. All other provisions of Trade Notice No. 22/2026-27 dated 25.08.2026 shall remain unchanged.
|
This issues with the approval of the DG, DGFT.
|
|
|
|
|
|
|
|
The Directorate of Revenue Intelligence (DRI) seized more than 362 metric tonnes of Pakistan-origin dry dates under 'Operation Deep Manifest' during an enforcement drive targeting illicit trade conduits.
|
Acting on specific actionable intelligence, operational teams intercepted 13 cargo containers carrying the consignments at CFS Ahmad in Nashik , which a Mumbai-based commercial entity imported.
|
According to the Ministry of Finance, the shipments arrived via Jebel Ali in the United Arab Emirates, accompanied by import clearance paperwork that falsely declared the UAE as the sovereign country of origin.
|
Official findings revealed that the commercial consignment moved through a deliberate routing network designed to mask its true origin. The cargo started its maritime transit from Karachi Port in Pakistan, reaching Jebel Ali Port in the UAE abroad an initial vessel.
|
"Preliminary investigation revealed a carefully orchestrated transshipment arrangement designed to conceal the Pakistan-origin of the goods," the Ministry stated.
|
The operational breakdown showed that the illicit cargo underwent minimal physical handling in the Gulf transit hub to obscure the paper trail.
|
"The dry dates were initially shipped from Karachi Port, Pakistan, to Jebel Ali Port, UAE, in one set of containers aboard one vessel," the official statement noted.
|
Handlers in the transit zone then re-routed the shipment onto another carrier line, it state.
|
"At Jebel Ali, the goods were merely transshipped and transferred to another set of containers and loaded onto a different vessel for onward shipment to India through entities operated by Pakistani nationals," the Ministry confirmed.
|
Border and port enforcement tightened following regulatory revisions enacted by the Directorate General of Foreign Trade (DGFT) in mid-2025.
|
The Ministry mentioned that following the Pahalgam terror attack, the Government of India, in the interest of national security, imposed a complete prohibition on the direct or indirect import or transit of all goods originating in or exported from Pakistan, with effect from 02.05.2025, vide DGFT notification no. 06/2025-26 dated 02.05.2025.
|
To counter non-compliant import tactics across container terminals, central enforcement authorities launched structured surveillance protocols targeting third-party trade jurisdications.
|
"In response, DRI, under 'Operation Deep Menifest", has been consistently identifying, intercepting and seizing Pakistan-origin goods attempted to be imported into India through third-country routing," the Ministry said.
|
Customs and intelligence officials continue to track intermediate entities connected to commercial paper falsification, fraudulent routing manifests, and proxy transshipment nodes.
|
"The seizure underscores (DRI's sustained resolve to identify, disrupt and dismantle sophisticated networks seeking to circumvent trader prohibitions through misdeclaration , transshipment and manipulation of documentation, thereby safeguard national security and straightening supply chain integrity," the Ministry added.
|
|
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Notification No. 36/2026-27 dated 15.09.2026 regarding De minimis exemption from Registration-cum-Membership Certificate (RCMC) requirements for low-value exports
|
|
|
|
|
|
Central Board of Direct Taxes issued Circular no. 6 of 2026 dated 02.07.2026 regarding Condonation of delay in filing Form No. 10AB electronically for approval under clause (ii) of the first proviso to section 80G(5) of the Income tax Act, 1961
|
|
|
|
|
|
|
|
Central Board of Direct Taxes issued Circular no. 4 of 2026 dated 31.03.2026 regarding Document Identification Number (DIN).
|
|
|
|
|
|
Central Board of Direct Taxes (CBDT) issued notification no. 120/2026 dated 17.09.2026 to hereby make following rules further to amend the Income tax Rules, 2026 , namely -
|
These rules may be called the Income-tax (Fourth Amendment) Rules, 2026
|
|
|
|
|
|
Press release no. 2300883 dated 18.08.2026
|
Top Tax Officials Deliberate on Key Issues Concerning the Income Tax Department at Conclave
|
The two-day conclave of Principal Chief Commissioners of Income Tax and Principal Directors General of Income Tax, organized by the Income Tax Department, concluded today, August 18, in Jaipur. The conclave was chaired by Shri Ravi Agrawal, Chairman, Central Board of Direct Taxes (CBDT).
|
The event was attended by Members of the CBDT—Shri Pankaj Kumar Mishra, Shri Sanjay Bahadur, Shri Prasenjit Singh, Ms. G. Aparna Rao, Ms. Pallavi Agrawal and Shri Sunil Kumar Singh—along with Principal Chief Commissioners, Principal Directors General, Commissioners of Income Tax (Administration) and other senior officers from across the country.
|
The conclave witnessed extensive deliberations on key issues concerning the Income Tax Department, including e-HRMS, service matters, litigation, reservation policy, taxpayer services, future projects, the Systems Directorate, capacity building, infrastructure, expenditure budget, TDS administration and inter-agency coordination. Senior officers also shared their views and suggestions on the challenges and future priorities of the Department. A documentary produced by the Media Cell of the CBDT was also screened during the programme.
|
Shri Ravi Agrawal, Chairman, CBDT, held open and interactive discussions with senior officers on the future direction and functioning of the Department and emphasized the need for an actionable roadmap based on the suggestions received. Detailed discussions were also held on infrastructure requirements and essential facilities for Income Tax offices across the country.
|
The programme was organized under the guidance of Shri Ravi Agrawal, Chairman, CBDT, and under the leadership of Shri Sumeet Kumar, Principal Chief Commissioner of Income Tax, Rajasthan. Shri Anil Kumar Bhardwaj, Commissioner of Income Tax (Administration & TPS), Jaipur; Shri Gautam Singh Chaudhary, Additional Commissioner of Income Tax (Administration); Shri Surendra Yadav, Deputy Commissioner of Income Tax (Headquarters); and other officers and staff made significant contributions towards the successful conduct of the conclave.
|
At the conclusion of the programme, Ms. G. Aparna Rao, Member (TPS&R), CBDT, delivered the valedictory address. Shri Anil Kumar Bhardwaj, Commissioner of Income Tax (Administration & TPS), Jaipur, thereafter extended a vote of thanks to the Chairman, CBDT, Members of the Board, senior officers and all officers and staff associated with the successful organization of the conclave.
|
The conclave concluded on a positive and forward-looking note, with a shared commitment to translating the deliberations and suggestions into concrete action towards strengthening the Department and enhancing taxpayer services.
|
|
|
|
|
|
|
|
GSTN Advisory no. 672 dated 19.09.2026
|
This is an advance information to the all users – Taxpayers and Tax Officers, of GST System who use Digital Certificate Signature on the GST Portal.
|
A new version of emSigner (v3.3) is being made available for download for the purpose of providing compatibility with tokens (USB dongles) that are issued on or after 21-September-2026.
|
A. Users with valid certificates: There is no change for the users having existing valid digital certificates and their existing token (USB Dongle) are working, as of 21-Sep-2026. If your existing DSC works normally, you may continue using your current emSigner version.
|
If you encounter signing failures or if your certificate does not appear for selection despite correctly installed token drivers, upgrade to the emSigner version 3.3 by following steps given under point-B below. The emSigner version 3.3 is backward compatible to support the existing tokens (USB dongles).
|
B. Users with newly issued tokens: The users who have been issued a new token (USB Dongle) on or after 21-Sep-2026, either due to issuance of new certificate and dongle, or renewal of certificate in a new dongle, shall have to upgrade to version 3.3 of emSigner by following below steps:
|
Step-1. Please ensure that your system – desktop / laptop / AIO which on which the DSC is used for the GST System, meets the following minimum system requirements:
|
1.1 Operating system and hardware
|
Step-2.Download & install the version 3.3 of emSigner from the GST Portal by navigating to https://www.gst.gov.in/help/docsigner - the older versions of emSigner will not work for such new DSC dongles issued from 21 September 2026 onwards.
|
C. Validity and future renewal: Under CCA’s advisory, DSCs downloaded onto FIPS 140-2 dongles on or before 21 September 2026 can continue to be used until the DSC expires. That date does not automatically invalidate existing DSCs. Subsequent renewal or fresh issuance generally requires a FIPS 140-3 dongle, subject to CCA’s specified exceptions. The CCA migration advisory may be referred for more details on this aspect by navigating to https://cca.gov.in/sites/files/pdf/news/Advisory_on_Migration_from_FIPS_140- 2_to_FIPS_140-3.pdf
|
Please create a ticket on the GST Helpdesk if you need any assistance while upgrading to the emSigner version 3.3 and our teams shall get in touch for resolution.
|
|
|
|
|
|
|
|
GSTN is taking downtime to enhance its services on the GST Portal on 18.09.2026 from 12:00 AM onwards until 2:00 am of 18.09.2026.
|
|
We shall be enhancing services on the GST portal on : 18th Sept’26 12:00 AM onwards. GST Portal services will not be available until 18th Sept’26 02:00 AM. The inconvenience caused is regretted.
|
|
|
|
|
|
|
|
|
|
|
GSTN is taking downtime to enhance its services on the GST Portal on 17.09.2026 from 03:00 AM onwards until 4:30 am of 17.09.2026.
|
|
We shall be enhancing services on the GST portal on : 17th Sept’26 03:00 AM onwards. GST Portal services will not be available until 17th Sept’26 04:30 AM. The inconvenience caused is regretted.
|
|
|
|
|
|
|
|
|
|
|
GSTN is taking downtime to enhance its services on the GST Portal on 16.09.2026 from 12:00 AM onwards until 2:00 am of 16.09.2026.
|
|
We shall be enhancing services on the GST portal on : 16th Sept’26 12:00 AM onwards. GST Portal services will not be available until 16th Sept’26 02:00 AM. The inconvenience caused is regretted.
|
|
|
|
|
|
|
|
|
|
|
GSTN is taking downtime to enhance its services on the GST Portal on 12.09.2026 from 01:30 AM onwards until 3:30 am of 12.09.2026.
|
|
We shall be enhancing services on the GST portal on : 12th Sept’26 1:30 AM onwards. GST Portal services will not be available until 12th Sept’26 03:30 AM. The inconvenience caused is regretted.
|
|
|
|
|
|
|
|
|
|
|
GSTN Advisory no. 671 dated 07.09.2026
|
In cases where a dispute regarding liability exists but the demand amount is reflected as "NIL" or "Zero" in the demand order, and payment has been made by the taxpayer prior to the issuance of the demand order, the previous validation restricting the filing of an appeal against such demand orders has been removed from the GST Portal. Accordingly, taxpayers are now enabled to file an appeal in Form GST APL-01 against demand orders reflecting a NIL or Zero demand amount.
|
Taxpayers facing the above issue may now file an appeal in Form GST APL-01 against such demand orders.
|
In case of any query or difficulty while filing the appeal, taxpayers may raise a ticket with the GST Helpdesk for assistance.
|
|
|
|
|
|
|
|
GSTN is taking downtime to enhance its services on the GST Portal on 04.09.2026 from 12:00 AM onwards until 6:30 am of 04.09.2026.
|
|
We shall be enhancing services on the GST portal on : 4th September’26 12:00 AM onwards. GST Portal services will not be available until 4th September’26 06:30 AM. The inconvenience caused is regretted.
|
|
|
|
|
|
|
|
|
|
|
GSTN Advisory no. 670 dated 01.09.2026
|
Please click on the link below to view the gross and net GST revenue collections for the month of August, 2026.
|
|
|
|
|
|
CBDT has issued Notification No. 114/2026 dated 14.08.2026, notifying the rules and prescribed forms under the Foreign Assets of Small Taxpayers Disclosure Scheme, 2026.
|
|
|
|
|
|
|
|
The Income Tax e-Filing Portal has enabled a dedicated grievance facility for taxpayers to report complaints relating to corruption, misbehaviour, harassment and sexual harassment.
|
Under the grievance mechanism, complainants can select the relevant category and provide details including the name and designation of the officer concerned, along with a description of the grievance. The portal specifically provides categories for “Corruption” and “Mis-behaviour/harassment/sexual harassment.”
|
The facility is expected to strengthen transparency, accountability and taxpayer grievance redressal by providing an online mechanism for reporting serious complaints relating to official conduct.
|
|
|
|
|
|
|
|
Author: Mr. B. Venkateswaran IRS., Assistant Commissioner Central GST, (Retired)
|
The Central Board of Indirect Taxes and Customs (CBIC) has introduced Rule 47A via Notification No. 20/2024 – Central Tax, which will come into effect from November 1, 2024. This new rule introduces a 30-day time limit for issuing tax invoices in cases where recipients are liable to pay tax under the Reverse Charge Mechanism (RCM).
|
Key Provisions of Rule 47A
- If a registered person is required to issue a tax invoice under Section 31(3)(f) of the CGST Act, i.e., when the tax liability is on the recipient under Section 9(3) or 9(4) of the CGST Act, the invoice must be issued within 30 days from the receipt of goods or services.
- Rule 47A applies to transactions where the supplier is unregistered or where RCM applies (such as services provided by advocates or goods purchased from unregistered suppliers).
Non-compliance Consequences:
- If the 30-day timeline is not adhered to, businesses may face interest and penalties for non-compliance.
Explanation of Relevant Sections of the CGST Act, 2017
- Section 31(3)(f) – Requirement to Issue Self-Invoice in RCM Cases:
- This section mandates that when a registered recipient of goods or services is liable to pay tax under the Reverse Charge Mechanism (RCM), the recipient must issue a self-invoice.
- Section 9(3) – Reverse Charge on Notified Goods and Services:
- This section provides for Reverse Charge Mechanism (RCM) on specific categories of goods and services, which are notified by the government.
- In these cases, the recipient of the goods or services is liable to pay GST instead of the supplier. Examples include:
- Legal services from advocates
- Services provided by transportation agencies
- Purchase of certain goods such as cashew nuts from agriculturists
- Section 9(4) – Reverse Charge on Purchases from Unregistered Persons:
- This section applies when a registered person purchases goods or services from an unregistered supplier.
- In such cases, the registered recipient must pay GST under RCM and generate a self-invoice to record the transaction and pay the applicable tax.
- Section 13 – Time of Supply for Services under RCM:
- Section 13(3) specifies that the time of supply for services under RCM will be the earlier of:
- The date of payment (recorded in the recipient’s books or when debited in the bank)
- 60 days from the invoice date (if issued by the supplier)
- The date of issuing the self-invoice (if applicable)
List of services under the Reverse Charge Mechanism (RCM) in GST as of October 2024:
- Goods Transport Agency (GTA): Transport of goods by road from a GTA to various entities such as factories, societies, and partnership firms (except government departments registered for tax deduction only).
- Legal Services: Services by individual advocates or law firms to business entities, including representational services.
- Arbitral Tribunal Services: Services provided by arbitral tribunals to businesses.
- Sponsorship Services: Sponsorships given to corporate bodies or partnership firms.
- Director’s Services (Non-remunerative): Services provided by directors to the company or corporate body.
- Insurance and Recovery Agent Services:
- Insurance agent services to insurance businesses.
- Recovery agent services to financial institutions, including banks and NBFCs.
- Government Services to Business Entities: Services (excluding postal, passenger, and goods transport services) offered by central or state governments to businesses. Rental services of immovable property by the government are also under RCM.
- Transfer of Development Rights and Long-Term Lease:
- Transfer of Floor Space Index (FSI) and development rights to promoters.
- Long-term lease of land (30 years or more) for construction projects by promoters.
- Copyright Services: Transfer of copyrights by artists, authors, composers, and photographers to publishers, producers, or music companies.
- Direct Selling Agents (DSAs): Services provided by individual DSAs to banks or NBFCs.
- Business Facilitator and Correspondent Services:
- Services by business facilitators to banks.
- Agents of business correspondents offering services to correspondents.
- Security Services: Security personnel services provided to registered persons, with certain exclusions for government entities.
- Motor Vehicle Rental: Rental of motor vehicles with fuel costs included, supplied by non-corporate entities to corporate bodies.
- Securities Lending: Lending of securities under the SEBI Securities Lending Scheme to borrowers through intermediaries.
- Recent Addition: Rental of immovable property (excluding residential dwellings) by unregistered persons to registered entities from October 10, 2024
Sample Format for Self-Invoice under RCM
|
Self-Invoice
(Issued as per Rule 36(1) of the CGST Rules, 2017)
|
Invoice No.: ………………..
Date: ………..
|
Supplier Name: Unregistered Supplier
Address:
GSTIN: Not Applicable
|
Reverse Charge Applicable: Yes
|
Recipient Name:
Recipient Address:
GSTIN:
|
Total Invoice Value: …………………
|
Declaration:
This invoice has been generated by the recipient under Section 31(3)(f) of the CGST Act, 2017, as the supplier is not registered under GST, and the tax liability has been discharged under RCM.
|
Signature of the Authorised person.
|
|
|
|
|
|
Yes, the Honorable Madras High Court in the case of P S K Engineering Construction & Co. v. Assistant Commissioner of GST & Central Excise held that there is no restriction in statute for Central GST authorities to initiate proceedings on different subject matter that it is already adjudicated by State Authorities. The Honorable Madras High Court noted that on perusal of the Impugned Notice, it is clear that such notice was issued while being fully aware of Section 6(2)(b) of the CGST Act. However, there is no restriction to initiate any proceedings on any other subject matter by the Central Tax Authority. Accordingly, the officer intended to conduct an audit under the provisions of section 65 of the CGST Act. The Honorable Court held that the subject matter of the audit was not the same subject matter as proceedings initiated by the State GST authorities, there is no restriction in the statute. Therefore, the writ petition was disposed of by leaving it open to the petitioner to respond to the Impugned Notice.
|
As per Section 6(2)(b) of the CGST Act, if a proper officer under the SGST Act or the UTGST Act has initiated any proceedings on a subject matter, no proceedings shall be initiated by the proper officer under the CGST Act on the same subject matter. In the considered opinion of the Author, there is no bar under the law that once a proceeding is initiated for a particular period by the CGST department, no proceedings can be issued by the SGST or UTGST authorities or vice versa for the same period. The only bar that the statute places is regarding proceedings based on the same cause-of-action and the same subject matter (in a few circumstances, even for the same cause-of-action, parallel proceedings are permissible). Section 6(2)(b) of the Act comes into play only when overlapping SCN is issued for the same subject matter for the same period. Important to highlight that the cross-empowerment is allowed for proceedings carried out under section 67 of the Act only.
|
|
|
|
|
|
No, the Honorable Himachal Pradesh High Court in the case of M/s. Microtek Himachal Power Products (P.) Ltd. v. State of Himachal Pradesh disposed the writ petition and directed that the erroneous order passed with the wrong description be treated as Show Cause Notice and be further adjudicated upon after the filing of reply to the deemed SCN.
|
The Honorable court noted that the order dated June 20, 2023 is issued in Form GST DRC-01 passed under Section 74(9) of the Central Goods and Services Act and it is contented that no prior SCN has been issued before the passing of the Impugned order mandated under Section 74(1) of the CGST Act and thereby the Impugned Order passed is in violation of principles of natural justice. The Honorable Court noted that the Revenue Department contended that there has been an error on the part of the Respondent officer, as the portion of the SCN has been mentioned as if there is the determination of tax, interest, and penalty.
|
The Honorable High Court accepted the submissions made by the Respondent and directed that the Impugned Order shall be treated as SCN issued to the Petitioner. Further, the Honorable High Court directed petitioner to file the reply to the deemed SCN within the period of four weeks.
|
Approaching a writ court under Article 226 or Article 32 of the Constitution of India must be a strategic and well-thought decision. If the Honorable Court remands back the case for the second round of adjudication and the notice is not vacated, then it turns out to be a fruitless exercise unable to fetch the desired relief.
|
It is not always that suffering an ex-parte order will be disastrous. Most of the times, ex parte orders without a reply by taxpayers, are not sustainable on facts and law. Moreover, every mistake of the Revenue cannot become ground to vacate notice and achieve the desired outcome. In the instant case, the petitioner could have disputed the adverse order because “Due Process” of law demands, (i) pre-notice consultations in DRC-01A conducted and concluded; (ii) notice served; (iii) reply received; (iv) personal hearing conducted and concluded; and (v) adjudication completed by passing speaking order. Any departure from ‘due process’ in law causes prejudice to the taxpayer’s rights, remedies and safeguards. And this itself can be a ground to fetch the desired relief in appeal or judicial review. Passion to protect the interest of revenue does not authorize the by-passing of the law.
|
|
|
|
|
|
4. Lawgics by Ms.Nidhi Aggarwal
|
Ms. Nidhi Aggarwal is delighted to present judgment with a great vision to spread complex GST law in a simple manner amongst the taxpayers, tax professionals, students and knowledge seeker.
|
|
Recently added notes are listed below:
|
|
|
|
|
|
Synopsis: The Delhi High Court dismissed the writ petition involving fraudulent ITC claims, directing the petitioner to pursue appellate remedy u/s 107 of the CGST Act.
|
Caste name: Banson Enterprises & Anr. vs Assistant Commissioner CGST & Ors.
|
Citation: W.P. (C) 6503/2025 dated 15.05.2025
|
Authority: Delhi High Court
|
The petition challenges the Order-in-Original dated 02.02.2025 based on a Show Cause Notice (SCN) dated 03.08.2024 A search was conducted, and statements were recorded including that of one Director admitting to the issuance of fake invoices during the Central Excise period. It was alleged that the Petitioner issued goods-less invoices to enable fraudulent Input Tax Credit (ITC) claims amounting to Rs. 1.85 crore.
|
Contentions of the Petitioner:
|
SCN was issued by unauthorized officer, thus, violates Rule 142(1)(a) of CGST Rules. No pre-consultation as required under Rule 142(1A) of CGST Rules was issued. Consolidated SCN for multiple financial years was issued and challenge to such consolidated action is pending in a separate matter (Quest Infotech case).
|
Contentions of the Department:
The impugned order is appealable, hence writ is not maintainable. The Petitioner’s Director admitted to allegations. Natural justice was followed as the Petitioner received the SCN, filed a reply, and availed of personal hearing. Reliance must be made on SC judgments and Allahabad HC rulings emphasizing alternate remedy u/s 107 CGST Act.
|
Findings and Decision of the Court:
The Court refused to interfere under writ jurisdiction, citing:
|
- No breach of fundamental rights or principles of natural justice.
- Availability of a statutory remedy (appeal) under Section 107 CGST Act.
The Court noted that the Allegations involve serious misuse of ITC, requiring fact-based adjudication, not suited for writ jurisdiction. Thus, the Petitioner was granted liberty to file appeal, and if filed with pre deposit, the appeal shall not be dismissed on limitation.
|
|
|
|
|
|
5. GST Notes by CMA Anil Sharma
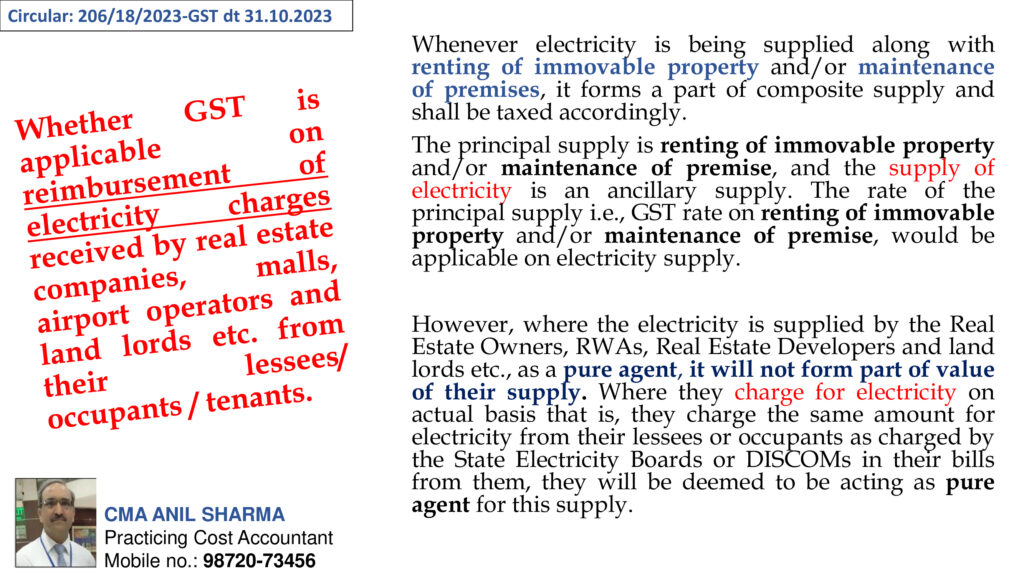
1) New slides on GST Circulars is added in the Notes section titled as "Capsules".
|
- Total 25 slides in capsule-01 is added
|
|
|
|
|
|
|
|
6. GST Daily by CA Pradeep Modi
CA Pradeep Modi is presenting judgment analysis under title 'GST Daily - Stay yourself updated'
|
|
|
|
|
|
|
Recap of Latest updates posted on 27.08.2026
|
CBIC issued Notification No. 30/2026-Customs dated 21.08.2026 regarding Seeks to exempt 10 lakh MT of raw sugar falling under tariff heading 1701 from the whole of the customs duty leviable thereon under …
|
GSTN is taking downtime to enhance its services on the GST Portal on 26.08.2026 from 12:00 AM onwards until 6:30 am of 26.08.2026.
|
The Hon’ble Supreme Court in M/s G.R. Infra Projects Limited set aside the Show Cause Notice dated June 13, 2025 issued under Section 74 of the CGST Act read with the MPGST Act for the FY 2018-19, and held that a bland and mechanical recital of the words ‘fraud or concealment of facts’,
|
Indian Railway Finance Corporation Ltd received a show cause notice from the GST Authority demanding ₹549.32 crore. The notice, issued under Section 73 of the Central Goods and Services Tax Act, 2017, cites excess input tax credit claims for FY23.
|
The Anti-Corruption Bureau (ACB) on Monday arrested a state tax officer and a senior assistant in Nirmal district for demanding and accepting a bribe of ₹50,000 in connection with a GST audit.
|
CBIC issued Notification No. 71/2026-Customs (N.T.) dated 25.08.2026 regarding Fixation of Tariff Value of Edible Oils, Brass Scrap, Areca Nut, Gold and Silver
|
CBIC issued Notification no. 21/2026-Customs (ADD) dated 21.08.2026 that Seeks to continue applicability of anti-dumping duty on imports of Natural Mica based Pearl Industrial Pigments ..
|
CBDT issued notification no. 115/2026 dated 21.08.2026 to hereby approves deduction under section 45(3)(a)(i) of the Income tax Act, 2025 to the International Institute of Bio Technology and Toxicology , Tamil Nadu for Scientific Research
|
I request the views of tax professionals and TDS experts on the following issue under the Income-tax Act, 2025, regarding reporting in Form 140.
|
|
|
|
|
|
7. PPT/Handbook on GST
|
|
|
|
8. GST/Income Tax in Media
|
|
|
- ₹5.55 Crore GST Credit Under Scanner, Pharma Company MD Arrested
- GST Fraud: Partner Arrested for Rs 15.78 Cr ITC Claims
- Central GST officer caught accepting bribe in Bengaluru
- 170 vehicles detained, goods worth Rs 5 cr seized: Cheema
- Telangana tax dept holds officers personally accountable for unauthorised AI sharing of taxpayer data
- Tax department turns to AI for sharper scrutiny, compliance
- CBI Catches CGST Superintendent and Consultant Red-Handed in ₹1 Crore Bribery Trap Over New Panvel Flat Redevelopment
- Tax officials barred from sharing taxpayer data with AI tools
- Sirmaur pharma company MD held in Rs 6.55 crore GST refund fraud case
- West Bengal AAR says actual-cost electricity recovery not liable to GST
- Haryana: GST officer, CA held red-handed taking ₹3 lakh bribe
- HDFC Life Insurance faces ₹3,365 crore GST tax demand and penalty after appeal order
- GST data to track Andhra Pradesh’s economic growth live
- Gujarat Assembly passes GST amendment, livestock feed regulation bills
- SBI to use UPI data to lend to small businesses without GST registration
- IAMAI wants 5% GST dropped for app-based rides
- Rajasthan govt seizes 44 vehicles in 3 weeks in tax evasion crackdown
- States reject Gauba panel's push for single, nationwide GST registration
- Maruti sees strong growth as GST 2.0 pushes more customers to upgrade to cars, says Partho Banerjee
- Credai-Gujarat seeks GST clarity on FSI purchases
- Tata Steel gets major Supreme Court relief in ₹890 crore GST dispute
- TN Govt earns ₹50,845 crore from sales tax and excise revenue in liquor, aims for revenue expansion and de-addiction initiatives
- Despite GST Council’s no, legislators in UP, other states want Vidhayak Nidhi outside tax net
|
|
|
|
|
|
|
|
|
GST Litigation Course by OTU:
|
|
onlinetaxupdate.com is conducting a GST Litigation Course with 3 sessions of 2 hours each by Best Industry speaker tentatively in November 2024
|
|
|
|
|
|
|
Hope the above updates is of use to you. Please share your input and feedback at taxupdate.otu@gmail.com
|
|
|
|
|
|
|
|
 
|
Visit our website
|
OTU provides you
|
- Articles on various topics
|
|
- Media - GST, Income Tax & Press R.
|
|
|
|
|
