|
onlinetaxupdate team wish to express sincere thanks to all the readers, authors, subscribers for the support extended to us. Please share your feedback at
|
taxupdate.otu@gmail.com or 7738647904
|
Newsletter 122 dated 10.06.2024
|
|
|
|
|
|
|
|
|
Dear Reader,
|
Please find newsletter for your reading and reference.
|
|
Index of the Newsletter
- Recent updates
- Article
- Lawgics by Ms.Nidhi Aggarwal
- GST Notes by CMA Anil Sharma
- GST Daily by CA Pradeep Modi
- GST/IT/Customs in media
- Latest Update - Recap
|
|
|
|
|
|
|
Haryana Excise & Taxation Department, issued an Instruction via memo no. 1217/GST-II daed 29.11.25 regrading taking up Suo-Moto Cases for Audit/ Scrutiny under the HGST Act, 2017.
|
Your attention is invited to the subject cited above. In this context, it is hereby directed that whenever any suo-moto case is proposed to be taken up for audit or scrutiny, the same shall be submitted with a clear, specific, and duly justified reasons and must also include the tentative quantum of tax evasion on the basis of available records, intelligence inputs, data analysis, or any other verifiable source of information.
|
Further, it is mandated that every such proposal for initiating suo-moto audit/scrutiny shall first be examined and recommended by the Deputy Excise and Taxation Commissioner (DETC) concerned and after the DETC's recommendations, the case file shall be forwarded to the Joint Excise and Taxation Commissioner (Range) for obtaining the necessary approval.
|
All field formations shall ensure strict compliance with these instructions. Any initiation of suo-moto action without adherence to the above-mentioned procedure shall be viewed seriously.
|
This issues with the approval of the competent authority.
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Instruction no. 17/2026-Customs dated 21.09.2026 giving Clarification in respect of difficulties being faced by field formations in adjudication of cases where Show Cause Notices have been issued under Section 28AAA of the Customs Act, 1962 in light of TRU instruction vide D.O. letter dated 01.06.2012 at para II.2
|
|
|
|
|
|
Central Board of Indirect Taxes and Customs (CBIC) issued Circular no. 41/2026-Customs dated 03.09.2026 regarding National Assessment Centre (NAC) Portal for Trade and department for effective dissemination of information
|
|
|
|
|
|
CBIC issued Notification No. 75 /2026-Customs (N.T.) dated 15.09.2026 regarding Fixation of Tariff Value of Edible Oils, Brass Scrap, Areca Nut, Gold and Silver
|
|
|
|
|
|
|
|
CBIC issued Notification No. 74 /2026-Customs (N.T.) dated 01.09.2026 regarding Appointment of Common Adjudicating Authority in the case of M/s. Akwel Automative Pune India Pvt. Ltd. (IEC: 3105015850) – Consolidated Adjudication of Multiple Show Cause Notices arising from SVB Investigation Report No. 198/AC/SVB/SKB/2022-23 dated 20.12.2022
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Trade Notice 28/2026-27 dated 16.09.2026 regarding Revision in Timeline for Issuance of PSIC and One-time Relaxation for Issuance of Backlog PSICs
|
Kind attention is invited to earlier Trade Notice No. 22/2026-27 dated 25.08.2026 regarding enhancements in the Pre-Shipment Inspection Agency (PSIA)/Pre Shipment Inspection Certificate (PSIC) process.
|
2. In order to facilitate smooth implementation of the revised PSIA/PSIC module, the following relaxations are hereby made to the provisions contained in the aforesaid Trade Notice:
|
i. One-time transitional arrangement for issuance of PSICs
|
A one-time relaxation of seven days from the date of issuance of this trade notice is hereby provided to the recognized PSIAs for clearing the backlog PSICs pertaining to inspections conducted prior to 25.08.2026, where such certificates could not be issued due to system restrictions introduced pursuant to the aforesaid Trade Notice.
|
ii. Revision in timeline for issuance of PSIC
|
Para 2(ii) of Trade Notice No. 22/2026-27 dated 25.08.2026 shall stand substituted with the following:
|
"The PSIC shall be generated and issued within 2 days from the date of inspection. The system shall permit generation and issuance of the PSIC only within the prescribed timeline. The PSIC uploading shall be done from the same geographical location/country where inspection is carried out."
|
3. All other provisions of Trade Notice No. 22/2026-27 dated 25.08.2026 shall remain unchanged.
|
This issues with the approval of the DG, DGFT.
|
|
|
|
|
|
|
|
The Directorate of Revenue Intelligence (DRI) seized more than 362 metric tonnes of Pakistan-origin dry dates under 'Operation Deep Manifest' during an enforcement drive targeting illicit trade conduits.
|
Acting on specific actionable intelligence, operational teams intercepted 13 cargo containers carrying the consignments at CFS Ahmad in Nashik , which a Mumbai-based commercial entity imported.
|
According to the Ministry of Finance, the shipments arrived via Jebel Ali in the United Arab Emirates, accompanied by import clearance paperwork that falsely declared the UAE as the sovereign country of origin.
|
Official findings revealed that the commercial consignment moved through a deliberate routing network designed to mask its true origin. The cargo started its maritime transit from Karachi Port in Pakistan, reaching Jebel Ali Port in the UAE abroad an initial vessel.
|
"Preliminary investigation revealed a carefully orchestrated transshipment arrangement designed to conceal the Pakistan-origin of the goods," the Ministry stated.
|
The operational breakdown showed that the illicit cargo underwent minimal physical handling in the Gulf transit hub to obscure the paper trail.
|
"The dry dates were initially shipped from Karachi Port, Pakistan, to Jebel Ali Port, UAE, in one set of containers aboard one vessel," the official statement noted.
|
Handlers in the transit zone then re-routed the shipment onto another carrier line, it state.
|
"At Jebel Ali, the goods were merely transshipped and transferred to another set of containers and loaded onto a different vessel for onward shipment to India through entities operated by Pakistani nationals," the Ministry confirmed.
|
Border and port enforcement tightened following regulatory revisions enacted by the Directorate General of Foreign Trade (DGFT) in mid-2025.
|
The Ministry mentioned that following the Pahalgam terror attack, the Government of India, in the interest of national security, imposed a complete prohibition on the direct or indirect import or transit of all goods originating in or exported from Pakistan, with effect from 02.05.2025, vide DGFT notification no. 06/2025-26 dated 02.05.2025.
|
To counter non-compliant import tactics across container terminals, central enforcement authorities launched structured surveillance protocols targeting third-party trade jurisdications.
|
"In response, DRI, under 'Operation Deep Menifest", has been consistently identifying, intercepting and seizing Pakistan-origin goods attempted to be imported into India through third-country routing," the Ministry said.
|
Customs and intelligence officials continue to track intermediate entities connected to commercial paper falsification, fraudulent routing manifests, and proxy transshipment nodes.
|
"The seizure underscores (DRI's sustained resolve to identify, disrupt and dismantle sophisticated networks seeking to circumvent trader prohibitions through misdeclaration , transshipment and manipulation of documentation, thereby safeguard national security and straightening supply chain integrity," the Ministry added.
|
|
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Notification No. 36/2026-27 dated 15.09.2026 regarding De minimis exemption from Registration-cum-Membership Certificate (RCMC) requirements for low-value exports
|
|
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Public Notice 30/2026-27 dated 14.09.2026 regarding Extension of timeline for surrender of unutilised TRQ quantity allocated for import of 10 Lakh MT of Raw Sugar
|
|
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Trade Notice 27/2026-27 dated 14.09.2026 Inviting comments/suggestions on Amendment in Para 2.93 of the Handbook of Procedures, 2023 – Rules of Origin (Non-Preferential).
|
|
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Trade Notice 26/2026-27 dated 07.09.2026 regarding Comments/views on proposed suspension of 544 Standard Input Output Norms (SIONs) remaining unutilized during the last three financial years
|
|
|
|
|
|
|
|
Directorate General of Foreign Trade (DGFT) issued Trade Notice 25/2026-27 dated 07.09.2026 regarding Introduction of Open API Integration for Certificate of Origin (CoO) through Trade Connect e-Platform
|
|
|
|
|
|
GSTN Advisory no. 672 dated 19.09.2026
|
This is an advance information to the all users – Taxpayers and Tax Officers, of GST System who use Digital Certificate Signature on the GST Portal.
|
A new version of emSigner (v3.3) is being made available for download for the purpose of providing compatibility with tokens (USB dongles) that are issued on or after 21-September-2026.
|
A. Users with valid certificates: There is no change for the users having existing valid digital certificates and their existing token (USB Dongle) are working, as of 21-Sep-2026. If your existing DSC works normally, you may continue using your current emSigner version.
|
If you encounter signing failures or if your certificate does not appear for selection despite correctly installed token drivers, upgrade to the emSigner version 3.3 by following steps given under point-B below. The emSigner version 3.3 is backward compatible to support the existing tokens (USB dongles).
|
B. Users with newly issued tokens: The users who have been issued a new token (USB Dongle) on or after 21-Sep-2026, either due to issuance of new certificate and dongle, or renewal of certificate in a new dongle, shall have to upgrade to version 3.3 of emSigner by following below steps:
|
Step-1. Please ensure that your system – desktop / laptop / AIO which on which the DSC is used for the GST System, meets the following minimum system requirements:
|
1.1 Operating system and hardware
|
Step-2.Download & install the version 3.3 of emSigner from the GST Portal by navigating to https://www.gst.gov.in/help/docsigner - the older versions of emSigner will not work for such new DSC dongles issued from 21 September 2026 onwards.
|
C. Validity and future renewal: Under CCA’s advisory, DSCs downloaded onto FIPS 140-2 dongles on or before 21 September 2026 can continue to be used until the DSC expires. That date does not automatically invalidate existing DSCs. Subsequent renewal or fresh issuance generally requires a FIPS 140-3 dongle, subject to CCA’s specified exceptions. The CCA migration advisory may be referred for more details on this aspect by navigating to https://cca.gov.in/sites/files/pdf/news/Advisory_on_Migration_from_FIPS_140- 2_to_FIPS_140-3.pdf
|
Please create a ticket on the GST Helpdesk if you need any assistance while upgrading to the emSigner version 3.3 and our teams shall get in touch for resolution.
|
|
|
|
|
|
|
|
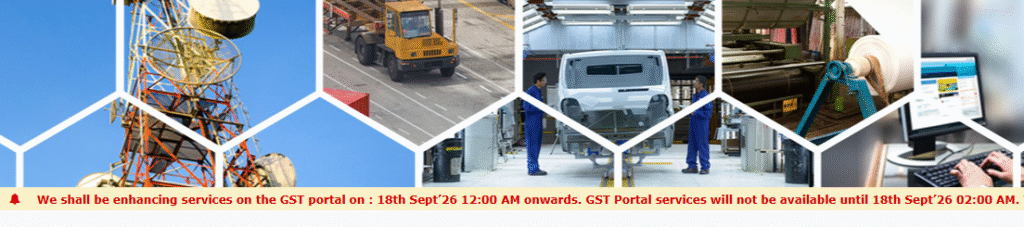
GSTN is taking downtime to enhance its services on the GST Portal on 18.09.2026 from 12:00 AM onwards until 2:00 am of 18.09.2026.
|
|
We shall be enhancing services on the GST portal on : 18th Sept’26 12:00 AM onwards. GST Portal services will not be available until 18th Sept’26 02:00 AM. The inconvenience caused is regretted.
|
|
|
|
|
|
|
|
|
|
|
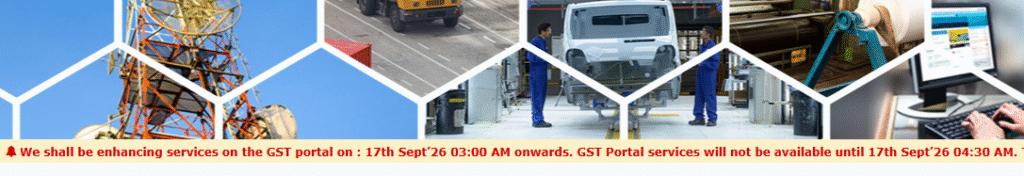
GSTN is taking downtime to enhance its services on the GST Portal on 17.09.2026 from 03:00 AM onwards until 4:30 am of 17.09.2026.
|
|
We shall be enhancing services on the GST portal on : 17th Sept’26 03:00 AM onwards. GST Portal services will not be available until 17th Sept’26 04:30 AM. The inconvenience caused is regretted.
|
|
|
|
|
|
|
|
|
|
|
GSTN is taking downtime to enhance its services on the GST Portal on 16.09.2026 from 12:00 AM onwards until 2:00 am of 16.09.2026.
|
|
We shall be enhancing services on the GST portal on : 16th Sept’26 12:00 AM onwards. GST Portal services will not be available until 16th Sept’26 02:00 AM. The inconvenience caused is regretted.
|
|
|
|
|
|
|
|
|
|
|
GSTN is taking downtime to enhance its services on the GST Portal on 12.09.2026 from 01:30 AM onwards until 3:30 am of 12.09.2026.
|
|
We shall be enhancing services on the GST portal on : 12th Sept’26 1:30 AM onwards. GST Portal services will not be available until 12th Sept’26 03:30 AM. The inconvenience caused is regretted.
|
|
|
|
|
|
|
|
|
Central Board of Direct Taxes (CBDT) issued notification no. 120/2026 dated 17.09.2026 to hereby make following rules further to amend the Income tax Rules, 2026 , namely -
|
These rules may be called the Income-tax (Fourth Amendment) Rules, 2026
|
|
|
|
|
|
|
|
Directorate of Income Tax (Systems) of Central Board of Direct Taxes (CBDT) issued notification no. 3/2026 dated 15.09.2026 to prescribe Procedure for registration of reporting person/entity and submission of Form No. 98 as per rule 160 of the Income tax Rules, 2026.
|
Rule 160 of the Income-tax Rules, 2026 (hereinafter, "the Rules") specifies that every person referred to in clauses (a) and (b) of sub-rule (2), who has received any declaration in Form No. 97 in relation to a transaction specified in column 2 of Table in rule 159, shall furnish a statement in Form No. 98.
|
2. As per rule 160, the statement in Form No. 98 shall be furnished through online transmission of electronic data to a server designated for this purpose. As per sub-rule 3 of rule 160, the statement in Form No. 98 shall:
|
(a) where the declarations are received by the 30th September, be furnished by the 31st
October of that year; and
|
(b) where the declarations are received by the 31st March, be furnished by the 30th April
of the financial year immediately following the financial year in which the form is
received.
|
3. In exercise of the powers under rule 332 of the Income-tax Rules, 2026, the Director General of lncome-tax (Systems) hereby lays down the following procedure:.
|
(a) Registration and Generation of Income Tax Department Reporting Entity Identification Number (ITDREIN): The reporting person/entity is required to get registered with the Income Tax Department by logging in to the e-filing website (https://eportal.incometax.gov.in) with the log-in ID used for the purpose of filing the Income Tax Return of the reporting person/entity. The reporting person/entity needs to click on "Reporting Portal" link under "Pending Actions" tab at e-filing portal to access "Reporting Portal" for first time registration. The reporting person/entity will mandatorily be required to enter the details of form type, category and address of reporting person/entity along with the details of the principal officer.
|
On successful submission, the ITDREIN is generated and the principal officer will receive a confirmation e-mail on his/her registered e-mail address and SMS at his/her registered mobile number. There will be no option to deactivate ITDREIN, once it is generated.
|
The reporting person/entity already registered for compliance of erstwhile Form No: 61 are not required to register for Form No. 98 and the existing ITDREIN as well as the respective principal officers shall continue to remain valid. For the purpose of verification of Form No. 98, the principal officer will act as "Designated Director".
|
(b) Submission of Form No. 98: As per rule 160, a statement in Form No. 98 is required to be furnished by the reporting person/entity. The prescribed Schema, Report Generation and Validation Utility for Form No. 98 and Generic Submission Utility can be downloaded from the Reporting Portal under "Resources" tab. The prepared Statement to be filed is required to be digitally signed by and uploaded at the Reporting Portal or through Generic Submission Utility through the login credentials (PAN and password) of the principal officer.
|
(c) Submission of correction statement: In case the reporting person/entity comes to know or discovers any inaccuracy in the information provided in the statement or the defects have been communicated to the reporting person/entity through Data Quality Report (DQR) after submission of Statement, it is required to remove the defects by submitting a correction statement. The number of "Reports Requiring Correction (RRC)" will be visible against the original statement on Reporting Portal. The user can download the DQR file from the DQR column under "Statements" Tab of Reporting Portal, which can then be opened on the Report Generation Utility to find and fix the errors. The reporting person/entity needs to rectify all the defects till the number of "Reports Requiring Correction (RRC)" becomes zero within the specified period.
|
(d) Deletion of Submitted Reports in a statement: In case the reporting person/entity wishes to delete the inadvertently filed reports within a statement, it can choose the statement type as "Deletion Statement" and file all such reports within a single statement to be deleted with exact previously filed values against each field. The manner of filing Deletion Statement shall be similar to submission of correction statement.
|
(e) Security, archival and retrieval policies: The reporting person/entity is required to document and implement appropriate information security policies and procedures with clearly defined roles and responsibilities to ensure security of submitted information and related information/documents. The reporting person/entity is also required to document and implement appropriate archival and retrieval policies and procedures with clearly defined roles and responsibilities to ensure that submitted information and related information/documents are available promptly to the competent authorities.
|
This notification shall come into force with effect from /5~f September 2026. The Reporting for F.Y. 2025-26 and earlier years (including correction/ deletion) will continue as per the provisions of the Income-tax Act, 1961 and the Income-tax Rules, 1962, through Form No. 61 as per Notification No. 2 of 2018 dated 05.04.2018.
|
|
|
|
|
|
CBDT has issued Notification No. 114/2026 dated 14.08.2026, notifying the rules and prescribed forms under the Foreign Assets of Small Taxpayers Disclosure Scheme, 2026.
|
|
|
|
|
|
|
|
No, the Honorable Calcutta High Court in the case of Pioneer Co-operative Car Parking Servicing and Construction Society Ltd. v. Senior Joint Commissioner disposed of the writ petition holding that the adjournments granted for the notice issued under section 61 cannot be clubbed together with proceedings under Section 73 of the Central Goods and Services Tax Act, 2017. The Honorable Calcutta High Court noted that as per sub-section (5) of Section 75 of the CGST Act, upon sufficient cause shown by the person, the adjournment should be granted by the proper officer and the reasons are to be recorded in writing. However, the adjournment should not be granted more than three times to a person during the proceeding. The Honorable Court opined that the adjournment granted to the Petitioner in relation to the proceedings under Section 61 of the CGST Act cannot be clubbed together with the SCN proceedings and holding that the Petitioner was granted ample opportunity to respond to SCN issued under Section 73(1) of the CGST Act is erroneous. The Honorable Court quashed the recovery notice.
|
Proceedings under section 73 of the CGST Act are completely different and independent of section 61 proceedings. Proceeding under section 61 of the CGST Act is pre-adjudication exercise (where no demand can be confirmed and recovered) and certainly not a pre-condition to initiate proceedings under chapter XV of the CGST Act. Although, the Proper officer to issue a notice under section 61 and 73 of the CGST Act might or might not be the same one, but the adjournments granted during section 61 proceedings cannot be considered as adjournments granted for the purpose of section 71 of the CGST Act.
|
Section 75(5) states that if sufficient cause is shown, the proper officer is empowered to grant maximum of three adjournments to a person during the proceeding. This power must neither be misused not left to fall into disuse. Many instances arise where intervention is warranted but this request may be entertained based on 'sufficient cause'. The Apex Court in case of Esha Bhattacharjee v. MC of Raghunathpur Nafar Academy (2013) 12 SCC 649 has held that reasonableness, practically and fairness must underpin course of disposal of all such requests and applications and extent of condonation allowance must not exceed statutory boundaries even in meritorious facts.
|
|
|
|
|
|
The Hon'ble CESTAT upheld that SCN issued by the department for the recovery of an ***erroneous refund***. This decision came even after the matter was ultimately held in favour of the revenue by the Hon'ble SC, despite the taxpayer having received a favourable ruling from the HC.
|
CESTAT clarified that since the issue had been conclusively determined by the Hon'ble SC, setting aside the judgement of the HC, it could not be argued that there was no case of erroneous refund on the date the SCN was issued.
|
Additionally, the Hon'ble CESTAT emphasized that the principles of Section 14 of the Limitation Act apply to appeal filed by taxpayers before the Commissioner (Appeals) under the Customs Act. Section 14 allows for the exclusion of time during which the taxpayer diligently pursued a remedy before an authority that lacked jurisdiction or for similar reasons.
|
|
|
|
|
|
Author: Mr. Parveen Mahajan
|
The petitioner not furnished the reply. The Court held that failure to avail one opportunity may not lead to denial of the other. The two tests have to be satisfied independently. The court set aside the impugned order without waiting the counter affidavit on the plea that the order impugned has been passed contrary to the mandatory procedure. The deficiency of procedure is self apparent and critical to the out-come of the proceedings.
|
Case - M/s NASIBULLA TIMBER STORE - Allahbad HC
|
|
|
|
|
|
No, the Honorable Madras High Court, in the case of Tvl Future General India Insurance Co. Ltd v. Assistant Commissioner (State Tax) held that an assessment order passed by the Assessing Officer has accepted the explanation of the assessee with regard to certain defects that had imposed GST at the rate of 18% on the ground that the financial statements submitted by the assessee did not reflect state-wise turnover.
|
The Honorable Madras High Court observed that the turnover for an entity operating in multiple states in India as reflected in the financial statements and the turnover attributable to its operations in a particular state (in this case-Tamil Nadu) would vary and the bifurcation of total and state-wise turnover is the only relevant factor, and the Competent Authority erred in imposing GST at rate of 36% instead of the applicable rate of 18%, despite the Petitioner having already paid tax on the turnover of Rs. 80,59,05,068/-
|
The impugned assessment order was to be set aside, and the matter was to be remanded to the Competent Authority for reconsideration.
|
There is an urgent need to understand that the linear comparison of two different data sets in meaningless in GST. Yes, it may raise suspension but no adverse inference can be made regarding non-payment, short-payment or evasion of taxes.
|
In this particular case, Output tax is demanded citing data differences without stating (i) the nature of supply (ii) the taxability of the same (iii) the HSN code (iv) the time of supply, and (v) the place of supply. Without these taxing ingredients, any demand for output tax is arbitrary and illegal.
|
This principle has been laid by the Honorable Apex Court in the case of Govind Saran Ganga Saran v. CST & Ors. AIR 1985 SC 1041, where it was held that 'four ingredients' are required to be present in any proceedings to demand tax.
|
|
|
|
|
|
No, the Honorable Allahabad Hight Court in the case of Mansoori Enterprises v. Union of India held that as per Circular No. 31/05/2018-GST dated 09.02.2018, power of the Superintendent, Central Goods and Service Tax & Central Excise is limited to the matter not exceeding Rs. 10,00,000/- and in the present case the amount involved is more than Rs. 16,00,000/- and consequently, the order passed by the Superintendent is without jurisdiction. Hence, the said order was declared without jurisdiction and liable to be set aside.
|
The Honorable Allahabad High Court observed that the Superintendent lacked jurisdiction to issue the impugned Order since the amount involved exceeded the limits set in Circular No. 31/05/2018-GST dated 09.02.2018. The Honourable Court held that the impugned order was liable to be quashed, also the Court granted liberty to the Respondent to initiate fresh proceedings by the law.
|
In this statute, there is a 'Proper Officer' for every section and every action under the law. The officer who is empowered to grant registration is not the Proper officer to do audit (most likely), those who can come for audit, cannot come for proceedings under section 67 of the Act. The Proper officer who can do audit and inspection cannot be a Proper officer to adjudicate. Just because statutory duties are being performed, even if there is strong suspicion of revenue leakage, except by following the due process of invoking specific powers conferred within specific boundaries of the law, these proceedings are in as much illegal. The Law of administration states that what power is given to be a particular thing, that thing must be done in that particular manner or not at all.
|
Taxpayers before replying to any proceedings, "Validity of Jurisdiction" must be tested and confirmed. And if there is any doubt, the Proper Officer must explain the exercise of jurisdiction when validity of notice is questioned is view of the mandate in section 160(2) of the Act.
|
|
|
|
|
|
In case of Inter state movement of Goods for Job work, then E-way bill is required in all cases, irrespective of any value.
|
It is observed that there is general understanding that E way bill is not required for inter statement if value is less than Rs 50,000/-. However this is not applicable for Inter statement movement of goods for Job work as per 3rd proviso to Rule 138(1) of CGST Rules.
|
Legal provision in this regards is reproduced below for ready reference –
|
- “Provided also that where goods are sent by a principal located in one State or Union territory to a job worker located in any other State or Union territory, the e-way bill shall be generated either by the principal or the job worker, if registered, irrespective of the value of the consignment”
|
|
|
|
|
|
The attached communication is relevant, as it appears to concede that the profit margin of the third party (and other recoveries involved in preparing the product for export from the origin) will not be a relevant factor for computing the AIFTA content or the value addition.
|
|
The communication clarifies that even in the case of third-party invoicing, the value addition should be calculated based on the FOB (Free on Board) value stated in the commercial invoice issued by the manufacturer, supplier, or consignor from an AIFTA member state. The third party invoice price may not be relevant for VA.
|
|

|
|
|
|
|
3. Lawgics by Ms.Nidhi Aggarwal
|
Ms. Nidhi Aggarwal is delighted to present judgment with a great vision to spread complex GST law in a simple manner amongst the taxpayers, tax professionals, students and knowledge seeker.
|
|
Recently added notes are listed below:
|
|
|
|
|
|
Synopsis: The Delhi High Court dismissed the writ petition involving fraudulent ITC claims, directing the petitioner to pursue appellate remedy u/s 107 of the CGST Act.
|
Caste name: Banson Enterprises & Anr. vs Assistant Commissioner CGST & Ors.
|
Citation: W.P. (C) 6503/2025 dated 15.05.2025
|
Authority: Delhi High Court
|
The petition challenges the Order-in-Original dated 02.02.2025 based on a Show Cause Notice (SCN) dated 03.08.2024 A search was conducted, and statements were recorded including that of one Director admitting to the issuance of fake invoices during the Central Excise period. It was alleged that the Petitioner issued goods-less invoices to enable fraudulent Input Tax Credit (ITC) claims amounting to Rs. 1.85 crore.
|
Contentions of the Petitioner:
|
SCN was issued by unauthorized officer, thus, violates Rule 142(1)(a) of CGST Rules. No pre-consultation as required under Rule 142(1A) of CGST Rules was issued. Consolidated SCN for multiple financial years was issued and challenge to such consolidated action is pending in a separate matter (Quest Infotech case).
|
Contentions of the Department:
The impugned order is appealable, hence writ is not maintainable. The Petitioner’s Director admitted to allegations. Natural justice was followed as the Petitioner received the SCN, filed a reply, and availed of personal hearing. Reliance must be made on SC judgments and Allahabad HC rulings emphasizing alternate remedy u/s 107 CGST Act.
|
Findings and Decision of the Court:
The Court refused to interfere under writ jurisdiction, citing:
|
- No breach of fundamental rights or principles of natural justice.
- Availability of a statutory remedy (appeal) under Section 107 CGST Act.
The Court noted that the Allegations involve serious misuse of ITC, requiring fact-based adjudication, not suited for writ jurisdiction. Thus, the Petitioner was granted liberty to file appeal, and if filed with pre deposit, the appeal shall not be dismissed on limitation.
|
|
|
|
|
|
|
|
Synopsis: GST RC cancellation is not justified as petitioner was not given fair opportunity to respond.
|
Case Name: M/s. Genius Orthos Industries VS Union of India & Ors.
|
Citation: WRIT TAX No. 542 of 2023 dated 24.04.2025
|
Authority: Allahabad High Court
|
The petitioner was engaged in the business of surgical goods and its GST registration was cancelled on 19.12.2022 after a physical verification of its premises allegedly found no inputs, finished goods, or workers. A show cause notice was issued prior to cancellation, but the petitioner claimed they were not informed of the specific material findings leading to the cancellation. The appeal against the cancellation was also dismissed.
|
Contentions of the Petitioner:
|
The principles of natural justice were violated, as no proper notice of the specific material against them was given. Cancellation was based on vague grounds, and the watchman at the premises had confirmed that business activities were conducted, albeit irregularly. Rule 25 of the CGST Rules and Form GST REG 30 was not referenced in actual SCN.
|
Contentions of the Department:
|
The petitioner had due knowledge of the discrepancies found during physical verification and failed to provide a satisfactory explanation. Claimed that the cancellation order was justified due to absence of business activity at the registered premises.
|
Findings and Decision of the Court:
|
The High Court found that the cancellation was done without due process, especially considering that:
|
- The material used for cancellation was never properly shared with the petitioner.
- The statement of the watchman indicating occasional business activity was ignored.
- The physical verification report (GST REG-30) was not referenced in the show cause notice.
Thus, impugned cancellation and appellate orders were quashed and the matter was remanded to the proper authority for fresh adjudication within three months, ensuring that a reasoned and speaking order is passed after an Opportunity of hearing is granted. The petitioner may submit relevant evidence.
|
|
|
|
|
|
|
|
Synopsis: Rejection of appeal on ground that appeal was not filed electronically under Rule 108 of CGST Rules, 2017 is invalid in case of non availability of order–in–original on GST portal and Appeal being filed manually.
|
Case Name: M/s Appolo Sesame Industries & Anr. VS Assistant Commissioner of CGST, Division X, Nadiad & Ors
|
Citation: R/Special Civil Application No. 571 of 2025 dated 24.04.2025
|
Authority: Gujarat High Court
|
The petitioners challenged the rejection of their appeal against an Order-in-Original dated 30.10.2023. They had filed the appeal manually in Form GST APL-01, as the order was not available on the GST portal, making electronic filing impossible. Despite this, the Appellate Authority rejected the appeal on 27.09.2024, stating it was not filed electronically, as required under Rule 108(1) of the CGST Rules, 2017.
|
Contentions of the Petitioner:
|
The order-in-original was not available on the portal, so manual filing was the only viable option. A pre-deposit of 10% of the disputed dues was paid. The Appellate Authority ignored the proviso to Rule 108(1), which allows manual filing if the order is unavailable electronically. The Appellate Authority failed to issue the mandatory provisional acknowledgment, despite receiving the appeal.
|
Contentions of the Department:
|
The appeal was filed offline without fulfilling electronic filing requirements. The Appellate Authority argued that procedural rules were not followed, hence the rejection was valid.
|
Findings and Decision of the Court:
|
The High Court found that the Appellate Authority failed to apply its mind to the facts. It held that the rejection of the appeal violated Rule 108(1) of the CGST Rules, as manual filing is permitted when the order is not available on the portal. The impugned rejection order was set aside and the matter was remanded to the Appellate Authority to hear and decide the appeal on merits.
|
|
|
|
|
|
|
|
Synopsis: The demand order was quashed on the ground that the hearing notices must not be merely uploaded on portal but also e-mailed to petitioner.
|
Case Name: Shri Krishna Sales VS Commissioner of Delhi Goods and Service Tax & Ors.
|
Citation: W.P. (C) 5524/2025 dated 29th April, 2025
|
Authority: Delhi High Court
|
Brief facts of the case:
The petitioner challenged the Show Cause Notice (SCN) dated 26.09.2023 and demand order dated 25.12.2023, issued by the Delhi GST authorities. The challenge also extended to Notification No. 09/2023 Central Tax dated 31.03.2023, which extended the time limits for adjudication under Section 73 of the CGST Act. The SCN was only uploaded under the "Additional Notices and Orders" tab on the GST portal and did not come to the petitioner’s notice. The petitioner filed a rectification application, which was considered time-barred.
|
Contentions of the Petitioner:
The SCN and subsequent hearing notices were not properly served, being uploaded in a location on the portal that made them easy to miss. The notification extending limitation was issued improperly under Section 168A without valid GST Council approval and is under challenge before the Supreme Court (SLP No. 4240/2025).The demand order was passed ex parte without giving a fair opportunity to respond.
|
Contentions of the Department:
The SCN was uploaded properly as per current GST portal functionality. The notification extending time limits is valid and backed by GST Council recommendation (in some cases), with related petitions already under consideration in the Supreme Court. The petitioner’s application for rectification was rightly rejected due to limitation bar.
|
Findings and Decision of the Court:
The demand order dated 25.12.2023 was set aside. The Court allowed the petitioner to file a reply to the SCN within 30 days. The hearing notice must be communicated not just through the portal but also via email. The adjudication order shall be passed afresh, after granting a personal hearing. The outcome of this case will be subject to the final decision of the Supreme Court in the pending SLP on the validity of the notifications.
|
|
|
|
|
|
|
|
Synopsis: Notification dated 11.03.2022 & 25.11.2024 confers power to Principal Commissioner Delhi North and Delhi West to issue notices under Section 73 & 74 of CGST Act, 2017.
|
The petitioner challenged a Show Cause Notice (SCN) dated 24.07.2024 and Order-in-Original dated 02.02.2025, issued for alleged fraudulent availment of Input Tax Credit (ITC) through fictitious and non existent firms. The case was based on an extensive investigation involving over 87 entities, and a criminal complaint was also filed under Section 132(1)(b) of the CGST Act, 2017. The petitioner participated in the proceedings and submitted a reply to the SCN but later objected to the jurisdiction of the adjudicating authority.
|
Contentions of the Petitioner:
The personal hearing was improper, and the order was passed without following due process. The authority that adjudicated the matter (CGST Commissionerate Delhi North) lacked jurisdiction. The correct authority was claimed to be CGST Delhi West. A Corrigendum, issued on 28.01.2025 (after the hearing), was alleged to be backdated and manipulated to rectify the jurisdiction issue.
|
Contentions of the Department:
|
The department cited two notifications: Notification dated 11.03.2022 granted jurisdiction to Principal Commissioner, Delhi North and Notification dated 25.11.2024 extended jurisdiction to both Delhi North and Delhi West. The department argued that the adjudicating authority had valid jurisdiction and that due opportunity of hearing was provided to the petitioner. Petitioner’s challenge to jurisdiction was unfounded, and their remedy lies in filing an appeal under Section 107 of the CGST Act.
|
Findings and Decision of the Court:
The High Court held that jurisdiction was validly established via the cited notifications. The petitioner was directed to file an appeal before the Appellate Authority under Section 107. The court clarified that if the appeal is filed within 30 days, along with mandatory pre-deposit, it shall not be dismissed on limitation grounds and shall be heard on merits.
|
|
|
|
|
|
4. GST Notes by CMA Anil Sharma
|
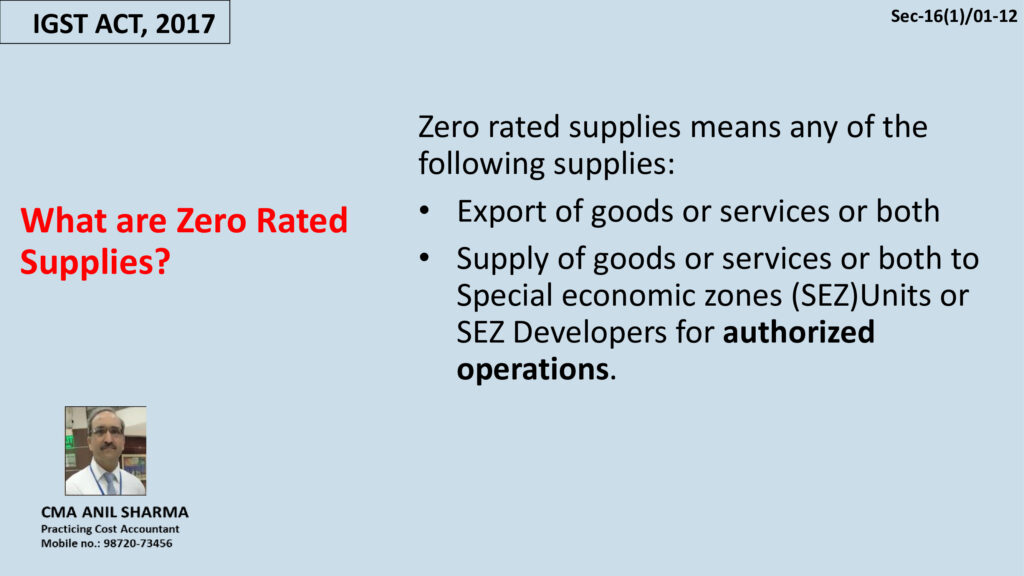
1) Chapter-7 of IGST Act containing 12 slides is added in the Notes section'. It covers POS for inter state transactions including export.
|
Authored by CMA Anil Sharma Sir, with a vision to simply the complex GST Law for taxpayer, professional, taxmen etc.
|
|
|
|
|
|
|
|
|
5. GST Daily by CA Pradeep Modi
CA Pradeep Modi is presenting judgment analysis under title 'GST Daily - Stay yourself updated'
|
|
|
|
|
|
|
Recap of Latest updates posted on 27.08.2026
|
CBIC issued Notification No. 30/2026-Customs dated 21.08.2026 regarding Seeks to exempt 10 lakh MT of raw sugar falling under tariff heading 1701 from the whole of the customs duty leviable thereon under …
|
GSTN is taking downtime to enhance its services on the GST Portal on 26.08.2026 from 12:00 AM onwards until 6:30 am of 26.08.2026.
|
The Hon’ble Supreme Court in M/s G.R. Infra Projects Limited set aside the Show Cause Notice dated June 13, 2025 issued under Section 74 of the CGST Act read with the MPGST Act for the FY 2018-19, and held that a bland and mechanical recital of the words ‘fraud or concealment of facts’,
|
Indian Railway Finance Corporation Ltd received a show cause notice from the GST Authority demanding ₹549.32 crore. The notice, issued under Section 73 of the Central Goods and Services Tax Act, 2017, cites excess input tax credit claims for FY23.
|
The Anti-Corruption Bureau (ACB) on Monday arrested a state tax officer and a senior assistant in Nirmal district for demanding and accepting a bribe of ₹50,000 in connection with a GST audit.
|
CBIC issued Notification No. 71/2026-Customs (N.T.) dated 25.08.2026 regarding Fixation of Tariff Value of Edible Oils, Brass Scrap, Areca Nut, Gold and Silver
|
CBIC issued Notification no. 21/2026-Customs (ADD) dated 21.08.2026 that Seeks to continue applicability of anti-dumping duty on imports of Natural Mica based Pearl Industrial Pigments ..
|
CBDT issued notification no. 115/2026 dated 21.08.2026 to hereby approves deduction under section 45(3)(a)(i) of the Income tax Act, 2025 to the International Institute of Bio Technology and Toxicology , Tamil Nadu for Scientific Research
|
I request the views of tax professionals and TDS experts on the following issue under the Income-tax Act, 2025, regarding reporting in Form 140.
|
|
|
|
|
|
|
|
THE HON'BLE ALLAHABAD HIGH COURT IN THE CASE OF Vibhuti Tyres V/s State of U.P., decided on 7-5-2025
|
✔️ Is it justified that GST order with higher demand than show-cause notice?
|
👉 The Hon'ble High Court Judgement:-
|
✔️ Where in show-cause notice amount representing tax, interest and penalty was indicated as Rs. 8,81,080, but in order, much higher demand was raised at Rs. 32,97,336, same was in violation of section 75(7); matter was to be remanded back.
|
Section 75 of Central Goods and Services Tax Act, 2017
|
|
|
|
|
|
|
|
THE HON'BLE JHARKHAND HIGH COURT IN THE CASE OF Sadanand Prasad Barnwal V/s State of Jharkhand, decided on 8-5-2025
|
✔️ Is it valid if SCN and order under section 73 for lack of digital signature of issuing authority?
|
👉 The Hon'ble High Court Judgement:-
|
✔️ Where both summary of SCN in Form GST DRC-01 and order under section 73 did not bear digital signature of concerned authority, both SCN and order were to be quashed.
|
Section 161, read with section 73 of Central Goods and Services Tax Act, 2017
|
|
|
|
|
|
|
|
THE HON'BLE CALCUTTA HIGH COURT IN THE CASE OF Edelweiss Rural & corporate Services Ltd. V/s Deputy Commissioner of Revenue, decided on 5-5-2025
|
✔️ What would be Refund if business stood closed and registration was cancelled?
|
👉 The Hon'ble High Court Judgement:-
|
✔️ Where Refund sanction order had itself observed that assessees business was closed down, its registration was cancelled and it had no tax dues refund claim was already allowed, direction to credit refund amount to credit ledger instead of bank account of assessee was self-contradictory since there was no business for assessee to take benefit of refund credited to assessees credit ledger.
|
Section 54 of Central Goods and Services Tax Act, 2017
|
|
|
|
|
|
PPT/Handbook on GST
|
GST case Law compendium by CA Shravan Gehlot CLICK HERE
|
|
|
|
6. GST/Income Tax in Media
|
|
|
- ₹5.55 Crore GST Credit Under Scanner, Pharma Company MD Arrested
- GST Fraud: Partner Arrested for Rs 15.78 Cr ITC Claims
- Central GST officer caught accepting bribe in Bengaluru
- 170 vehicles detained, goods worth Rs 5 cr seized: Cheema
- Telangana tax dept holds officers personally accountable for unauthorised AI sharing of taxpayer data
- Tax department turns to AI for sharper scrutiny, compliance
- CBI Catches CGST Superintendent and Consultant Red-Handed in ₹1 Crore Bribery Trap Over New Panvel Flat Redevelopment
- Tax officials barred from sharing taxpayer data with AI tools
- Sirmaur pharma company MD held in Rs 6.55 crore GST refund fraud case
- West Bengal AAR says actual-cost electricity recovery not liable to GST
- Haryana: GST officer, CA held red-handed taking ₹3 lakh bribe
- HDFC Life Insurance faces ₹3,365 crore GST tax demand and penalty after appeal order
- GST data to track Andhra Pradesh’s economic growth live
- Gujarat Assembly passes GST amendment, livestock feed regulation bills
- SBI to use UPI data to lend to small businesses without GST registration
- IAMAI wants 5% GST dropped for app-based rides
- Rajasthan govt seizes 44 vehicles in 3 weeks in tax evasion crackdown
- States reject Gauba panel's push for single, nationwide GST registration
- Maruti sees strong growth as GST 2.0 pushes more customers to upgrade to cars, says Partho Banerjee
- Credai-Gujarat seeks GST clarity on FSI purchases
- Tata Steel gets major Supreme Court relief in ₹890 crore GST dispute
- TN Govt earns ₹50,845 crore from sales tax and excise revenue in liquor, aims for revenue expansion and de-addiction initiatives
- Despite GST Council’s no, legislators in UP, other states want Vidhayak Nidhi outside tax net
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
This is an advance information to the all users – Taxpayers and Tax Officers, of GST System who use Digital Certificate Signature on the GST Portal.
|
CBIC issued Instruction no. 16/2026-Customs dated 18.09.2026 regarding Authorised Officers under Section 25 read with Section 47 (5) of Food Safety Standards (FSS) Act, 2006 and Regulation 13 (1) of FSS (Import) Regulation, 2017 .
|
CBIC issued Instruction no. 17/2026-Customs dated 21.09.2026 giving Clarification in respect of difficulties being faced by field formations in adjudication of cases where Show Cause Notices have been issued under Section 28AAA of the Customs Act, 1962
|
CBDT issued notification no. 120/2026 dated 17.09.2026 to hereby make following rules further to amend the Income tax Rules, 2026 , namely –
|
Input Tax Credit (ITC) as a concept is easy to understand, but it pose challenges when we want to claim the credit.
|
The Hon'ble Supreme Court in M/s Nageen Traders and Molding India Pvt. Ltd. issued notice and stayed the operation of the judgment of the Hon'ble Allahabad High Court, Lucknow Bench, in M/s Nageen Traders and Molding India Pvt. Ltd.
|
Input tax Credit (ITC) should be correctly recorded in the books of accounts. Timely recording in books is of great advantage. It helps in working capital management.
|
Let us see some scenario where Input tax credit claim need critical thinking -
|
The Hon’ble Supreme Court in GVK Jaipur Expressway Pvt. Ltd. issued notice in the Special Leave Petition filed by the Assessee challenging the judgment of the Hon’ble Rajasthan High Court, which had dismissed its writ petition against a total GST demand of Rs. 14,06,54,640/-,
|
|
|
|
|
|
|
|
Recap of Latest updates posted on 17.09.2026
|
CBIC will conduct outreach programmes and handhold MSMEs to encourage them to opt for the Eligible Manufacturer Importer (EMI) scheme, a senior official said on Wednesday.
|
The Superintendent of Central GST, Mohit Pratap Singh, was caught while allegedly accepting a bribe of Rs 8 lakh through a mediator, the Lokayukta said.
|
Keeping track of provident fund and pension-related announcements could become easier for millions of EPFO subscribers, with the Employees’ Provident Fund Organisation (EPFO) launching an official WhatsApp channel.
|
Tax officer imposed a 200% penalty of Rs. 4.85 lakh, but ITAT cut it to Rs. 1.21 lakh.
|
Hon'ble Delhi High Court in case of M/s. Katyani Exports and connected matters decided on 16.09.2026 that the Jurisdiction stood vested by way of the statute and the notifications thereof.
|
The principal issue was framed as ‘Whether the classification should be merely based on the textual entry under Heading 8421 or whether the ‘sole or principal use test’ should be applied?’.
|
The Union government has moved the Supreme Court against a Punjab and Haryana High Court ruling that declared Section 147A of the Income Tax Act unconstitutional, a decision that has raised questions over the validity of reassessment proceedings conducted by jurisdictional tax officers.
|
The September 30, 2026 deadline for filing tax audit reports for assessment year (AY) 2026-27 is fast approaching, but the government has not announced any extension so far.
|
GST officers have arrested a partner of a firm engaged in trading of iron and steel goods for fraudulently availing input tax credit of over Rs 15.78 crore.
|
The Preventive Wing of the Central Goods and Services Tax (CGST) Commissionerate, Shimla, has uncovered an alleged GST fraud involving input tax credit of around ₹5.55 crore in the Kala Amb industrial area of Sirmaur district.
|
GSTN is taking downtime to enhance its services on the GST Portal on 18.09.2026 from 12:00 AM onwards until 2:00 am of 18.09.2026.
|
First of all the taxpayer must ascertain the eligibility of the Input Tax Credit (ITC) on his purchases, expenses and capital goods.
|
The Hon’ble Delhi High Court in Rohit Garg disposed of a batch of writ petitions assailing the SCN and Orders-in-Original (“OIO”) passed under Section 122 of the the CGST Act
|
The Hon’ble Supreme Court in M/s PVCON Engineering Co. issued notice on the question whether the mandatory pre-deposit for preferring an appeal before the Goods and GSTAT in penalty-only matters
|
|
|
|
|
|
|
|
DGFT issued Trade Notice 28/2026-27 dated 16.09.2026 regarding Revision in Timeline for Issuance of PSIC and One-time Relaxation for Issuance of Backlog PSICs
|
Systems of Central Board of Direct Taxes (CBDT) issued notification no. 3/2026 dated 15.09.2026 to prescribe Procedure for registration of reporting person/entity and submission of Form No. 98 as per rule 160 of the Income tax Rules, 2026.
|
Fixation of Tariff Value of Edible Oils, Brass Scrap, Areca Nut, Gold and Silver
|
GSTN is taking downtime to enhance its services on the GST Portal on 17.09.2026 from 03:00 AM onwards until 4:30 am of 17.09.2026.
|
CESTAT, Hyderabad, has upheld relief granted to the Northern Power Distribution Company of Telangana (NPDCL), holding that delayed payment surcharges and meter-testing charges collected from consumers are not liable to service tax.
|
|
|
|
|
|
|
|
Recap of Latest updates posted on 14.09.2026
|
DGFT issued Notification No. 36/2026-27 dated 15.09.2026 regarding De minimis exemption from Registration-cum-Membership Certificate (RCMC) requirements for low-value exports
|
CBDT issued notification no. 119/2026 dated 14.09.2026 to hereby approve the Indian Institute of Technology , Roorkee for Scientific Research under the category of University, college or other institution , for the purposes of Section 45(a)(i) of the Income tax Act, 2025, and rules 32 and 34 of the Income tax Rules, 2026.
|
Central Board of Indirect Taxes and Customs (CBIC) issued Notification no. 22/2026-Customs (ADD) dated 14.09.2026 that Seeks to amend Notification No. 73/2021-Customs dated 17.12.2021 to extend the anti-dumping duty on imports of “Calcined Gypsum Powder” originating in or..
|
GSTN is taking downtime to enhance its services on the GST Portal on 16.09.2026 from 12:00 AM onwards until 2:00 am of 16.09.2026.
|
The Hon’ble Madras High Court (Division Bench) in Principal Commissioner of Customs set aside the order of the Learned Single Judge directing return of the seized currency and held that Indian currency seized during the investigation of fraudulent claims under the Amnesty Scheme of the DGFT, where such currency constituted evidence of Hawala transactions and illegal gratification, is liable to be treated as a “thing” under Section 110(3) of the Customs Act, 1962
|
The Directorate of Revenue Intelligence (DRI) seized more than 362 metric tonnes of Pakistan-origin dry dates under 'Operation Deep Manifest' during an enforcement drive targeting illicit trade conduits.
|
The tax department is increasingly using artificial intelligence (AI), data analytics and information from multiple government databases to identify anomalies, detect potential tax risks and sharpen scrutiny of taxpayers.
|
The Telangana Commercial Taxes Department has issued detailed guidelines governing the use of Artificial Intelligence tools and other third party online platforms by its officers, making individual officers personally accountable for any unauthorised sharing of taxpayer information through such platforms.
|
Punjab’s excise and taxation officials detained 170 vehicles carrying goods suspected to be in violation of GST provisions, officials said on Monday.
|
|
|
|
|
|
|
|
Recap of Latest updates posted on 14.09.2026
|
DGFT issued Trade Notice 27/2026-27 dated 14.09.2026 Inviting comments/suggestions on Amendment in Para 2.93 of the Handbook of Procedures, 2023 – Rules of Origin (Non-Preferential).
|
DGFT issued Public Notice 30/2026-27 dated 14.09.2026 regarding Extension of timeline for surrender of unutilised TRQ quantity allocated for import of 10 Lakh MT of Raw Sugar
|
The Hon’ble Allahabad High Court (Lucknow Bench) in M/s VosslohCogifer Turnouts India Pvt. Ltd. directed the Revenue to disburse the sanctioned refund of Rs. 1,10,72,753/-, which was earlier directed to be re-credited as ITC in the E Cr. L, in cash/ in the bank account of the assessee
|
GSTAT Delhi Bench passed an order on 07.09.2026 directing Registry to conduct the scrutiny of the appeal within three weeks from today.
|
An international passenger was caught trying to smuggle nearly 1.6 kg of gold worth about Rs 2.4 crore by concealing it in his undergarment at Delhi's Indira Gandhi International Airport, officials said.
|
The law may prescribe the limits of liberty; but a judge hearing the bail plea of a prisoner above 75 –who is suffering from health issues – must have the “spine to do justice”.
|
The Preventive Wing of the Central Goods and Services Tax (CGST) Commissionerate, Shimla, has unearthed an Rs 6.55-crore fraud involving fake invoices and fraudulent claims of input tax credit (ITC)
|
Amid the growing use of artificial intelligence in tax administration, the state commercial taxes department has imposed strict safeguards on the use of AI tools by its officials, making them personally accountable for any unauthorised disclosure of taxpayer information through such platforms.
|
The Central Bureau of Investigation (CBI) has arrested Superintendent, Land and Building Section at office of Commissioner of CGST and Central Excise, Raigad and a CGST consultant, in a bribery case.
|
|
|
|
|
|
|
|
Recap of Latest updates posted on 13.09.2026
|
CBDT has issued Notification No. 114/2026 dated 14.08.2026, notifying the rules and prescribed forms under the Foreign Assets of Small Taxpayers Disclosure Scheme, 2026.
|
The tax department cannot tax rental income in the hands of individual landowners if the commercial building was constructed under a joint development agreement (JDA) and the earnings from it have already been disclosed and assessed in the hands of a genuine partnership firm, the Income Tax Appellate Tribunal (ITAT) Bangalore has recently ruled.
|
The app-based mobility industry has pitched for exemption from the 5% goods and services tax (GST), arguing that the levy is being imposed on platforms that often do not collect fares from passengers.
|
State Bank of India, India’s largest lender, is developing a lending solution that will use UPI transaction data as a proxy for sales to extend loans to small businesses that do not have Goods and Services Tax registration
|
The Gujarat assembly on Thursday passed two bills, one amending the Gujarat GST Act to bring it in line with decisions of the GST Council and other seeking to regulate the manufacture, storage, distribution, sale and quality control of livestock and poultry feed.
|
The European Commission has proposed that the European Union approve and conclude its free-trade agreement with India, bringing the long-awaited pact closer to taking effect.
|
Commercial Taxes Department Chief Commissioner Babu A has said that the State is leveraging GST and related commercial tax data to develop a real-time mechanism for assessing economic activity and estimating Gross Value Added (GVA) across key sectors.
|
Two income-tax officials and two others were arrested Thursday for allegedly conducting a fake raid on a Chakala company and demanding Rs 1 crore, taking the total arrests in the case to 10. It was masterminded by a driver sacked by the company three months ago, said police.
|
HDFC Life Insurance Company Ltd on Friday (September 11) said that the Commissioner (Appeals-III), CGST & Central Excise, Mumbai, has confirmed the total Goods and Services Tax (GST) demand, including interest and penalty, in a case involving the period from July 1, 2017 to March 31, 2022.
|
Haryana State Vigilance and Anti-Corruption Bureau (SV&ACB) on Thursday arrested a State GST excise and taxation officer (ETO) and a chartered accountant from Jind as they were caught accepting a cash bribe in connection with a pending tax notice.
|
The Act modernises the legal framework for use of banking records as evidence.
|
The West Bengal Authority for Advance Ruling (AAR) has held that electricity charges recovered by a commercial building maintenance company from occupants at actual cost, without any markup or profit, will not attract Goods and Services Tax (GST).
|
|
|
|
|
Hope the above updates is of use to you. Please share your input and feedback at taxupdate.otu@gmail.com
|
|
|
|
|
|
|
|
 
|
Visit our website
|
OTU provides you
|
- Articles on various topics
|
|
- Media - GST, Income Tax & Press R.
|
|
|
|
|