
Addition of 6% tax rate in GSTR-1 online
01/06/2022It may be noted that 6% tax rate has been added in the item details section of all the tables of form GSTR-1, except HSN table 12. In case your outward supplies attracts 6% tax rate, you are required to upload the details against 6% tax rate in the item details section.
In respect to HSN table 12 of form GSTR-1, 6% tax rate shall be added shortly. Meanwhile, you may report the HSN details of supplies attracting 6% tax rate under tax rate 5% by updating the values/tax amounts as per the actual supplies made by you.
Thanking You,
Team GSTN
Previously below update was issued by GSTN
Reporting 6% rate in GSTR-1
10/05/2022
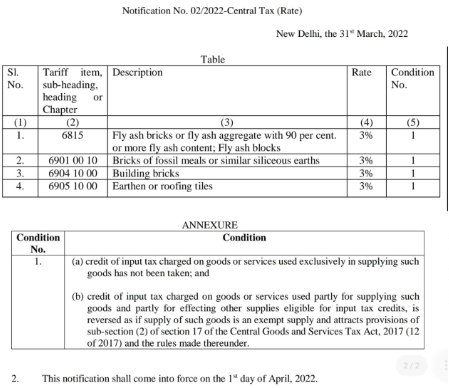
- A new tax rate of 6% IGST or 3% CGST+ 3% SGST has been introduced on certain goods vide Notification No. 02/2022 dated 31st March 2022. Changes are being made on the GST portal to include this rate in GSTR-1. As a temporary measure, taxpayers who have to report goods at this rate may do so by reporting the entries in the 5% heading and then manually increasing the system computed tax amount to 6%. This can be done by entering the value in the ‘Taxable value’ column next to 5% tax-rate and then increasing the system computed tax-amount to 6% IGST or 3% CGST + 3% SGST in the ‘Amount of Tax’ column under the relevant Table, namely B2B, B2C or Export, as applicable. This will ensure that correct tax amount is reported in GSTR-1. Meanwhile, this rate will be made available on the GST portal shortly.
- GSTN regrets any inconvenience caused in this regard.
Thanking you,
Team GSTN
Source: GSTIN News updates
New GST tax rate for certain items in Brick Kilns Sector:
The govt has introduced a new tax rate of 6% IGST or (3% CGST+ 3% SGST) on certain goods vide Notification No. 02/2022 Central Tax (rate) dated 31st March 2022. The summary of the new rate structure is as follows:
- It is applicable to the goods falling under HSN 6815, 69010010, 69041000, 69051000 referred in the notification.
- The new rate of tax for such goods is 12% with ITC or 6% without ITC.
- Suppliers of such goods are no longer entitled to avail composition scheme (@1% rate).
- The turnover limit for compulsory registration for persons dealing in such goods is reduced from 40 lakhs to 20 lakhs.
- This new rate structure is applicable w.e.f. 1st April 2022.

Share this content: